
Can Guardant Health (GH) Justify Its Valuation On Fresh Shield Screening Data?
Guardant Health (GH) just put its colorectal cancer blood test Shield back in the spotlight, releasing fresh real-world and modeling data on screening adherence at the 2026 ACG meeting in Nashville.
Shield’s fresh adherence data lands at a moment when momentum in Guardant Health’s stock has been strong, with a 2.47% 1 day share price return and a 9.74% 7 day gain. This has fed into a 70.29% year to date share price return and a 144.53% 1 year total shareholder return, even after a softer 30 day share price patch and a very large 3 year total shareholder return, which together suggest sentiment has been warming as investors weigh new product data alongside earlier concerns about cash burn and leverage.
Spot momentum in Guardant Health while it is back in focus, and compare it with other fast-moving healthcare opportunities screened through 34 healthcare AI stocks.Guardant Health now trades almost 20% below one intrinsic value estimate and about 14% under the average analyst target after a sharp run. Is that caution about cash burn and debt still doing useful work at this price?
Most Popular Narrative: 13% Undervalued
Guardant Health last closed at $173.25, against a widely followed fair value estimate of $199.04 that implies a discount even after a strong share price move. That gap is built on a story where test volumes, reimbursement decisions, and cost discipline all carry a lot of weight for where the valuation settles.
Substantial regulatory, reimbursement, and clinical validation milestones (including Shield's breakthrough device status, NCCN guideline inclusion, and ongoing pilot studies) are paving the way for further guideline adoption, expanded payer coverage, and commercial inflections in Shield/MCED and Reveal volumes, significantly increasing future revenue and earnings visibility.
See why 22 investors see Guardant Health as 13% undervalued.
Result: Fair Value of $199.04 (UNDERVALUED)
Still, Guardant Health faces real pressure if high R&D spending keeps cash burn elevated or if payer adoption and reimbursement for Shield fall short of expectations.
Find out about the key risks to this Guardant Health narrative.
Another View: Guardant Health Looks Expensive On Sales
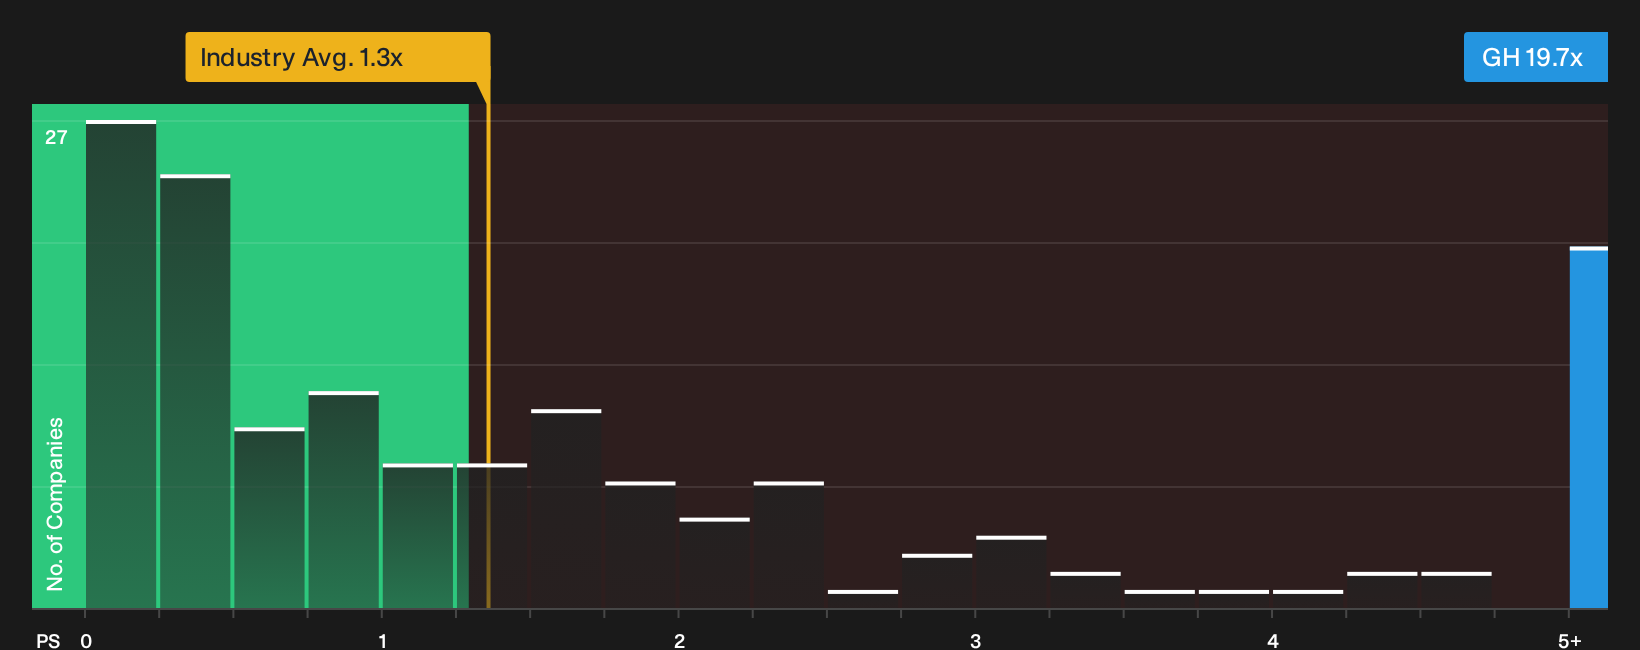
On a simple sales yardstick, Guardant Health screens as rich. The stock trades on a P/S of 19.7x, compared with 1.3x for the wider US Healthcare group and 1.5x for its peer set. The fair ratio sits at 9.8x P/S, which highlights real valuation risk if sentiment cools.
For investors who prefer to anchor decisions on revenue multiples rather than cash flow models, that gap raises a blunt question. Is the current share price rewarding too much future execution before Shield and the broader portfolio fully prove themselves, or does the premium simply reflect where this story now sits in your own risk budget?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Guardant Health so far. If you want to move quickly and base your call on the full risk and reward picture, start by checking 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Guardant Health?
If Guardant Health has sharpened your focus on where risk and reward can really move, do not stop at a single ticker when the wider market is full of mispriced stories.
- Target long term compounding potential by scanning a curated 29 high quality undervalued stocks that pairs strong fundamentals with prices that still lag underlying business quality.
- Strengthen portfolio resilience by searching a list of solid balance sheet and fundamentals (24 results) that can better handle shocks than highly leveraged peers.
- Get ahead of the crowd by reviewing a tightly filtered 21 high quality undiscovered gems before attention and liquidity catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com