
Enova (ENVA) Stock Looks Undervalued As Earnings Keep Supporting The Price
Enova International has logged a powerful multi‑year share price run, and the stock still trades near levels that make many investors pause over what they are really paying for in terms of earnings. With fresh corporate developments on the table, the question now is how well the current price lines up with the profit engine behind the business.
- Over the last 5 years the stock has returned about 389%, which puts real pressure on the question of whether the earnings profile can carry that kind of re-rating.
- Management has leaned into growth and capital returns, with rising originations and ongoing share buybacks that can shape both future profit per share and how the market values Enova’s earnings stream.
- Your read on Enova International is one view; the desks covering it have another. See what analysts think Enova International's shares could be worth.
For investors, the debate is whether Enova’s current share price is properly supported by the earnings it is generating today and is expected to produce over time.
If you are weighing whether Enova International’s recent earnings justify the current share price, a focused stock screen built around 29 high quality undervalued stocks can give you more ideas to research alongside it.
Is Enova International Still Cheap on Earnings?
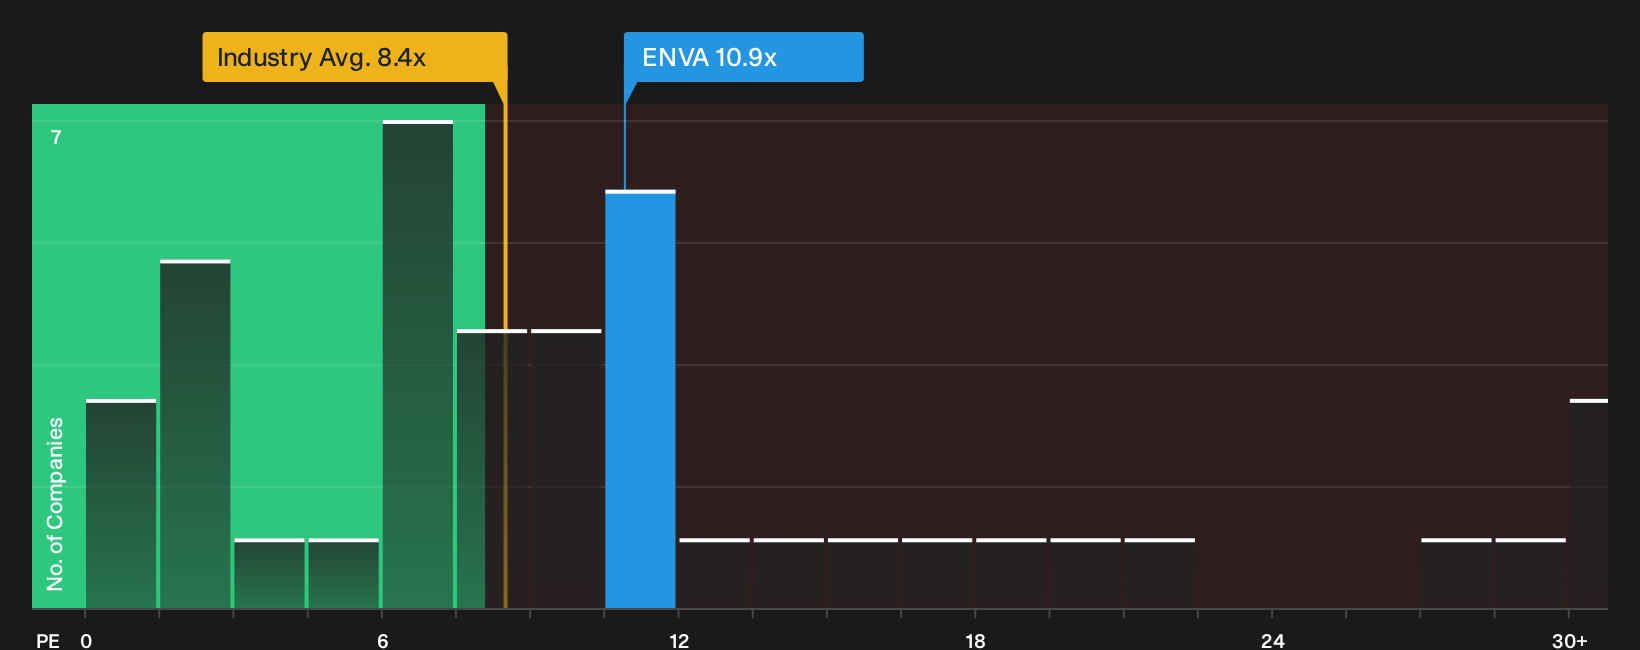
The P/E ratio fits Enova International because earnings remain the key driver of how investors frame value for a lender like this. On current numbers, the stock trades on about 10.9x earnings, which sits below the consumer finance industry average of roughly 8.4x and also under the peer group at about 12.6x. Because the model based on Enova International’s own growth, margins, size and risk profile points to a higher P/E than where the shares trade today, the current multiple screens as undervalued on this framework.
Because Enova recently reported Q3 2026 results with higher originations and earnings, yet the P/E still sits under that tailored fair level and the peer average, the pricing reflects some caution around how durable that profit profile is. For a reader weighing Enova International, the key question is whether the current earnings base and balance sheet justify the market keeping the P/E at this level or closer to that implied fair range over time. Explore the numbers behind Enova International's P/E valuation.
The Enova International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Enova International pick up where the P/E debate leaves off. They spell out what kind of future growth, margins and earnings would need to hold for the stock to look meaningfully cheap or expensive versus today’s price, all housed on the Community page. Each narrative treats Enova International's fair value as a thesis that can be tracked over time, rather than a one off snapshot, so you can see how the story holds up as new results arrive.
One of the top community narratives on Enova International: 29% undervalued
"Enova International's use of advanced machine learning and AI for real time, data driven credit risk management is now extending into generative AI and automated final decisioning at OnDeck…"
Discover why this Narrative puts Enova International at 29% undervalued.
One more question before you move on from Enova International
Price multiples and narratives tell only part of the story. Analyst models sketch out where they think earnings and the business could be a few years from now, which gives you a different reference point beside today’s valuation. Explore where analysts expect Enova International to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com