
Dear SK hynix Stock Fans, Mark Your Calendars for October 28
SK hynix (SKHY) will report third-quarter earnings on Wednesday, Oct. 28, giving investors another look at one of the companies supplying a critical ingredient in the artificial intelligence (AI) boom: memory.
Nvidia (NVDA) may get most of the attention for its powerful AI processors, and AMD (AMD) and Alphabet (GOOG) (GOOGL) make powerful chips of their own. But regardless of which company makes the processors, chips also need enormous amounts of memory to handle the data used to train and run increasingly sophisticated AI models. That's made memory manufacturers such as SK hynix, Micron Technology (MU), and Samsung Electronics (SMSN.L.IX) important players in the AI infrastructure buildout.
SK hynix has been particularly successful at capitalizing on that demand.
The South Korean company is a leading supplier of high-bandwidth memory (HBM), which stacks memory chips vertically to deliver data to AI processors at much higher speeds than conventional DRAM. The technology is especially essential for Nvidia's AI accelerators, where moving data quickly is essential to maximizing performance.
But SK Hynix's leadership is facing a serious challenge.
According to an Oct. 26 report in The Korea Herald, Bernstein estimates that Samsung overtook SK hynix in third-quarter HBM revenue. The research firm calculated that Samsung generated $8.7 billion in HBM sales during the quarter, compared with $7.6 billion for SK hynix.
Those figures are estimates based on semiconductor export data, not confirmed company results. Still, they suggest that Samsung is making progress in a market SK hynix has dominated.
Competition is intensifying as manufacturers transition to HBM4, the next generation of high-bandwidth memory. Both Samsung and SK hynix are competing to supply Nvidia's upcoming Vera Rubin AI platform, making production capacity, performance, and customer relationships increasingly important.
SK hynix isn't standing still. During its July earnings announcement, the company said it had finalized long-term supply agreements with approximately 10 customers. Those arrangements could provide greater visibility into future demand while reducing some of the uncertainty that has historically characterized the cyclical memory business.
The company also began large-scale HBM4 shipments during the second quarter and has been expanding manufacturing capacity to address growing demand.
And demand isn't limited to specialized AI memory. AI infrastructure spending is also increasing the need for conventional DRAM and NAND flash memory, giving SK hynix additional opportunities beyond HBM.
Wednesday's earnings report should offer a clearer picture of how successfully SK hynix is translating that demand into sales—and whether Samsung's advances are beginning to affect its competitive position.
About SK hynix Stock
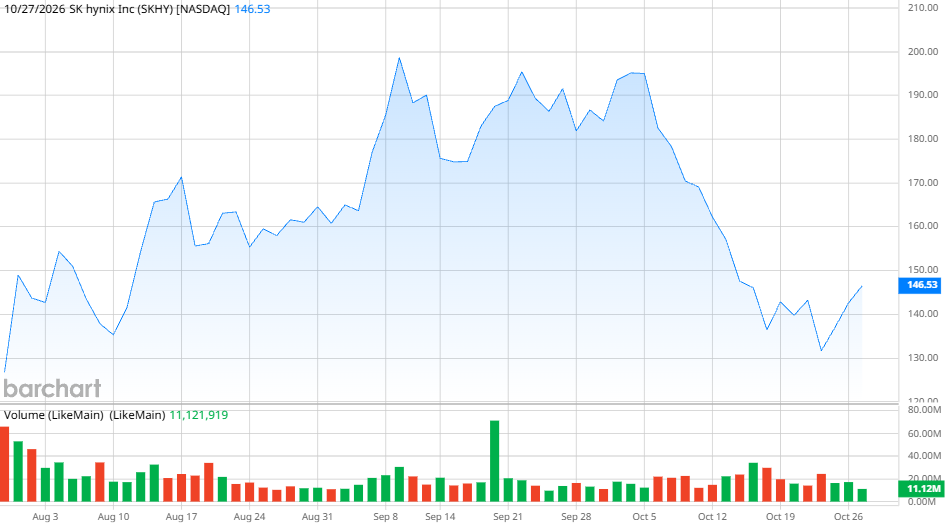
With a market capitalization of just over $1 trillion, SK hynix is one of the biggest companies in the world. The South Korean company has been trading on the Korea Exchange since 1996 but didn’t make its public debut on U.S. exchanges until this July. The company priced its U.S. IPO at $149 a share, and the stock is trading slightly under that at this writing.
Revenue in the second quarter was 79.32 trillion won ($59.8 billion). The company reported operating profit of 60.54 trillion won, giving it an operating margin of 76%, and net profit of 93.92 trillion won (amplified by more than 63 trillion won in investment gains). The company said its revenue was up 257% from a year ago, while operating profit increased 557%.
“With major tech companies increasing their AI infrastructure investments, additional supply requests continue to mount. As these investments are supported by revenue generated from AI services, the momentum in memory demand is expected to persist,” the company said in its earnings statement.
What Do Analysts Expect From SKHY Stock?
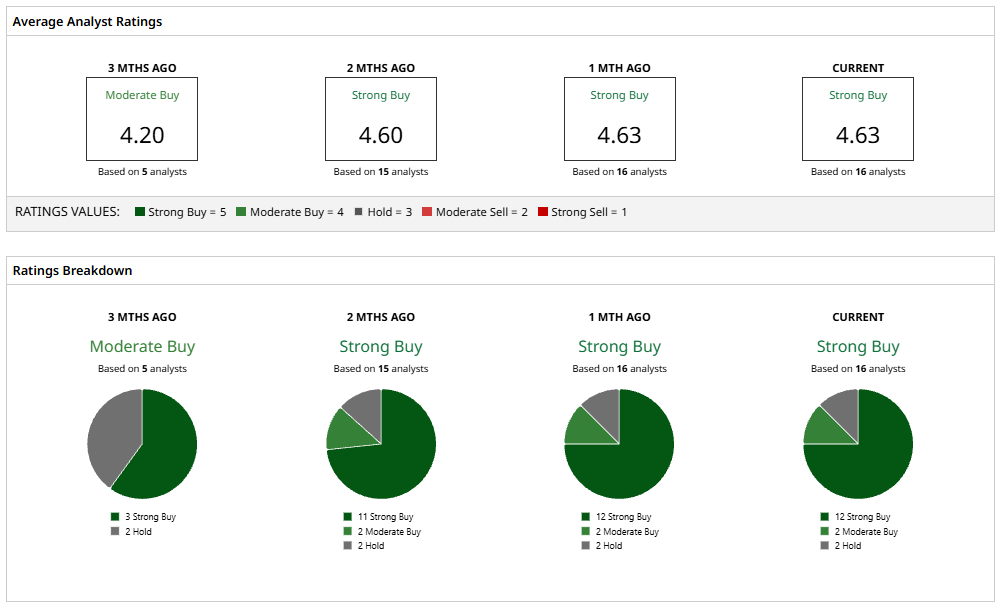
The company appears set for another blowout quarter, with analysts posting a consensus estimate of 99.59 trillion won in revenue ($75.3 billion), up more than 300% from a year ago. That helps explain why analysts are so bullish on the stock; 16 analysts surveyed by Barchart have a consensus “Strong Buy” recommendation, with a mean price target of $253.36 that represents a potential upside of 73%.
But while all signs point to a strong earnings report, investors shouldn't assume its early HBM leadership will guarantee continued dominance.
Samsung's apparent gains demonstrate that the competition is getting tougher, even as demand for advanced memory continues to expand. Meanwhile, SK hynix's long-term customer agreements and expanding HBM4 production provide reasons to believe the company can remain an important supplier.
Wednesday's earnings report should help investors determine whether SK hynix can maintain its competitive advantages while meeting growing demand.
On the date of publication, Patrick Sanders had a position in: NVDA . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.