
Learn Why The Bull Case For Devon Energy Stock Could Change Following Merger Synergy Progress
- Devon Energy has closed its merger with Coterra and is targeting at least US$1b in annual cost synergies by year end 2027, while management continues to frame free cash flow as the main financial yardstick despite a recent quarter of reported free cash flow shortfall.
- European natural gas prices recently reached a near four year high, which has drawn fresh attention to liquefied natural gas exposed producers such as Devon Energy as investors reassess how sustained pricing support could interact with the merger integration plan and free cash flow goals.
- Investors will now be watching how Devon Energy's focus on US$1b of merger related synergies could reshape the investment narrative around its cash generation.
Scan beyond Devon Energy and see how other gas exposed producers stack up on free cash flow strength and balance sheet resilience by using our hand picked list of solid balance sheet and fundamentals (24 results).
Devon Energy Investment Narrative Recap
To own Devon Energy here, you need to be comfortable tying your thesis to free cash flow durability, efficient shale execution and integration of the Coterra assets. The near four year high in European gas prices helps sentiment around liquefied natural gas exposed producers, but it does not remove the operational reality of high decline U.S. shale basins and the need to keep capital discipline tight.
The most important short term catalyst is clear delivery against the US$1b annual cost synergy target by year end 2027, along with visible improvement in free cash flow after the recent shortfall quarter. The biggest risk is that higher sustaining capital, basis pressure on U.S. gas or midstream cost creep dilute those merger benefits and leaves cash generation below what the current story implies.
The Coterra merger and the explicit US$1b synergy goal form the announcement that most directly links to today’s gas price backdrop. Devon Energy is now more exposed to gas and LNG linked pricing, so investors are likely to focus on whether integration work, AI driven cost reductions and midstream projects can convert that exposure into steadier cash, rather than just more volume.
Execution on the more than 350 synergy initiatives, plus the build out of projects like Blackcomb and the Solitude Pipeline System, feeds directly into that question. If Devon Energy keeps translating these projects into lower unit costs and more protected realized prices, then the combination of merger benefits and firm transportation could remain a key operational catalyst, while delays or cost overruns would raise the risk that synergies are slower to show up in reported free cash flow.
Devon Energy's narrative projects US$25.4b revenue and US$5.3b earnings by 2029. This is based on an assumed 10.6% yearly revenue increase and an earnings increase of about US$2b from US$3.3b today.
Uncover why Devon Energy's fair value indicates a 17% potential upside to its current price that could narrow quickly.
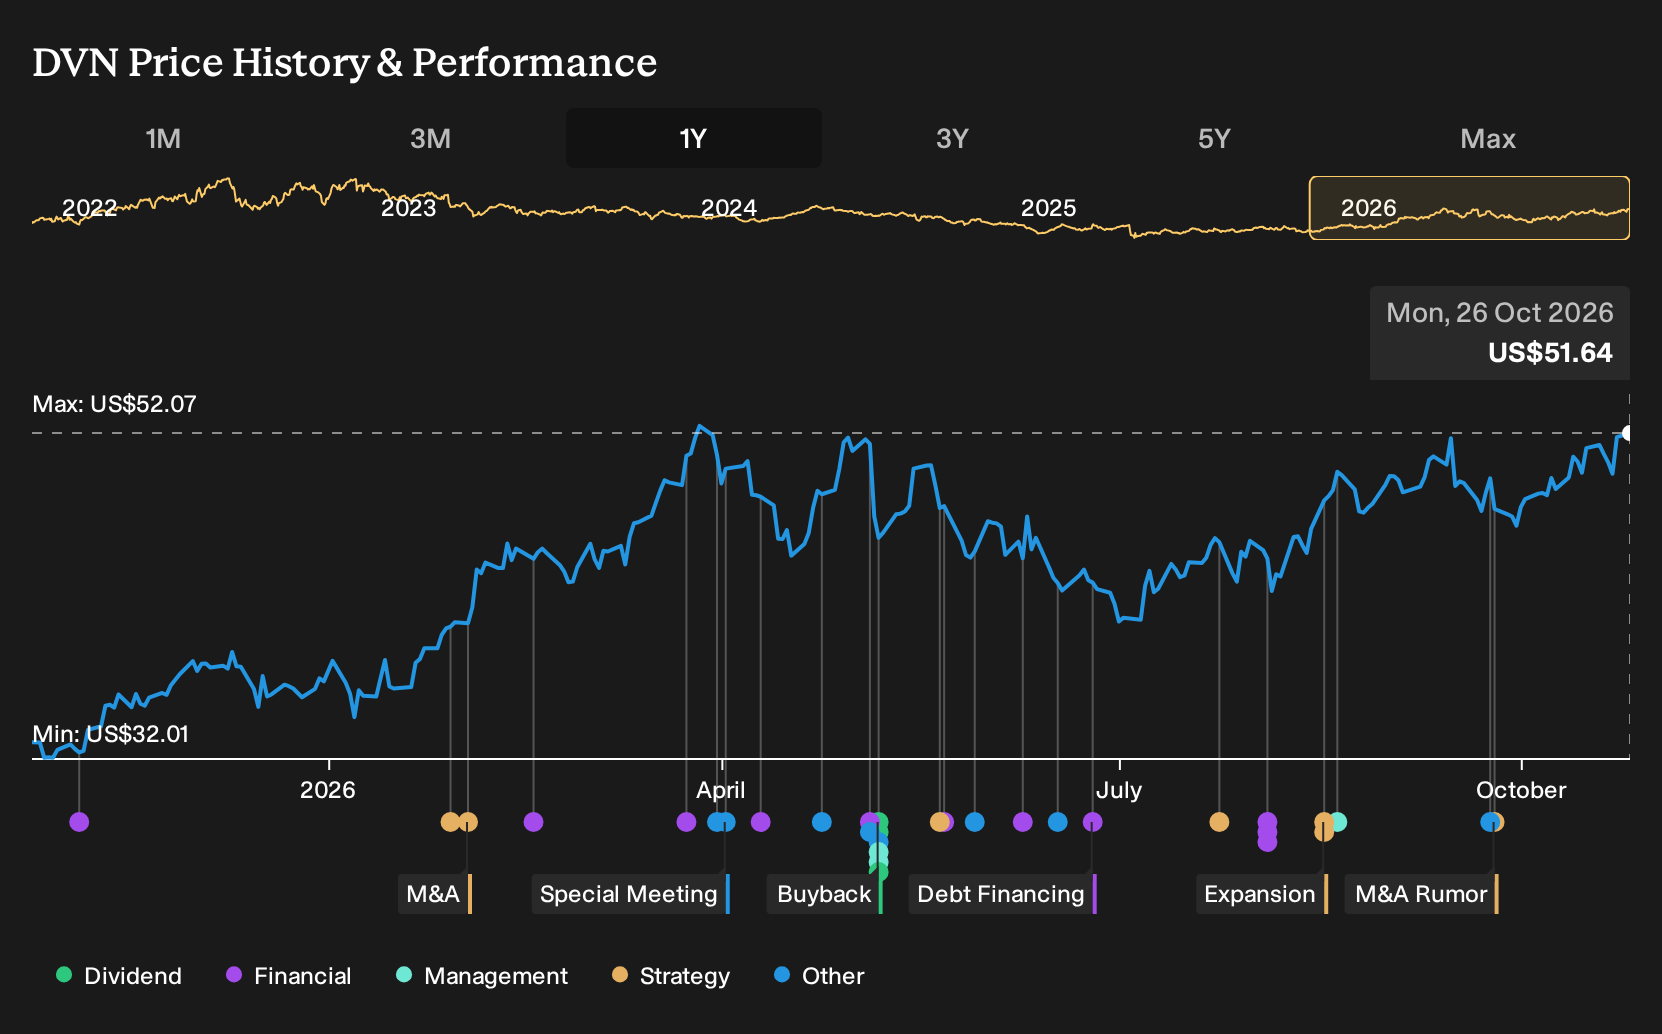
Exploring Other Perspectives
One alternate view puts regulation risk at the center of the Devon Energy story. The lowest analysts were pencilling in about US$22.6b of 2029 revenue and US$5.5b of earnings before this gas price spike, and see the stock as roughly fairly priced. That is a much more cautious narrative. Use it as a prompt to compare several viewpoints before deciding how this news might reshape your own expectations.
Explore 6 other Devon Energy fair value estimates, including one that suggests it could be worth just $49.62.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Devon Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Devon Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Devon Energy's overall financial health at a glance.
Looking for more investment ideas beyond Devon Energy?
If the Devon Energy story has sharpened your thinking on cash generation and balance sheet quality, use that same lens to scan a wider field of opportunities with the Simply Wall St Screener.
- If income stability is your priority, check out a group of potential yield candidates through our 5 dividend fortresses.
- For investors hunting for quality at a reasonable price, start with companies that screen well on value and fundamentals using our 29 high quality undervalued stocks.
- If downside risk control matters most to you, narrow your watchlist to businesses that score well on resilience through our 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com