
Sandfire Resources (ASX:SFR) Could Be 15% Undervalued As Motheo Progress Lifts The Growth Case
Sandfire Resources (ASX:SFR) is in focus after recent progress at its Motheo Copper Mine in Botswana, where management is working to optimise operations, lift ore throughput and extend mine life through drilling and feasibility work.
Recent trading shows that Sandfire Resources has given back some steam in the short term, with a 30 day share price return down 12.33% and a 7 day share price return lower by 3.44%, even though the year to date share price return is 9.00% and the 1 year total shareholder return sits at 28.87%. This backs up a very large 3 year and 5 year total shareholder return that suggests longer term momentum has been strong.
Scan the copper space beyond Sandfire Resources by comparing its Motheo progress and returns with a curated set of 16 top copper producer stocks.
After a strong multi year run and a softer past month, the question for Sandfire Resources now is whether most of the Motheo upside is already priced in or if valuation still leaves meaningful headroom.
Most Popular Narrative: 15% Undervalued
On the most followed narrative, Sandfire Resources screens as undervalued, with a fair value of A$22.97 against a last close of A$19.62, so the gap now hinges on how durable Motheo and MATSA prove to be.
Sandfire's ramp-up and optimization of the Motheo Copper Mine in Botswana is expected to deliver sustained step changes in ore output and revenue. Ongoing investment in infill drilling and pre-feasibility studies at Motheo (A1, A4, T3) position the company to extend mine life towards the 15-year target at processing hubs, supporting long-term revenue growth and production visibility.
See why 27 investors see Sandfire Resources as 15% undervalued.
Result: Fair Value of A$22.97 (UNDERVALUED)
Still, that 10% cost guidance lift and heavy Motheo and MATSA capital spend could squeeze cash generation if copper prices or operating performance disappoint.
Find out about the key risks to this Sandfire Resources narrative.
Another View: SWS DCF Flags Overvaluation
The analyst narrative points to Sandfire Resources looking about 15% undervalued at A$22.97 fair value versus the A$19.62 share price. The SWS DCF model tells a different story. It estimates fair value closer to A$11.13, which frames the stock as expensive and raises the question of which set of assumptions investors may consider more reliable.
Look into how the SWS DCF model arrives at its fair value.
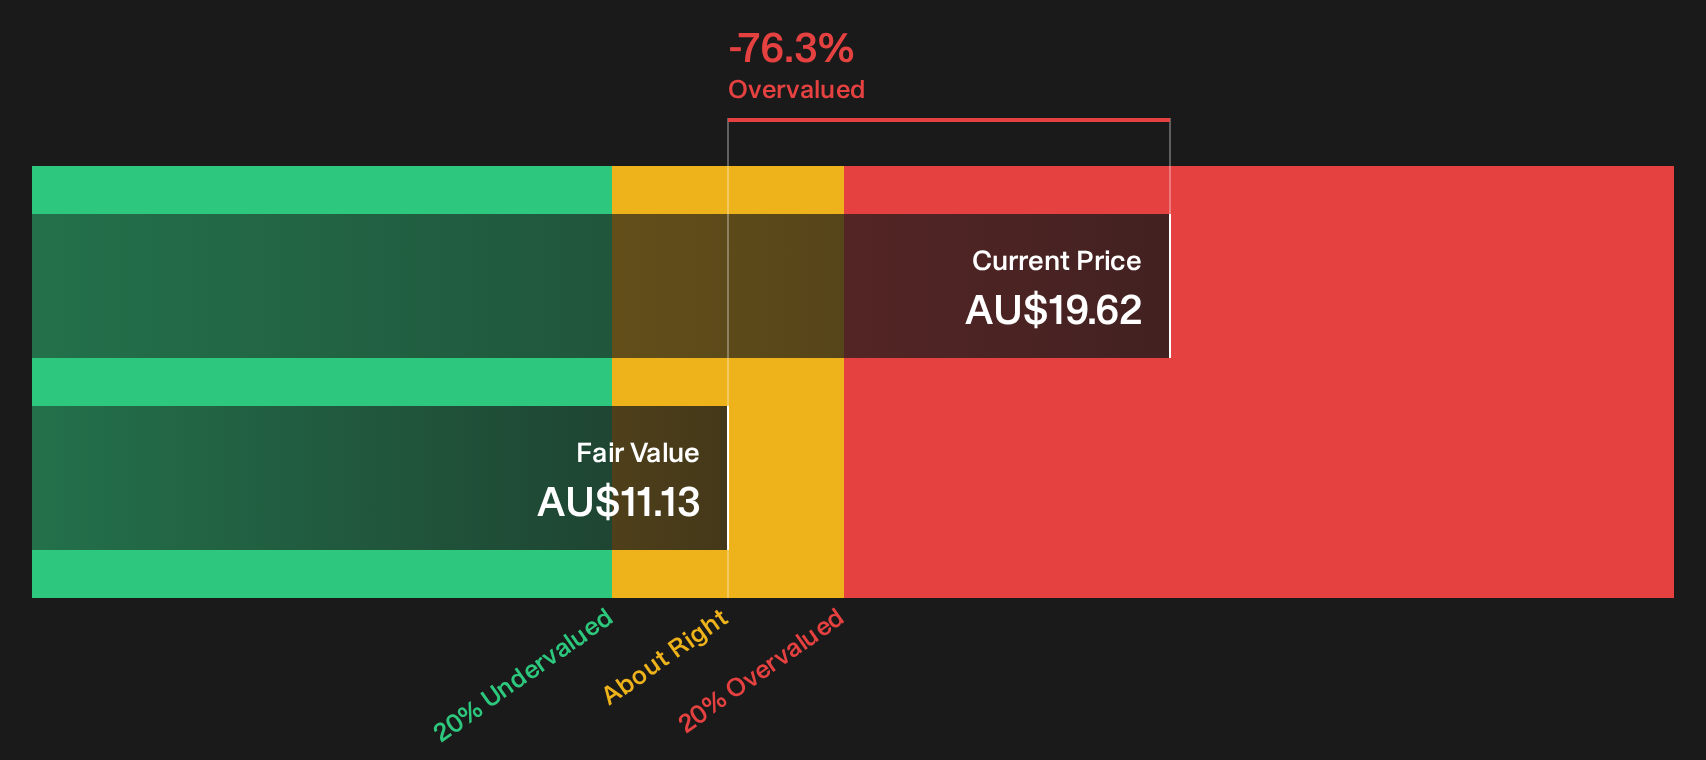
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sandfire Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Sandfire Resources can either feel confusing or like an opening if you move quickly and check the underlying data for yourself. To weigh up whether the potential rewards justify the concern around risks, start by reviewing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Sandfire Resources?
If Sandfire Resources has your attention, do not stop here. Broaden your watchlist now so you can compare opportunities and avoid missing stronger risk reward profiles.
- Target value first and scan a curated 2 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritise resilience by checking a list of solid balance sheet and fundamentals (12 results) so you focus on companies with sturdier finances backing their operations.
- Spot potential early and sift through a 15 high quality undiscovered gems that highlights lesser known stocks with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com