
Arm Holdings (ARM) Could Be 48% Undervalued After Qualcomm Verdict And Axiado Data Center Push
A jury verdict accusing Arm Holdings (NasdaqGS:ARM) of breaching its Qualcomm Architectural License Agreement sits alongside fresh AGI CPU data center plans with Axiado, giving investors two very different signals to weigh.
Arm Holdings has seen a sharp reset in momentum over the past month, with a 1-day share price return of 6.19% at US$223.35 coming after a 30-day share price decline of 28.03%, even as the year-to-date share price return sits at 94.67% and the 3-year total shareholder return is very large at about 4.7x. This suggests investors are weighing the legal setback against longer term enthusiasm for Arm’s AI and data center ambitions.
Scan how other AI infrastructure plays are reacting to similar catalysts by running through our hand-picked 55 AI infrastructure stocks alongside Arm Holdings today.
That sharp swing in Arm Holdings now forces a basic question. Are you seeing the early impact of legal and supply frictions on the business, or a fast reset in investor mood that valuation already reflects?
Most Popular Narrative: 48% Undervalued
Against the last close at $223.35, the most followed narrative for Arm Holdings anchors on a fair value of $430, which frames the recent pullback as a valuation gap rather than just volatility.
The issue is not operating quality. The issue is that the market is capitalizing a large part of the FY2031 dream today.
So the thesis is not “Arm is cheap.” It is: Arm may be one of the most strategically important companies in computing, but the stock already assumes a very large part of that future.
See why 44 investors see Arm Holdings as 48% undervalued.
Result: Fair Value of $430 (UNDERVALUED)
Still, the Qualcomm verdict and ongoing FTC scrutiny around Arm Holdings’ AGI CPU plans could quickly flip this undervalued narrative if the outcomes skew against the company.
Find out about the key risks to this Arm Holdings narrative.
Another View: Cash Flows Point The Other Way
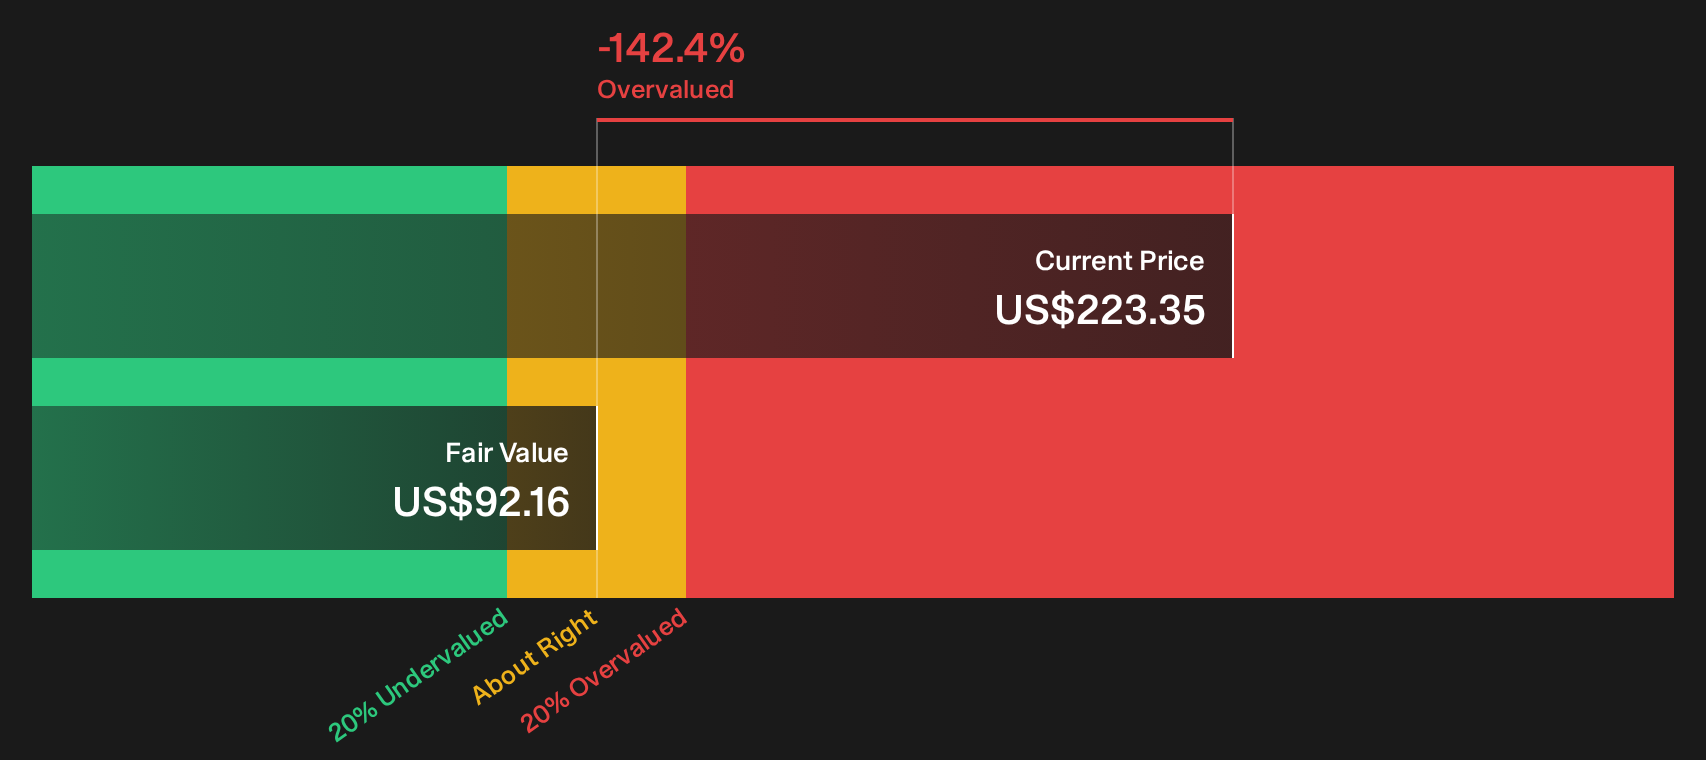
That $430 fair value anchor comes from a narrative style model built on Arm Holdings' long term revenue and EPS ambitions. A very different picture comes from our DCF model, which estimates future cash flow value at $92.16 per share, well below the current $223.35 price. Which lens do you trust more right now?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Arm Holdings and its valuation can feel noisy, so move quickly, check the underlying numbers for yourself, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Arm Holdings?
If Arm Holdings has your attention, broaden your watchlist now by stress testing other opportunities with clear frameworks rather than chasing the loudest headlines.
- Target potential mispricing by reviewing companies that screen as 29 high quality undervalued stocks before momentum fully catches up.
- Strengthen your income layer by focusing on businesses in our list of 5 dividend fortresses while yields still look appealing.
- Reduce portfolio fragility by filtering for resilient businesses through the 30 resilient stocks with low risk scores so you are not caught off guard by the next shock.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com