
Alkane Resources Stock In Focus After High Grade Nagambie Drill Results
- Alkane Resources reported initial drilling results from the Nagambie earn-in, where A$12.5 million of planned spending targets high grade gold-antimony mineralisation. The results confirm wide mineralised zones and deeper C2 vein extensions.
- The combination of wide gold-antimony intercepts and mineralisation traced more than 100 m below the previously known C2 extent points to a larger, still-open epizonal system that could influence how Alkane Resources allocates future exploration capital.
- We will now look at how Alkane Resources' investment narrative could be affected by deeper high grade Nagambie vein extensions.
Compare Alkane Resources’ Nagambie and Peak Hill drilling story with other high potential precious and critical metals opportunities screened in our 34 best rare earth metal stocks list.
Alkane Resources Investment Narrative Recap
To hold Alkane Resources, you need to believe that its producing gold assets can keep funding a heavy exploration program without eroding returns. In the short term, the focus is on whether new drill results at Nagambie and Peak Hill can support mine life options or future developments without stretching capital or operational bandwidth.
The main near-term risk still sits with high exploration and growth spending that may not convert into viable ounces, especially if gold or antimony prices soften. The latest Nagambie intercepts look positive for scale, but on their own they do not yet change the core risk-reward balance for the business.
The Nagambie earn-in announcement is the most relevant update here. Alkane Resources has committed A$12.5 million over three years to reach 60% ownership, with a path to 80% through additional spending. Early drilling has returned multiple high-grade gold-antimony veins and wide mineralised zones, including extensions to the C2 vein 115 m deeper than previously defined.
For catalysts, Nagambie now sits alongside Tomingley, Peak Hill and Northern Molong as part of Alkane Resources’ pipeline that could support future production options and diversify revenue beyond the current mines. Execution risk rises with every additional project, so investors will likely watch how management sequences capital, rigs and studies across this broader portfolio.
Alkane Resources' current analyst narrative assumes revenue of A$1.1b and earnings of A$370.5 million by 2029, based on 5.4% yearly revenue growth and an earnings increase of about A$141.8 million from A$228.7 million today.
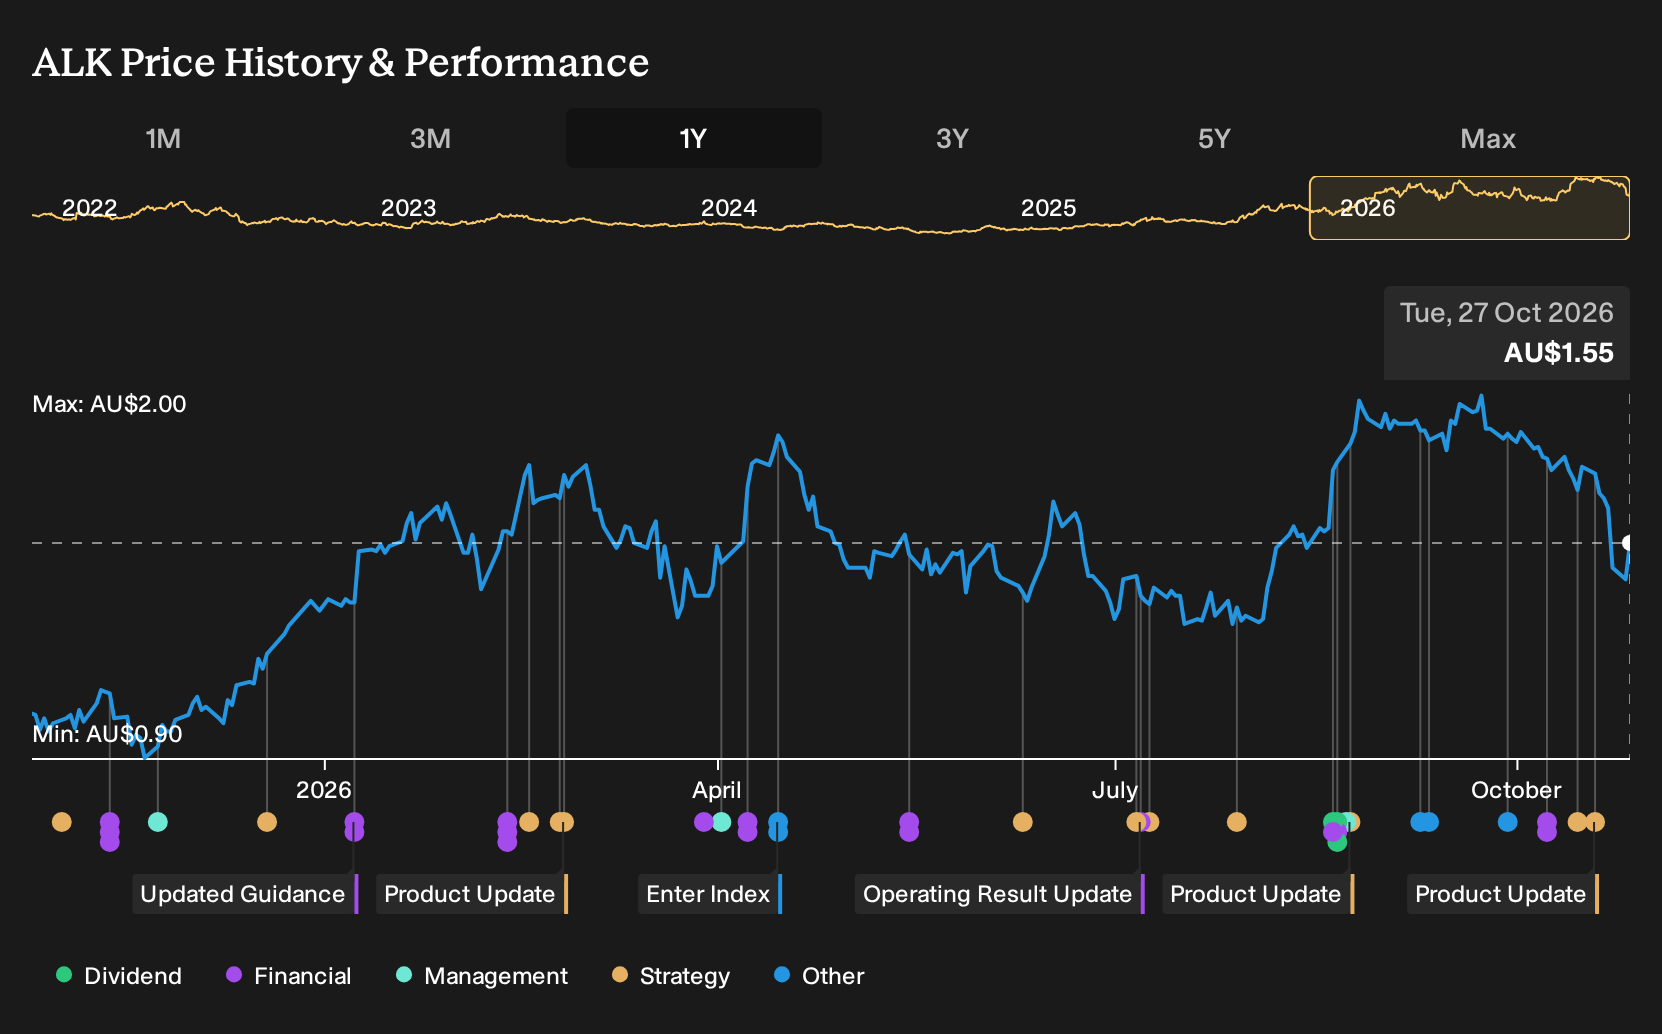
Discover why Alkane Resources' fair value points to a 48% potential upside from its current price, and why this gap could close quickly.
Exploring Other Perspectives
One alternate view puts far more weight on the risk that heavy Nagambie and Peak Hill spending does not translate into lasting production. The most cautious analysts were only pencilling in about A$957.6 million of revenue and A$242.0 million of earnings by 2029 before this drilling news. That is a much cooler Alkane Resources story. Use this surprise set of intercepts as a prompt to compare both narratives yourself and decide which one you believe better reflects how the projects might evolve.
Explore 5 other Alkane Resources fair value estimates, including one that suggests it could be worth just A$1.80.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alkane Resources research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alkane Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alkane Resources' overall financial health at a glance.
Looking For More Ideas Beyond Alkane Resources?
If the Alkane Resources story has you thinking about how to spread your risk and spot fresh opportunities, it can help to look across a wider set of companies that share some of the qualities you care about most.
- If capital protection is top of mind, focus on businesses that score well on resilience and balance sheet strength through the 6 resilient stocks with low risk scores.
- For investors who want a mix of quality and value, scan for companies with strong fundamentals trading below their estimated worth using the 2 high quality undervalued stocks.
- When cash flow consistency matters, concentrate on payout-focused companies that aim to return a meaningful yield to shareholders by reviewing the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com