
How Valuation Debate Will Impact Elkem (OB:ELK) Investors
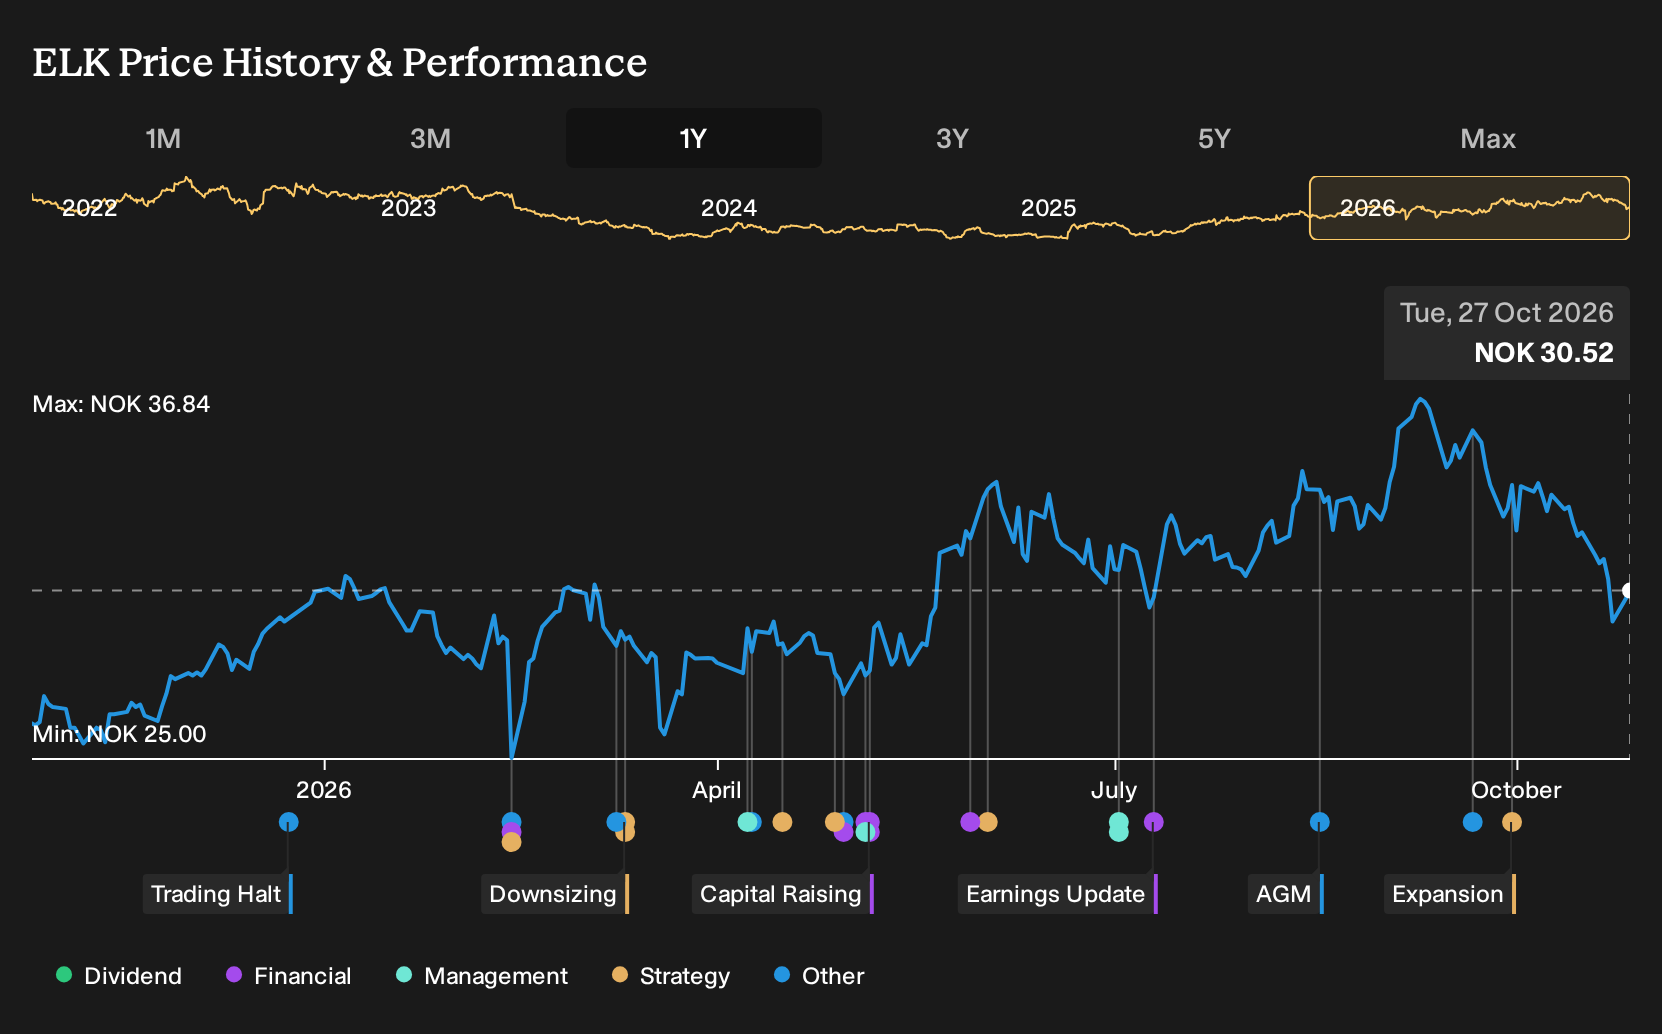
- Elkem is in focus as its current P/E ratio sits above the chemicals sector average but below a calculated Fair Ratio, reflecting market interest in how its earnings power compares with peers.
- The gap between Elkem's present valuation and the higher Fair Ratio estimate highlights an active debate about whether its earnings potential is fully recognised.
- Next, the discussion will look at how Elkem's valuation gap and perceived earnings power might reshape the broader investment narrative.
Scan how Elkem's valuation story compares with other earnings focused opportunities by jumping into a curated set of 195 high quality undervalued stocks that may not yet reflect their full potential.
Elkem Investment Narrative Recap
To own Elkem, you need to believe its silicone, silicon products and carbon solutions portfolio can convert exposure to automotive, construction and electronics into steadier earnings over time. The recent share price move and P/E discussion mostly affect sentiment. They do not materially change the near term operational swing factors, which still sit in volumes, pricing and power costs.
The most important short term catalyst is progress on the Silicones division review and underlying demand in China and the EU. The biggest risk remains weak end markets and pressure on silicon and ferrosilicon prices, especially if maintenance stops or power curtailments persist and keep margins thin.
Recent commentary around the Silicones division review ties directly into this valuation debate on Elkem. A clear outcome on whether the unit is retained or sold could reshape how investors think about the earnings mix, capital allocation and the appropriate P/E range for the business.
For you as a shareholder, the key questions are whether the review leads to a cleaner segment focus and whether operational improvements in China actually support revenue and margins. Any delay, or a decision that leaves income streams from Silicones unclear, would keep risk elevated while the stock trades above sector P/E but below the calculated Fair Ratio.
Elkem's current analyst narrative points to revenues of NOK 19.7b and earnings of NOK 2.7b by 2029. This is based on an assumed 7.0% yearly revenue growth rate and an earnings increase of about NOK 2.4b from NOK 278.0m today.
Uncover how Elkem's fair value indicates a 28% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternative view on Elkem leans heavily on the NOK 1.8b equity raise and €1b refinancing. Some analysts highlight this stronger balance sheet as a key factor, backing forecasts of NOK 22.5b revenue and NOK 3.4b earnings by 2029. These pre news projections could shift, so compare several viewpoints before deciding what feels reasonable.
Explore 3 other Elkem fair value estimates, including one that suggests as much as 167% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Elkem research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Elkem. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elkem's overall financial health at a glance.
Looking For More Ideas Beyond Elkem?
Once you have a view on Elkem, it can help to widen the lens and compare it with other opportunities that match your preferred balance of quality, risk and income.
- If you are hunting for companies that appear mispriced relative to their fundamentals, scan a curated 195 high quality undervalued stocks that might align more closely with your return and risk expectations.
- If resilience and financial strength matter most to you, focus on businesses highlighted in our list of solid balance sheet and fundamentals (207 results) that can help anchor a more defensive core to your portfolio.
- If you want income to do more of the heavy lifting, weigh Elkem against a hand picked 224 dividend fortresses that could complement your cash flow goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com