
Did Earnings Beat Just Shift Celestica's (TSX:CLS) Investment Narrative?
- Celestica reported Q3 2026 results with US$5.83b in sales and US$397.2m in net income, alongside higher full year 2026 revenue guidance of US$21.0b and fresh targets for Q4 2026 and 2027.
- The company tied its raised outlook and new US$40b 2027 revenue goal to what management described as an AI infrastructure supercycle supporting multi year demand.
- We will now examine how Celestica's raised revenue outlook and AI infrastructure supercycle message could reshape the broader investment narrative.
Celestica Investment Narrative Recap
Owning Celestica means buying into the idea that hyperscaler AI infrastructure programs can support a much larger, more profitable manufacturing and hardware solutions platform. The raised 2026 revenue guidance to US$21.0b and new 2027 outlook put execution on these AI programs front and center as the key near term catalyst.
The biggest operational risk still sits with customer concentration and capital intensity. Large AI orders from a handful of hyperscalers and heavy 2026 CapEx need to convert into durable program volumes. The latest results help confidence in the near term, but do not change that sensitivity if orders are delayed or resized.
The new US$40b 2027 revenue target is the announcement that really reframes this update. It ties Celestica’s recent Q3 beat directly to a multi year build out of AI racks and networking systems, and makes program execution on large OpenAI and AMD related platforms even more important for the story.
That longer term goal also raises the stakes around existing risks such as the patent dispute over power delivery modules and the elevated CapEx profile. Any restriction on AI related systems or slower utilization of new Thailand and Texas capacity would matter more against a US$40b ambition. Monitoring order visibility and legal outcomes becomes critical.
Celestica’s analyst narrative points to revenues of $55.4b and earnings of $3.8b by 2029, anchored to assumptions of 52.6% yearly revenue growth and an earnings increase of about $2.7b from $1.1b today.
Uncover why Celestica's fair value indicates a 98% potential upside to its current price that could narrow quickly.
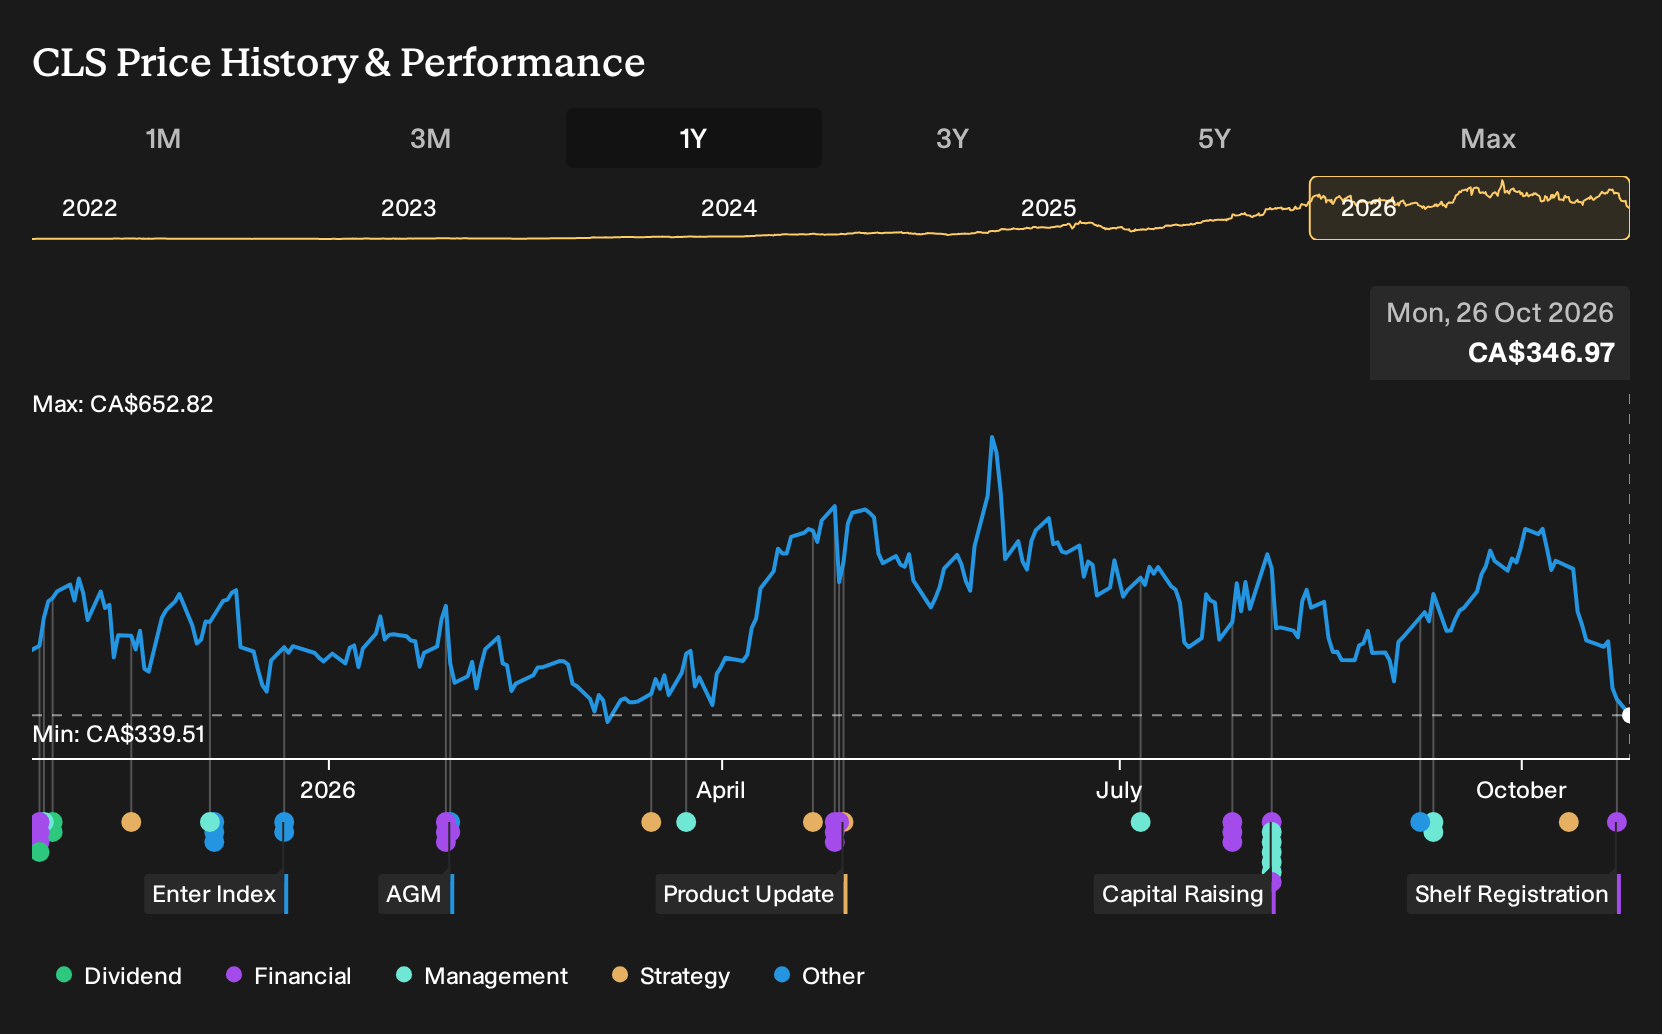
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$666.8 and US$790.4 per share, which signals a tight yet high conviction range from different individual models. Those views sit beside concentration risk, heavy AI driven CapEx, and an unresolved patent dispute, so you need to weigh sharply different opinions and explore more than one angle on Celestica.
Explore 2 other Celestica fair value estimates, including one that suggests as much as 128% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Celestica research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Celestica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Celestica's overall financial health at a glance.
Looking for more investment ideas beyond Celestica?
If the Celestica story has sharpened your view on AI infrastructure, broaden that lens. The Simply Wall St Screener lets you quickly filter for other businesses that might fit your risk comfort, income needs, or value focus so you can build a watchlist that feels intentional rather than random.
- If capital preservation ranks high on your list, start with a basket of companies that screen as more resilient on risk metrics through our 8 resilient stocks with low risk scores.
- For readers who care about quality at a sensible entry point, shortlist potential value opportunities drawn from the 3 high quality undervalued stocks.
- If consistent income is a priority, focus your research on companies with higher yields and robust payout profiles using the 3 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com