
Earnings Strength Might Change The Bull Case For Metropolitan Bank Holding (MCB)
- Metropolitan Bank Holding reported third quarter 2026 net interest income of US$97.61 million and net income of US$32.44 million, along with a higher quarterly dividend of US$0.40 per share and completion of a US$10 million share repurchase program that retired 107,553 shares.
- The mix of stronger earnings, a larger cash payout and a finished buyback indicates active capital return decisions alongside higher reported profitability for Metropolitan Bank Holding.
- We will now look at how Metropolitan Bank Holding's stronger earnings per share profile could influence the existing investment narrative.
Compare Metropolitan Bank Holding's capital return story with a curated 5 dividend fortresses that also pairs earnings strength with meaningful shareholder payouts.
Metropolitan Bank Holding Investment Narrative Recap
For an investor to stay with Metropolitan Bank Holding, the core belief is that its specialty deposit model, technology spend and payments relaunch can support durable profitability, even as banking stays competitive. The third quarter 2026 jump in net interest income and earnings per share points to an operating engine that is currently supporting those ambitions rather than disrupting them.
The bigger near term swing factor is whether elevated noninterest expense on AI, core systems and payments translates into better efficiency once those projects mature. The main near term risk remains credit quality, especially after earlier problem loans and ongoing legal scrutiny of disclosures, and the recent results do not remove that concern.
The most relevant fresh data point is the third quarter 2026 earnings release. Net interest income of US$97.61 million and net income of US$32.44 million, together with US$2.62 basic EPS from continuing operations, provide a snapshot of how the balance sheet is earning today while deposit funded loan growth and branch expansion are still being pursued.
This profitability picture matters for the key catalysts. It supports the higher dividend, helps fund the technology and AI build out without stretching capital, and provides a buffer if credit losses or legal costs rise. When assessing Metropolitan Bank Holding, it is worth weighing that earnings power against the ongoing risks around problem credits, legal outcomes and the payoff from the payments platform relaunch.
Metropolitan Bank Holding's narrative projects US$547.5 million revenue and US$195.4 million earnings by 2029. This implies 20.6% yearly revenue growth and an earnings increase of about US$108.8 million from US$86.6 million today.
Uncover why Metropolitan Bank Holding's fair value indicates an 8% potential upside to its current price that could narrow quickly.
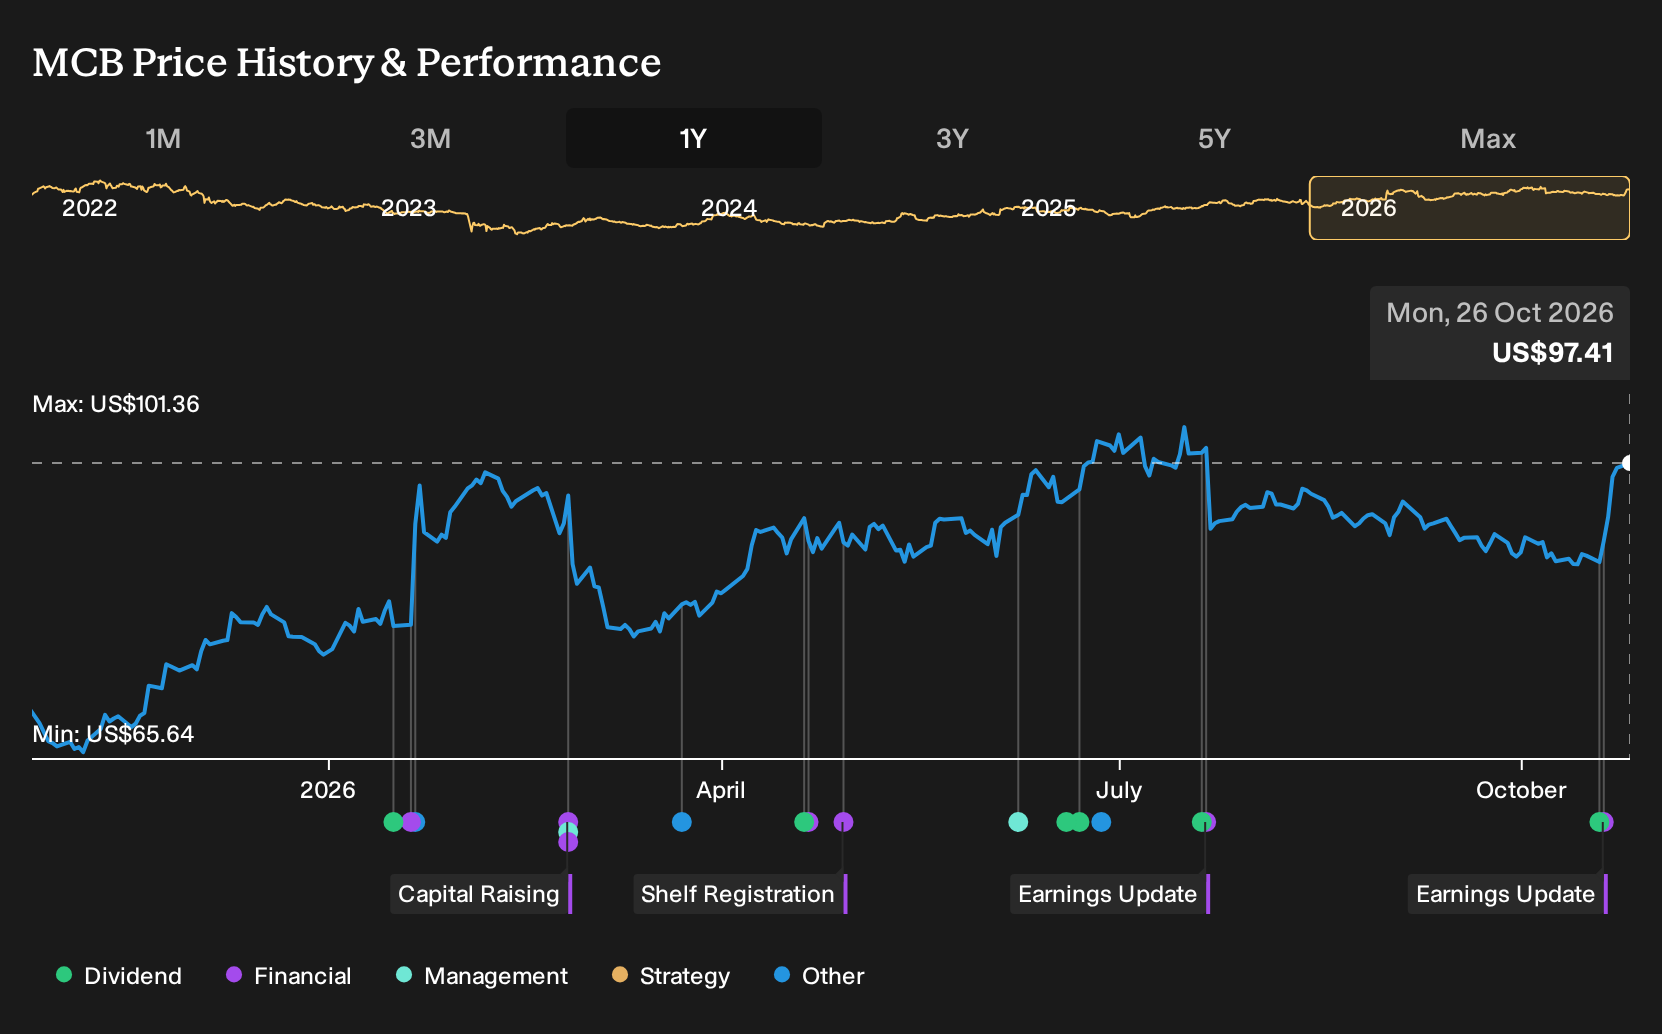
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$105 and US$152 per share, which already shows how far opinions on Metropolitan Bank Holding can stretch. When you factor in heavy AI and systems spend, plus ongoing legal and credit questions, you can see why it may be useful to test your own view against multiple community perspectives.
Explore another Metropolitan Bank Holding fair value estimate, including one that suggests the potential for as much as 56% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Metropolitan Bank Holding research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Metropolitan Bank Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Metropolitan Bank Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Metropolitan Bank Holding?
If the story around Metropolitan Bank Holding has sharpened your thinking, it can help to compare it with other opportunities that share similar strengths but with different risk profiles. The Simply Wall St Screener offers ready made sets of stocks that match common investor priorities, so you can quickly line up alternatives and see where this bank truly fits in your broader watchlist.
- For investors who want resilient balance sheets and fewer financial surprises, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on sturdier businesses.
- If you are hunting for underappreciated opportunities with quality fundamentals, compare Metropolitan Bank Holding with a 21 high quality undiscovered gems that might not yet be widely followed.
- When capital preservation matters just as much as return potential, scan a 30 resilient stocks with low risk scores that screens for stocks with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com