
What Bank Of N.T. Butterfield & Son Stock Earnings Report Means For Shareholders
- Bank of N.T. Butterfield & Son plans to release its Q3 2026 results after the market close on October 27, with consensus pointing to 4.5% year on year revenue growth, compared with a 6.8% increase in the same quarter a year earlier.
- The expected moderation in revenue growth, combined with largely unchanged analyst forecasts, highlights the importance investors appear to be placing on Butterfield's ability to manage operating costs and sustain fee driven income as it scales its offshore banking and wealth services.
- We will examine how Bank of N.T. Butterfield & Son's investment narrative could be influenced by the expected slowdown in quarterly revenue growth.
Scan offshore banking peers positioned for similar earnings catalysts by reviewing our curated list of list of solid balance sheet and fundamentals (24 results).
Bank of N.T. Butterfield & Son Investment Narrative Recap
For someone holding Bank of N.T. Butterfield & Son, the core belief is that an offshore focused bank can scale wealth, trust and digital services while keeping credit quality and costs under control. The Q3 report on October 27 mainly tests that cost discipline. A 4.5% revenue increase versus a stronger prior year quarter points more to moderation than a break in the story.
The near term swing factor is whether noninterest income and efficiency hold up as Butterfield prepares for the CIBC Caribbean acquisition and carries guided quarterly expenses of US$93m to US$95m. The biggest operational risk is that higher funding costs and integration spending compress margins before expected benefits come through.
The upcoming Q3 release is most relevant for tracking progress toward that CIBC Caribbean deal. Management plans to fund the US$1.8b purchase with about US$700m of subordinated debt and a pause in share buybacks, so investors are watching how current earnings absorb higher prospective interest costs.
Any fresh detail around credit quality in the Caribbean, capital ratios and regulatory milestones sits alongside the existing ratings watch for downgrade on senior unsecured debt and deposits. For readers, the key question is whether Butterfield shows enough fee income momentum and stable asset quality to offset those funding and integration risks as the acquisition moves closer.
Bank of N.T. Butterfield & Son's current analyst narrative points to revenues of US$1.8b and earnings of US$325.0m by 2029, based on an assumed 42.3% yearly revenue growth rate and a move from US$234.4m of earnings today to that 2029 consensus. This implies an earnings increase of about US$90.6m.
Uncover why Bank of N.T. Butterfield & Son's fair value indicates a 9% potential upside to its current price that could narrow quickly.
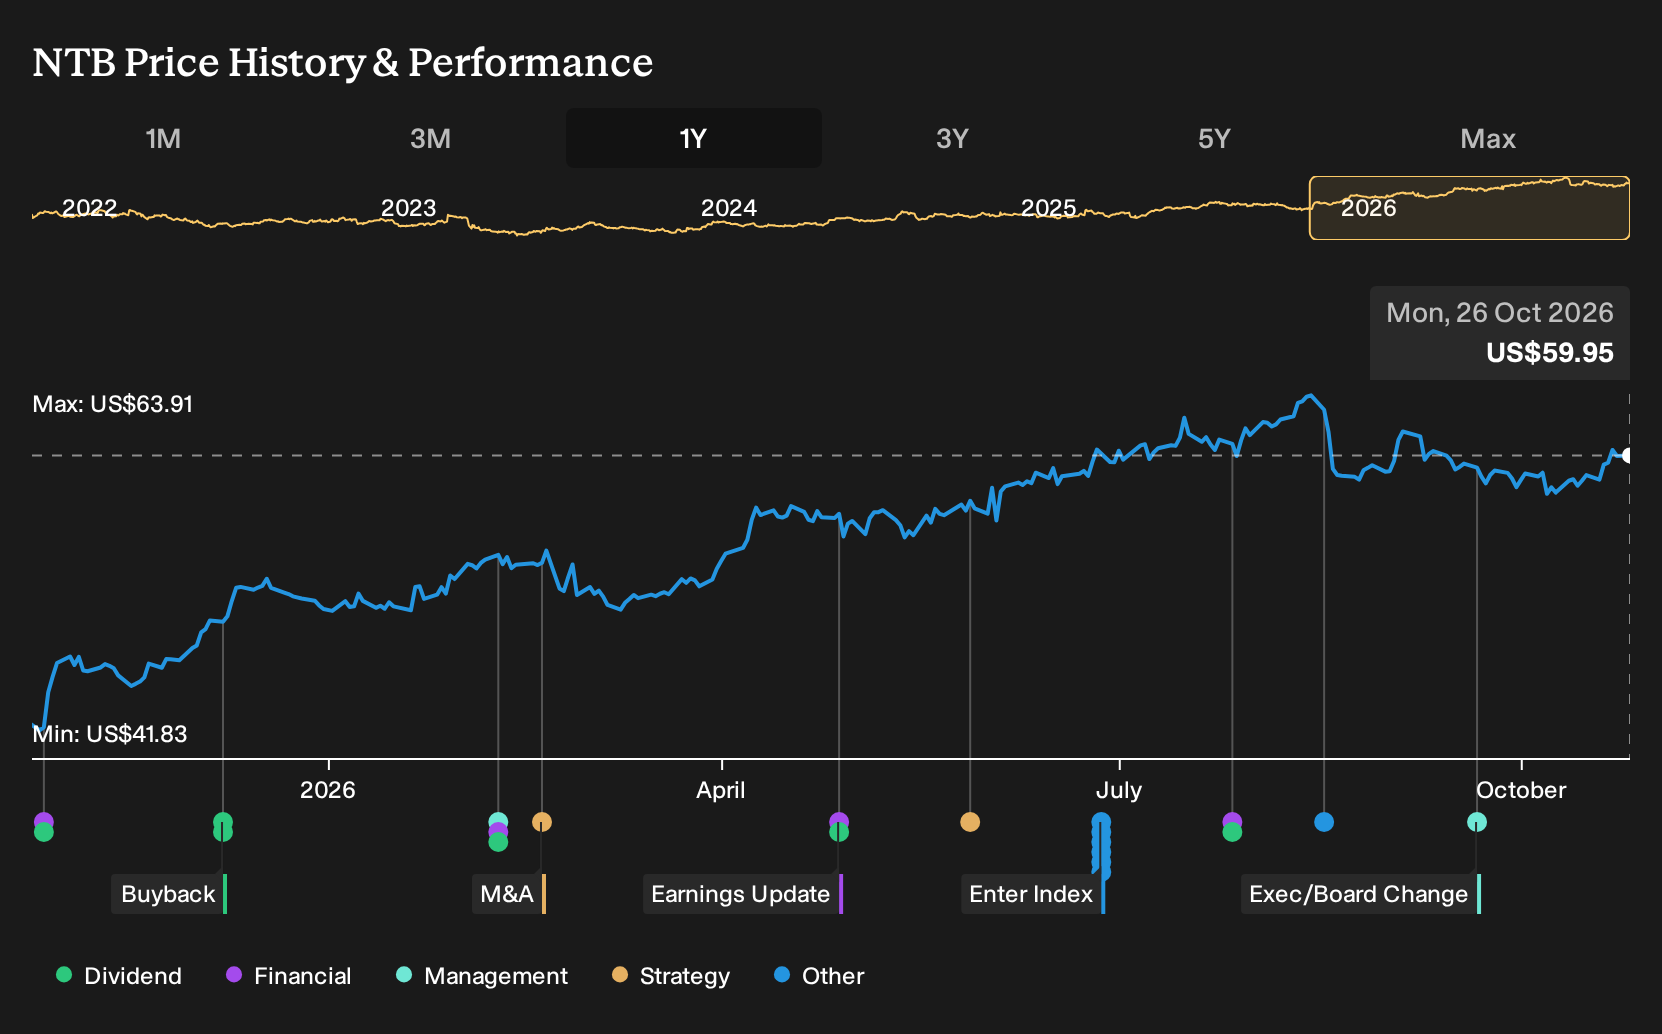
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$65 to US$196 per share, so retail opinions on Bank of N.T. Butterfield & Son already cover extreme outcomes. When these are considered alongside the coming Q3 update and the planned US$700m subordinated debt issue, there is real room for sharply different performance expectations.
Explore 2 other Bank of N.T. Butterfield & Son fair value estimates, including one that suggests it could be worth just $65.33.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Bank of N.T. Butterfield & Son research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bank of N.T. Butterfield & Son. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of N.T. Butterfield & Son's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank of N.T. Butterfield & Son?
If the story around Bank of N.T. Butterfield & Son has sharpened your thinking, keep that momentum going by scanning other companies that fit the kind of balance sheet strength, income profile, or risk level you want in a portfolio.
- For investors who want potentially resilient income and capital strength, review a curated 5 dividend fortresses that match higher yield targets with balance sheet checks.
- If your priority is limiting downside risk, start with companies screened as 30 resilient stocks with low risk scores and see which profiles best complement your existing holdings.
- For those searching for quality away from the usual watchlists, widen your research with a focused set of 21 high quality undiscovered gems that pair fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com