
Evergy (EVRG) Could Be 5% Undervalued Following Truist Coverage
Evergy stock: why Truist's fresh coverage matters now
Evergy (EVRG) just landed new analyst coverage from Truist, which highlighted earnings potential and a growth opportunity within the utilities sector. That fresh attention is what put the stock on many investors’ radar.
The fresh coverage lands after a solid run. Evergy’s share price has a 1 month return of 8.4% and a year to date share price return of 15.8%. The 3 year total shareholder return of 97.2% hints that momentum has been strong over a longer stretch as investors reassess both growth potential and risk.
Scan other utility plays showing similar analyst-driven momentum by running the 42 power grid technology and infrastructure stocks together with Evergy in your watchlist.
That recent 8.4% one month move in Evergy could be read as enthusiasm chasing Truist’s call or as a cleaner reflection of fundamentals. The valuation work now needs to show which story fits.
Most Popular Narrative: 5% Undervalued
Evergy closed at $84.61, while the most followed narrative pegs fair value at $89. This points to a modest valuation gap that Truist’s timing only sharpens. The story now hinges on whether the heavy spending and large-load contracts justify that difference.
Accelerated investment in grid modernization and new generation capacity is reflected in Evergy's current plan to deploy about US$21.6b from 2026 to 2030 plus roughly US$1b of additional generation capital. This is associated with a projected rate base CAGR of about 12% and is expected to support long-term earnings growth.
See why 15 investors see Evergy as 5% undervalued.
Result: Fair Value of $89 (UNDERVALUED)
Still, the whole Evergy narrative can wobble if large data center loads ramp more slowly than planned or if regulators push back harder on future rate increases.
Find out about the key risks to this Evergy narrative.
Another View: Evergy through the earnings multiple lens
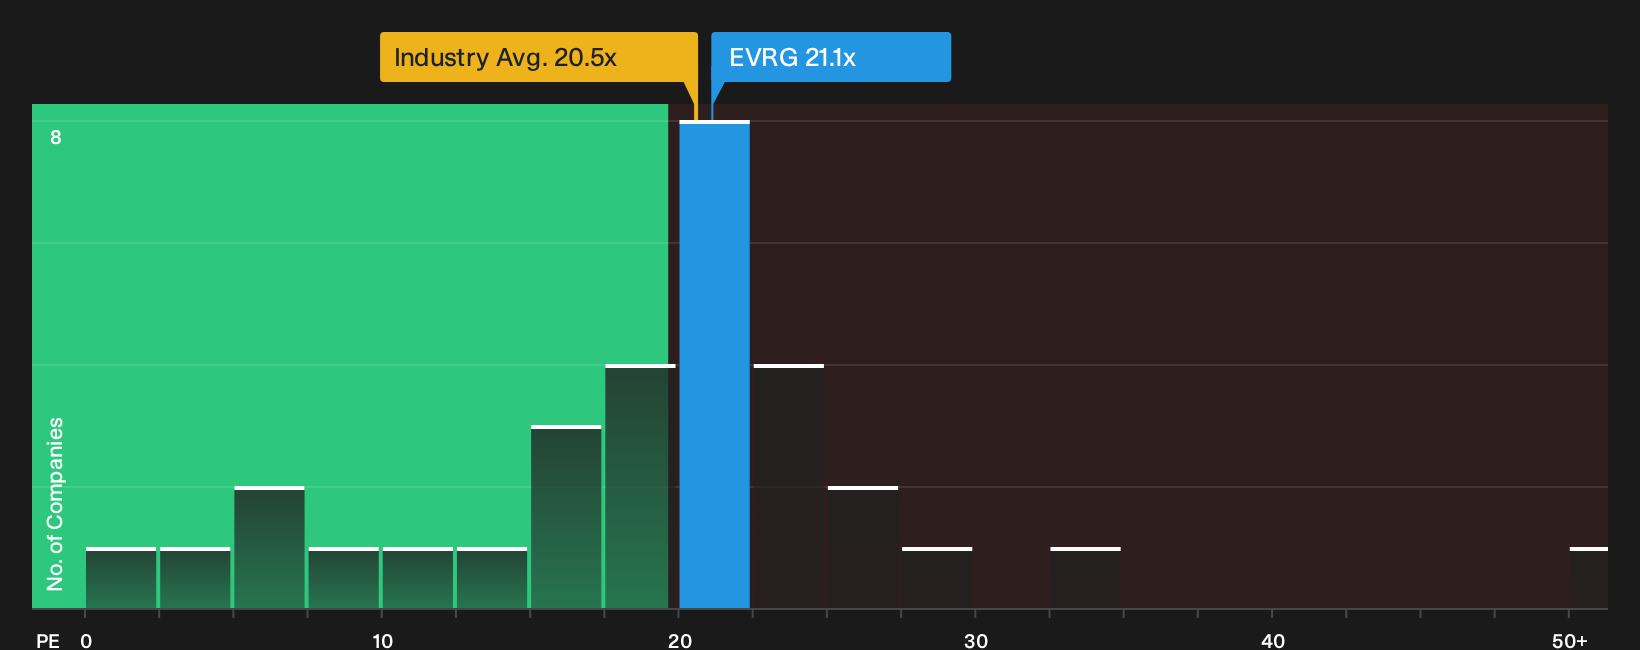
Evergy might look modestly undervalued on that $89 fair value narrative, yet the simple P/E check tells a tougher story. The stock trades on 21.1x earnings versus a fair ratio of 20.4x, the US Electric Utilities group on 20.6x and peers on 18.5x, which points to valuation risk rather than clear upside. The question is whether Evergy’s growth plans fully justify paying a richer multiple than both its industry and closest comparisons.
To see how those earnings-based signals stack up against a cash flow view, it is worth lining this up against the SWS DCF model, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Evergy’s valuation and risk profile make this a judgment call. Pull up the numbers, stress test your assumptions, then weigh the 2 key rewards and 2 important warning signs.
Looking for more Evergy-sized investment ideas?
If Evergy sharpened your focus, do not stop with a single ticker. Broaden your watchlist now with targeted stock ideas built from clear, transparent filters.
- Target potential mispricing by scanning a focused set of quality companies through the 29 high quality undervalued stocks.
- Prioritize income and resilience by zeroing in on companies that qualify as 5 dividend fortresses.
- Dial down portfolio risk by hunting for companies on the 30 resilient stocks with low risk scores before capital chases them higher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com