
Earnings Beat Might Change The Case For Investing In Iridium Stock (IRDM)
- Iridium Communications reported third quarter 2026 revenue of US$245.73 million and net income of US$106.9 million, with basic EPS from continuing operations of US$1, alongside higher year to date revenue and earnings compared with the same period in 2025.
- Altair Semiconductor disclosed the integration of Iridium NTN Direct into its ALT1350 and ALT1550 IoT chipsets, which gives device makers and mobile operators a way to add satellite connectivity without separate modems across asset tracking, logistics, utilities, agriculture, vehicle telematics and emerging AI wearables.
- Attention now turns to how Iridium Communications' stronger earnings and Altair chipset integration could reshape the longer term investment narrative.
Iridium Communications Investment Narrative Recap
To own Iridium Communications, you need to believe its satellite network can keep turning specialist services in IoT, aviation, government and assured PNT into steady cash generation, even with modest service revenue guidance. The latest quarterly results, with US$245.73 million of revenue and US$106.9 million of net income, show the model currently generates high earnings.
The near term swing factor is whether new offerings like NTN Direct and PNT move from launch phase to broader usage without eroding margins or overextending the balance sheet in the Rocket Lab tie up. The key risk remains that service mix and IoT usage soften, which could leave EBITDA and free cash flow closer to today’s levels than some investors might prefer.
The Altair Semiconductor update looks central to this story. Embedding Iridium NTN Direct into the ALT1350 and ALT1550 chipsets effectively puts Iridium Communications into more IoT and wearable designs at the silicon level. That gives device makers one board and one power system for both terrestrial and satellite links, which can remove friction from adoption.
What matters for investors is not the announcement itself but how much real traffic it eventually drives. If asset tracking, utilities, agriculture, telematics and AI wearables that use these Altair parts generate sustained satellite usage, that would speak directly to the IoT and direct to device catalyst that many are watching. If usage remains narrow, the earlier concern about muted IoT service revenue and slower EBITDA expansion would still hang over the story.
Iridium Communications Analyst Expectations In Focus
Analyst models around Iridium Communications paint a very different picture from the current earnings power implied by the latest quarterly numbers. Consensus assumes revenue grows at 7.9% per year for the next three years while profit margins compress from 18.1% today to 7.2% by 2029. That margin reset feeds into a forecast that earnings move from US$163.0 million today to US$81.9 million by 2029, even as the analyst framework still leans on recurring service activity and new products like NTN Direct and assured PNT.
This profile is not just about profit projections. It also bakes in share count creeping higher by 1.35% per year, a discount rate of 7.24% and an assumption that the stock trades on a P/E of 76.6x those 2029 earnings compared with 28.5x today and 23.2x for the wider US telecom sector. In other words, the scenario involves lower profit in absolute terms, lower margins and more shares, yet a much richer earnings multiple. Readers need to decide whether that mix of softer fundamentals and higher valuation multiple lines up with their own expectations for how Iridium Communications might monetise its spectrum assets, Rocket Lab combination and IoT footprint over the rest of the decade.
Iridium Communications' current analyst narrative points to revenues of US$1.1b and earnings of US$81.9 million by 2029. This framework assumes yearly revenue growth of 7.9% and an earnings decline of US$81.1 million from current earnings of US$163.0 million.
Uncover why Iridium Communications' fair value indicates a 3% potential upside to its current price that may not last much longer.
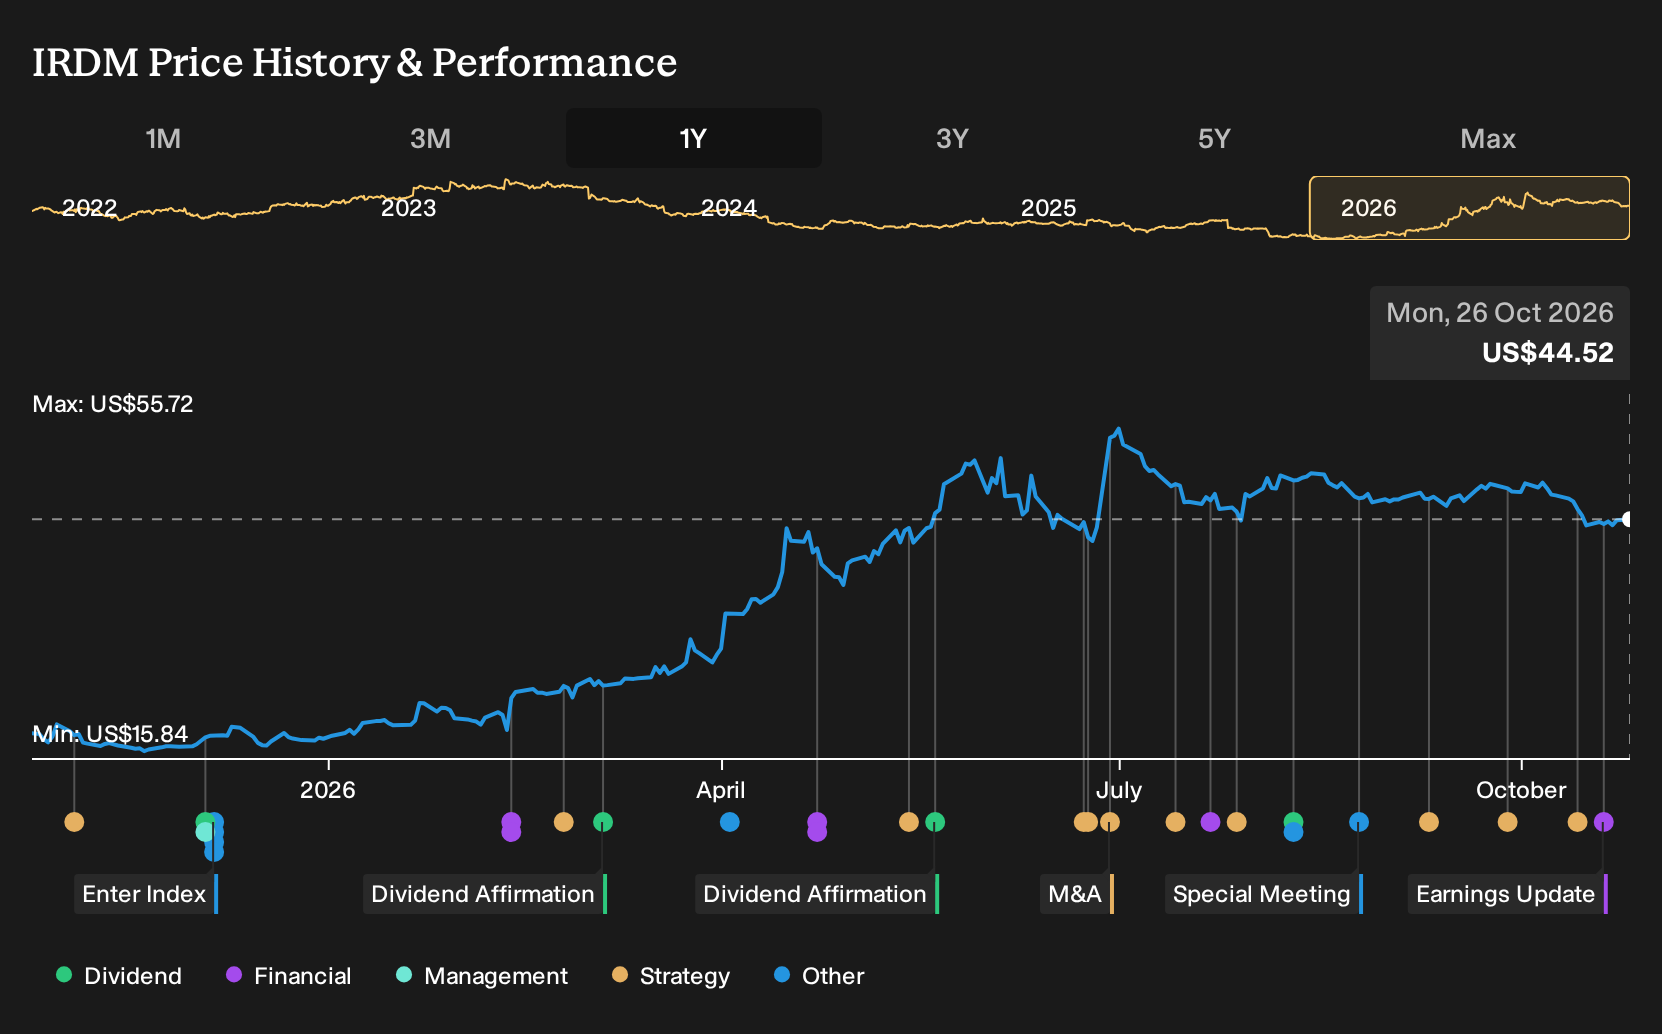
Exploring Other Perspectives
One alternate angle treats Iridium Communications' assured PNT ramp as the real swing factor. Bullish analysts were pencilling in US$1.2b of revenue and US$144.3 million of earnings by 2029 before this quarter and the Altair chipset deal. That is a far more optimistic path. Use this earnings beat to test which story you find more convincing.
Explore 5 other Iridium Communications fair value estimates, including one that suggests potential upside of up to 45% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Iridium Communications research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Iridium Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iridium Communications' overall financial health at a glance.
Looking for more investment ideas beyond Iridium Communications?
If Iridium Communications has sharpened your interest in connectivity and cash generation, consider using this momentum to widen your watchlist with companies that match the kind of balance sheet strength, income profile, or upside potential you want to focus on next.
- If capital preservation sits high on your checklist, you could start with a basket of companies that score well on resilience by checking out 30 resilient stocks with low risk scores positioned to handle a range of scenarios.
- For readers who want income flowing into their account, you might scan through 5 dividend fortresses that combine higher yields with an emphasis on stability.
- If you are hunting for under the radar stories, you could filter for 21 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com