
Will Stronger Q3 Earnings Change Packaging Corporation Of America's (PKG) Narrative
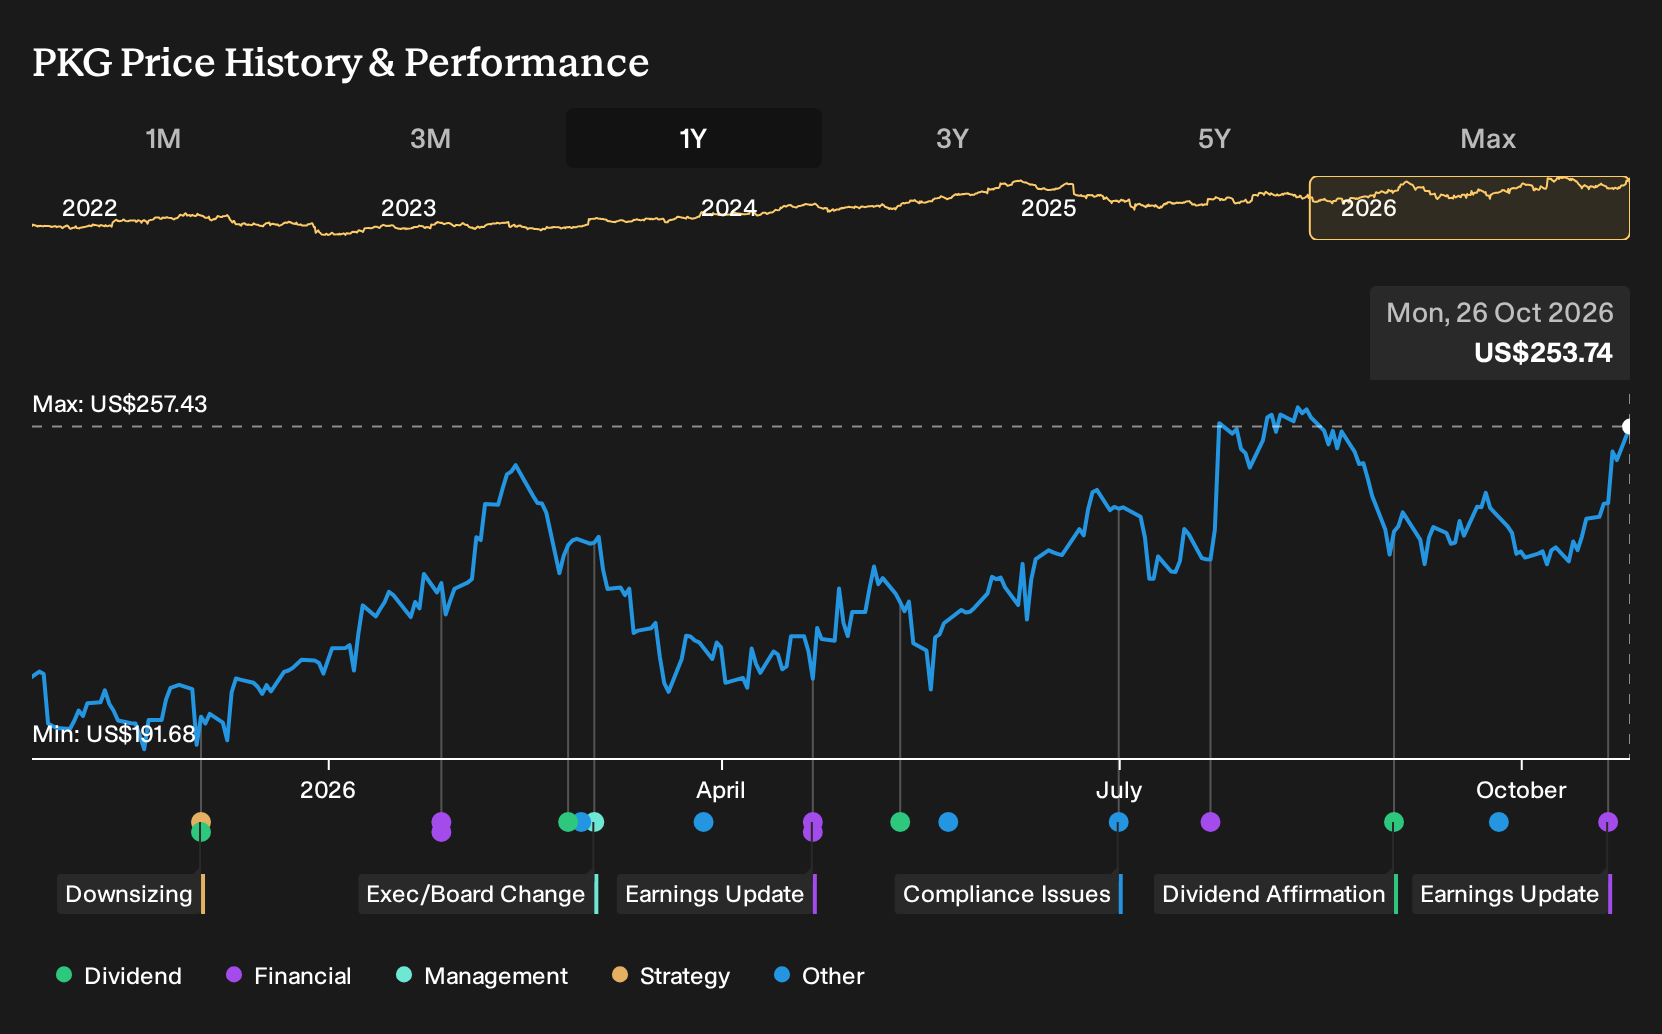
- Packaging Corporation of America reported past third quarter 2026 sales of US$2,601.7 million and net income of US$262.3 million, with basic earnings per share from continuing operations of US$2.94.
- The nine month period showed sales of US$7,459.3 million and net income of US$625.3 million, and stronger Q3 profitability contrasts with softer year to date earnings power.
- We will now look at how Packaging Corporation of America’s stronger third quarter profit picture affects the existing investment narrative.
Packaging Corporation of America Investment Narrative Recap
To own Packaging Corporation of America, you need to believe its tight containerboard system, heavy mill investment and Greif integration can support solid cash generation even when costs bite. The latest quarter helps that case in the short run. Higher Q3 sales and earnings per share suggest pricing and volumes are at least holding up against elevated input costs.
The less comfortable part is the nine month picture. Sales for the period grew while net income and earnings per share from continuing operations softened versus last year. That keeps the key near term risk in focus. If recycled fiber, freight and energy stay expensive and pricing power fades, margin pressure could persist.
The fresh Q3 and nine month earnings release is the announcement that matters most right now. It confirms US$2,601.7 million in quarterly sales and US$262.3 million of profit, with basic earnings per share from continuing operations of US$2.94. For the first nine months, revenue reached US$7,459.3 million and net income was US$625.3 million.
Those figures sit against a story built on tight industry supply, large capital expenditure and containerboard price increases intended to offset cost inflation. You can use this report as a check on that thesis. Stronger Q3 profitability relative to the softer year to date outcome underlines how sensitive Packaging Corporation of America still is to demand swings and how fully pricing flows through.
Packaging Corporation of America's narrative projects US$11.4b revenue and US$1.7b earnings by 2029. This assumes 5.2% yearly revenue growth and an earnings increase of about US$977.3 million from US$722.7 million today.
Uncover why Packaging Corporation of America's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish angle on Packaging Corporation of America leans heavily on earnings potential rather than today’s compressed margins. The most optimistic analysts were pencilling in about US$11.9b of revenue and US$1.8b of earnings by 2029 before this Q3 update. That is far above the more cautious consensus path. Use this result as a prompt to compare those optimistic expectations with your own view on pricing, costs and mill execution, since fresh numbers often shift narratives in very different directions.
Explore 2 other Packaging Corporation of America fair value estimates, including one that suggests as much as 73% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Packaging Corporation of America research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Packaging Corporation of America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Packaging Corporation of America's overall financial health at a glance.
Looking For More Ideas Beyond Packaging Corporation of America?
If the latest Packaging Corporation of America update has sharpened your view on quality, pricing power and balance sheet strength, it can be useful to line that thinking up against other listed businesses. The Simply Wall St Screener helps you quickly filter for stocks that match the kind of financial profile you want to research next.
- If you want potential value coupled with quality fundamentals, start by scanning a 29 high quality undervalued stocks that already clear basic balance sheet and cash flow hurdles.
- For income focused research, compare Packaging Corporation of America with a 5 dividend fortresses that combine yield with a focus on durability.
- When capital preservation is front of mind, narrow your watchlist to a 30 resilient stocks with low risk scores that score well on financial strength and volatility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com