
Did Earnings Strength Just Shift Fastenal's (FAST) Investment Narrative?
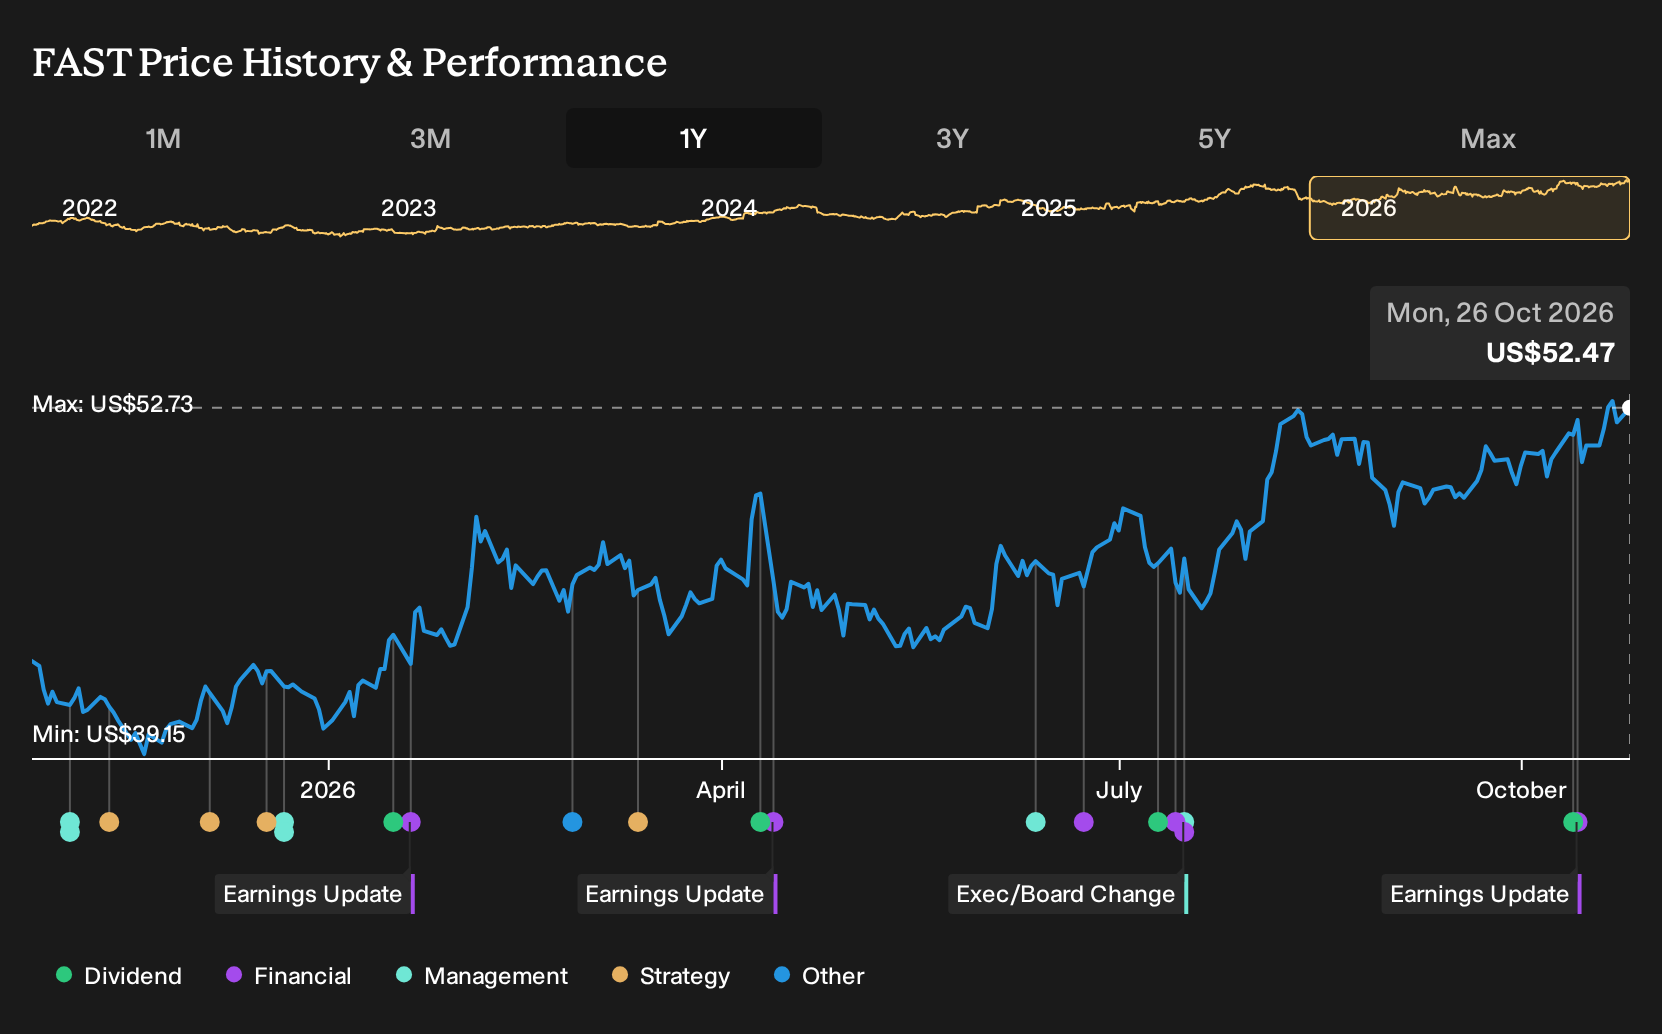
- Fastenal reported third quarter 2026 sales of US$2,463.3 million and net income of US$401.6 million, with basic and diluted EPS from continuing operations at US$0.35. For the first nine months of 2026, sales reached US$7,051.9 million and net income was US$1,124.2 million. The board declared a fourth quarter cash dividend of US$0.26 per share, payable on November 25, 2026.
- The combination of higher sales and earnings per share across both the quarter and year to date period indicates that Fastenal's operating model, including its focus on large accounts and managed inventory, is currently supporting stronger profitability. At the same time, the company continues to return cash to shareholders through regular dividends.
- This article will examine how Fastenal's investment narrative aligns with its third quarter earnings performance and higher year to date profitability.
Fastenal Investment Narrative Recap
To own Fastenal, you need to believe its model of large key accounts, Fastenal Managed Inventory and a rising digital mix can keep supporting high returns even as end markets move around. The latest quarter shows that structure still producing higher sales and earnings. In the near term, the key swing factor remains industrial demand, especially in heavy manufacturing and construction.
The main operational risk is that tariffs and other input costs keep outpacing pricing, which has already created a gross margin headwind. If industrial activity cools at the same time, that could pressure daily sales and make it harder for Fastenal to keep funding capital expenditure and dividends from internal cash generation.
The most relevant update for this catalyst and risk mix is the third quarter 2026 earnings release. Fastenal reported US$2,463.3 million of sales and US$401.6 million of net income for the quarter, plus US$7,051.9 million of sales and US$1,124.2 million of net income for the first nine months of 2026, alongside basic EPS from continuing operations of US$0.35 in the quarter.
Those results sit on top of an investment plan of about US$320 million of 2026 net capital expenditure into hubs, automation, FMI hardware and IT. For investors, the link is simple: ongoing earnings support this spend and the dividend, while any squeeze from tariffs, slower industrial activity or weaker free cash flow coverage of payouts remains the key risk to watch.
Fastenal's current analyst narrative points to revenues of US$11.4b and earnings of US$1.8b by 2029, based on expectations for 9.2% yearly top line growth and an earnings increase of about US$0.4b from US$1.4b today.
Uncover why Fastenal's fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic Fastenal watchers focus on SG&A leverage as the key catalyst. They were pencilling in around US$11.9b of revenue and US$2.0b of earnings by 2029, well above the baseline. The new earnings beat and steady dividend could push those upbeat forecasts higher, lower or simply make them more contested, so treat this as your cue to compare several viewpoints, not just a single perspective.
Explore 4 other Fastenal fair value estimates, including one that suggests up to 12% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Fastenal research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fastenal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fastenal's overall financial health at a glance.
Looking for more investment ideas beyond Fastenal?
If Fastenal's earnings profile and dividend stream have your attention, it can be useful to line it up against other businesses with different strengths and risk patterns using the Simply Wall St Screener.
- For investors who want income without stretching on quality, take a look at a curated group of high yielders in our 5 dividend fortresses that aim to pair payouts with resilient fundamentals.
- If capital protection and stability sit higher on your priority list, consider reviewing companies in the 30 resilient stocks with low risk scores that screen well on balance sheet strength and business risk.
- When you want to broaden your watchlist with less followed opportunities, scan the 21 high quality undiscovered gems to spot financially sound businesses that are not yet widely discussed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com