
Ray Dalio Gave the U.S. 3 Years Before a Debt ‘Heart Attack.’ 19 Months Later, Here’s the Scorecard.
Back in March 2025, Ray Dalio gave the U.S. a deadline. Speaking on Bloomberg’s “Odd Lots” podcast, the Bridgewater founder said America’s debt was heading toward a “heart attack.” He couldn’t say exactly when, but his best guess was “three years, give or take a year.” So his window runs from roughly 2027 to 2029. He warned that a crisis could bring a spike in interest rates and weaker currencies, and he pointed to gold as a way to protect yourself.
Fast forward 19 months, and I’d say the warning signs have become even harder to ignore. U.S. debt crossed $40 trillion in August 2026. Interest costs now take up about 3.3% of GDP, and only Social Security and Medicare cost the government more. In July, the 30-year Treasury yield hit its highest level since 2007. Shortly after this, the Treasury said it would buy back far more of its own long-term bonds. Officially, it's to keep that market running smoothly. But Dalio had warned that demand for U.S. debt would struggle to keep up with supply, and I worry these buybacks suggest that the problem is already here.
Gold Is Winning the Bet
So far, gold has paid off for anyone who listened. It was trading below $3,000 an ounce when Dalio spoke, and it’s now around $4,000, even after pulling back from its highs. Newmont (NEM), the world’s largest gold miner, shows how big a deal that is. In the third quarter of 2026, it sold gold at an average of $4,317 an ounce, while its all-in sustaining cost was $1,454. That's a gap of nearly $2,900 per ounce, almost double what it was in early 2025. While Washington keeps borrowing more, Newmont sits on $3.2 billion in net cash and has cut its share count by about 10% since February 2024.
About Newmont Stock
Founded in 1916, Newmont Corporation is a mining company headquartered in Denver, Colorado. Valued at $121.5 billion by market cap, the primarily gold-focused company also produces and markets, copper, silver, zinc, and lead.
NEM stock has climbed 13% on a year-to-date (YTD) basis, almost matching the Nasdaq Composite's ($NASX) 13.7% return. In the longer term, shares of the gold and copper miner have soared 43% over the past 52 weeks, compared to NASX’s 11.8% return over the same time frame. In comparison, rival AngloGold Ashanti (AU) has lagged NEM stock on a YTD basis, with AU stock up 1%. However, AU stock has surged 33% over the past 52 weeks.
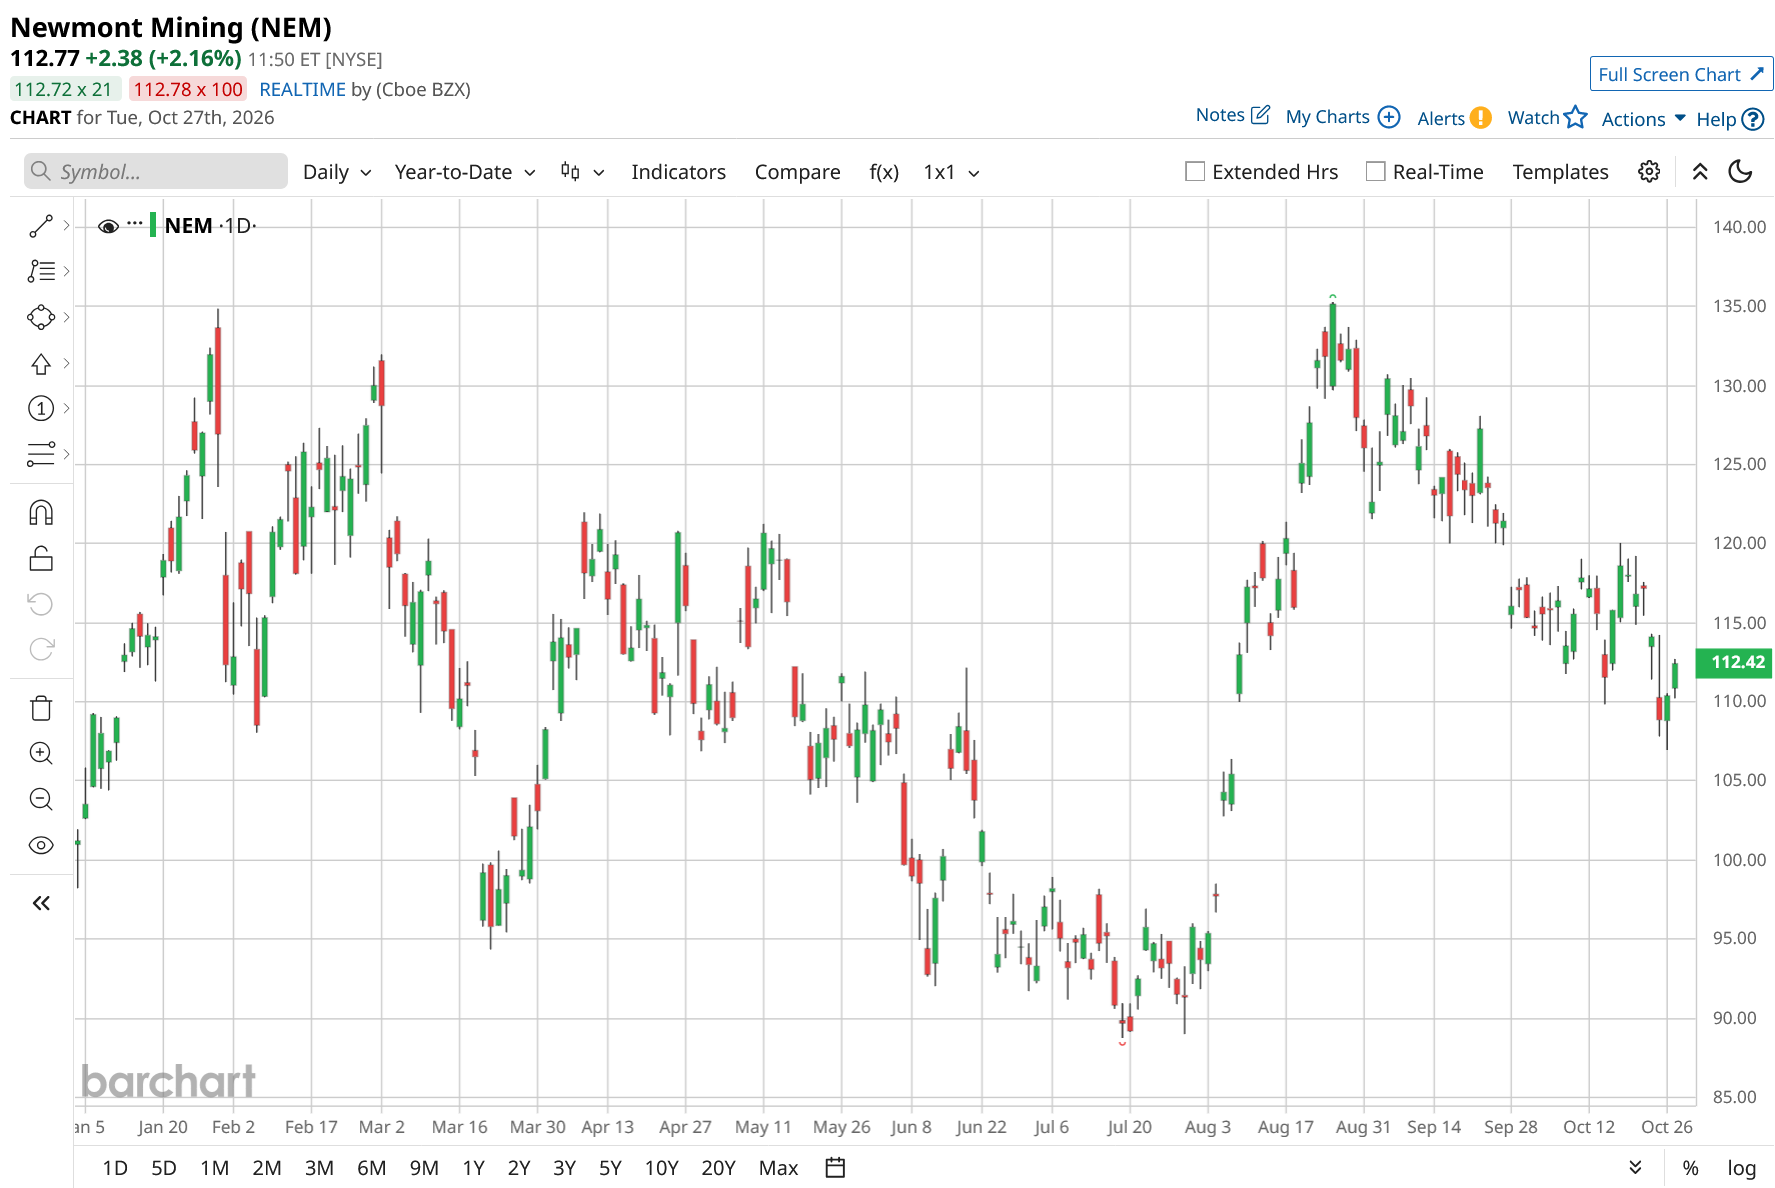
Newmont looks cheap on earnings. The forward price-to-earnings (P/E) of 11.87x sits about 32% below its 5-year average of 17.35x. I think that discount suggests the market doesn't fully trust gold to stay this high. The forward price-to-sales (P/S) ratio of 4.32x is about 23% above its 5-year average of 3.51x. That makes sense, since higher gold prices boost profits much more than sales. Analysts expect EPS to grow 32% in 2026, then keep growing at double-digit rates through 2029. The balance sheet is strong too, with $8.83 billion in cash against $5.58 billion in debt. For Newmont, the profits rise and fall with gold. So if Dalio is right, that works in its favor.
Higher Gold Prices Are Supporting Newmont's Earnings
Newmont reported its third-quarter fiscal 2026 earnings on Oct. 23. The company beat Wall Street expectations in the third quarter, reporting adjusted earnings of $2.20 a share on revenue of $6.36 billion. The company delivered about 1.3 million ounces of gold, 23,000 tons of copper, and 11 million ounces of silver in the quarter. Adjusted EBITDA reached $4 billion, and adjusted net income was also a third-quarter record.
Looking forward, management expects fourth-quarter gold production to rise by about 1.4 million ounces, which would make it the stronger quarter of 2026. Looking ahead to 2027, Newmont expects total portfolio production to rise by a low-to-mid single-digit percentage. The company said growth should come from higher-grade ore at Lihir and Boddington, additional ounces from Tanami’s second expansion and other assets.
What Do Analysts Think of NEM Stock?
Crucially, Wall Street analysts remain bullish as ever on NEM stock for the remainder of 2026. Barclays analyst Richard Garchitorena reiterated a “Buy” rating and set a price target of $123. In addition, Scotiabank analyst Tanya Jakusconek also maintained a “Buy” rating with a price target of $149.
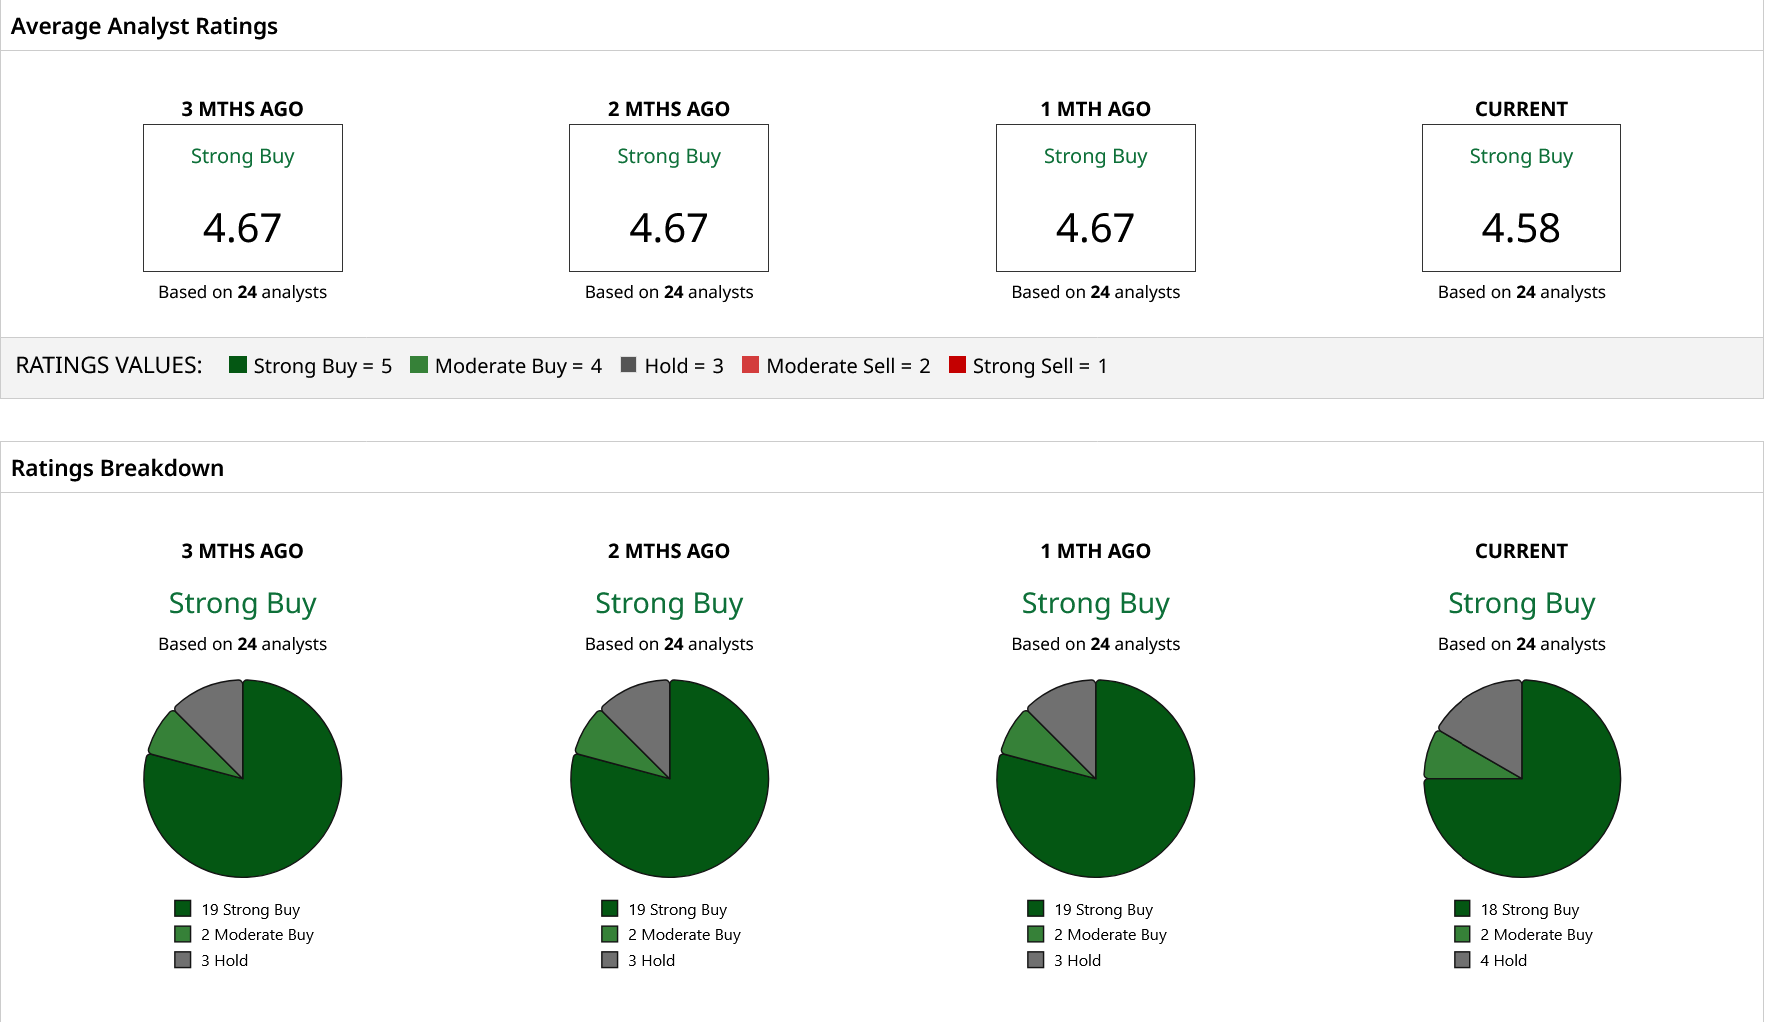
Overall, the consensus rating on NEM sits at “Strong Buy,” with the mean price target of $136.82 indicating a potential upside of about 22% from here. The high price target of $165 implies 47% upside from the current share price.
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.