
Did Earnings Estimate Hike Just Shift CNX Resources' (CNX) Investment Narrative?
- CNX Resources is set to report quarterly results for the September 2026 period, with analysts currently estimating earnings per share of $0.65 and recent revisions lifting that consensus figure in the past month.
- The upward shift in earnings expectations points to changing views on CNX Resources' near term operating performance and cost discipline rather than just sentiment, even though an Earnings ESP of 2.91% and a Zacks Rank of #3 leave the outcome versus consensus uncertain.
- We will now explore how CNX Resources' investment narrative is affected by these higher earnings estimates heading into the upcoming quarterly report.
CNX Resources Investment Narrative Recap
To own CNX Resources, you need to believe its Appalachian gas portfolio, low carbon projects and long dated hedges can keep cash generation resilient even if headline earnings swing. The near term focus is on how efficiently CNX converts its acreage, infrastructure and hedges into steady operating cash, rather than on a single quarter.
The September quarter EPS expectation of US$0.65 sets a reference point, but on its own does not materially alter the main near term catalyst, which is execution on Marcellus and Utica development alongside cost control. The biggest risk still sits with policy or market setbacks that affect tax credit monetization or in basin gas demand.
The most relevant update tied to this earnings set up is the recent 8.4% upward revision in the consensus EPS estimate to US$0.65 for the September 2026 quarter. That change highlights how investors are reassessing near term profitability for CNX Resources as the firm leans on hedges, tax credit plans and operating efficiencies.
For you, the link back to catalysts is clear. If CNX keeps improving Utica drilling efficiency, holds per foot costs near recent commentary and progresses toward the projected US$90 million a year from 45Z and environmental attributes, then quarterly results become checkpoints on execution. Any disappointment on tax guidance, demand projects or unit margins would cut against that thesis.
CNX Resources Earnings Framework And Analyst Assumptions
Analysts framing CNX Resources today are working off a relatively flat revenue path over the next three years, paired with a margin profile that is expected to compress. Profitability is modeled to move from a 44.4% margin now to about 19.8% by 2029, which shapes how much value investors might reasonably ascribe to the tax credit and efficiency story that has been front and center in recent commentary.
On earnings, the consensus points to US$949.4 million in profit today stepping down to US$435.9 million by around 2029. That is a decline of roughly US$513.5 million in annual earnings, even though analysts highlight levers like hedging, Utah and Marcellus efficiency and 45Z credits as important supports for cash generation. For readers focused on per share outcomes, that 2029 view also lines up with an earnings per share figure of about US$4.13, assuming the projected share count growth over the next few years.
Valuation math inside these models asks CNX Resources to trade on a P/E of 19.2x those 2029 earnings, compared with about 4.9x on current earnings and a reference multiple of 12.3x for the broader US oil and gas group. In practical terms, the analyst work is saying that even with lower earnings and thinner margins, the stock could support a higher multiple if investors gain confidence in the durability of hedged cash flows and the credibility of low carbon revenue streams.
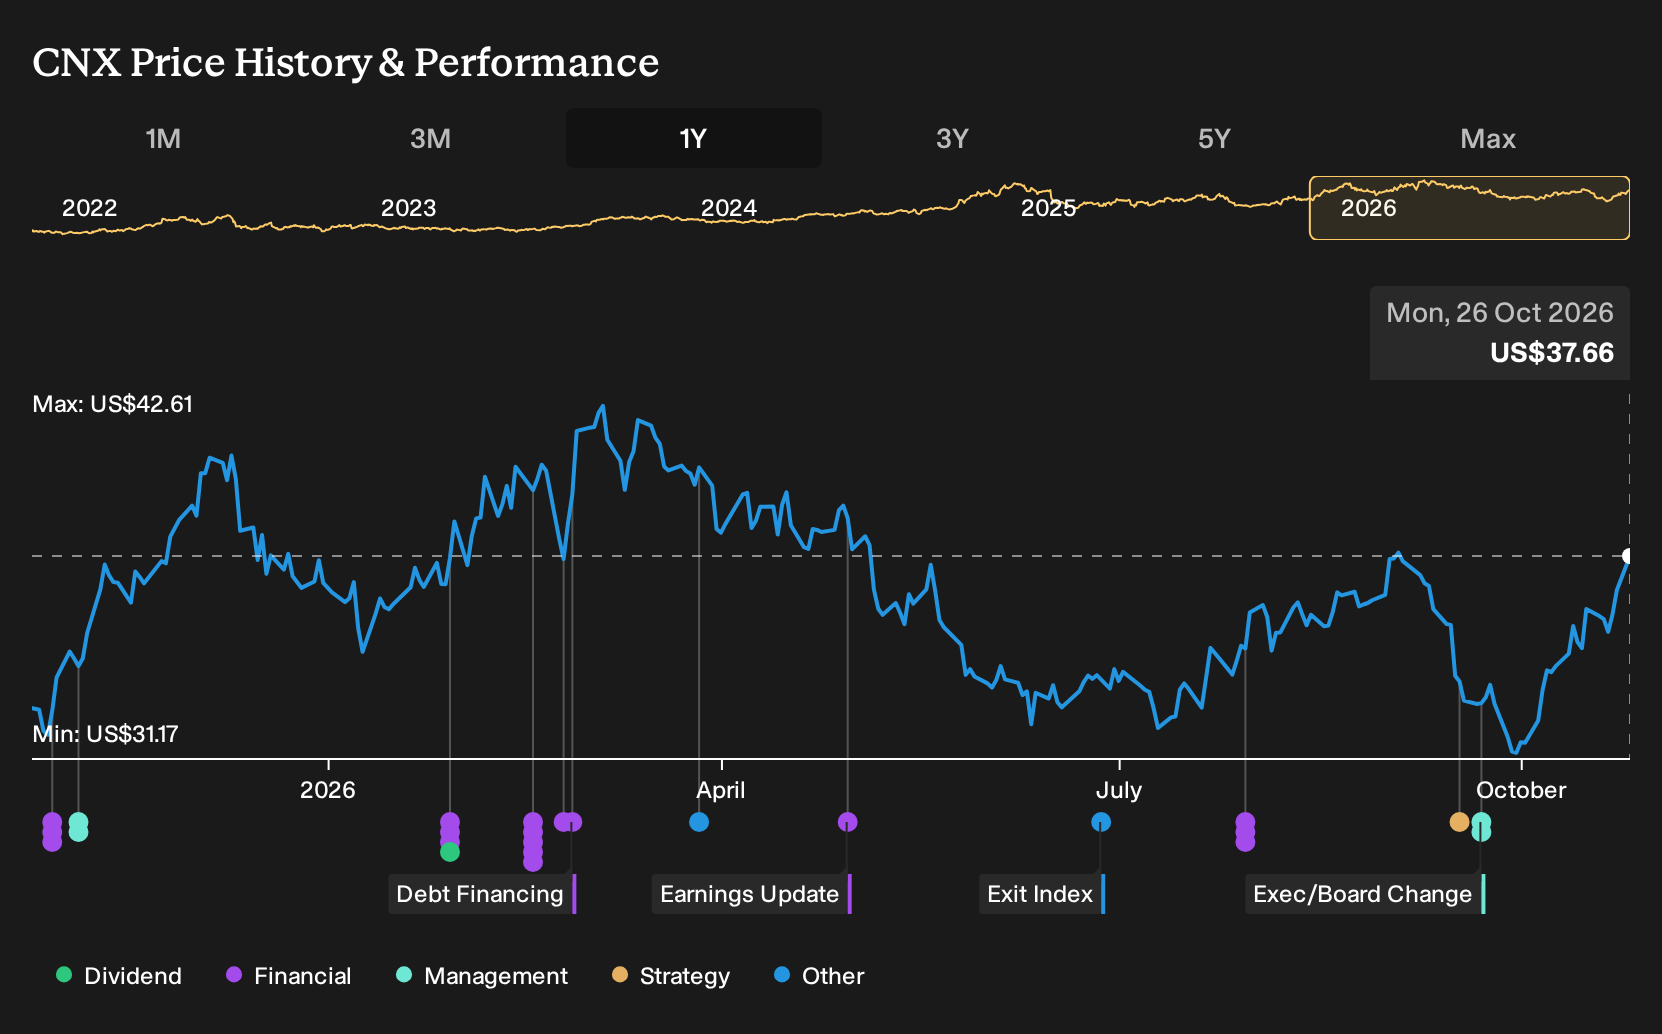
The same analyst set links that earnings trajectory and multiple assumption to a consensus price target of US$37.55, against a current share price around US$31.50 as of late October 2026. Individual targets stretch from US$32.00 at the low end to US$48.00 at the high end, which signals real disagreement on how far CNX Resources can extend its current playbook of share repurchases, balance sheet moves and gas marketing into the later 2020s without eroding equity value.
For readers comparing outcomes, the models that back the consensus target assume that by 2029 the business generates roughly US$2.2b in annual revenue alongside those US$435.9 million in earnings. That pairing implies a much lower profit margin than today, so any surprise in future quarters on realized pricing, tax credit monetization or cost control will tend to flow directly into how credible that 2029 bridge looks for both earnings power and valuation.
CNX Resources' narrative projects US$2.2b revenue and US$435.9 million earnings by 2029. This sits alongside analyst expectations that revenue stays broadly flat over the next few years and reflects an earnings decrease of about US$513.5 million from current earnings of US$949.4 million.
Uncover why CNX Resources' fair value indicates that CNX Resources is in line with its current price.
Exploring Other Perspectives
One bullish twist on CNX Resources centers on how fast low carbon cash flows ramp rather than on the headline EPS for this quarter. The most optimistic analysts were penciling in about US$2.6b of revenue and US$893.8 million of earnings by 2029 before this US$0.65 EPS setup. That is a very different story from the consensus US$2.2b and US$435.9 million view. Use this earnings revision as a prompt to compare those opposing forecasts and decide which version of CNX lines up better with your own expectations.
Explore 2 other CNX Resources fair value estimates, including one that suggests potential upside of as much as 485% from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CNX Resources research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CNX Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CNX Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond CNX Resources?
If the CNX Resources setup has sharpened your thinking, use that same lens across the market by running a few focused screens on Simply Wall St. Let the data do the heavy lifting while you compare balance sheets, earnings power and risk levels in a structured way.
- For investors who want potential upside but still care about underlying quality, scan a curated group of higher quality outliers using the 21 high quality undiscovered gems.
- If capital preservation is front of mind and you prefer steadier profiles, narrow your watchlist with a 30 resilient stocks with low risk scores that filters for resilient businesses with more measured risk scores.
- When you want income as well as exposure to equities, focus on companies with sizeable yields and sturdier payout records through a 5 dividend fortresses aimed at higher yielding dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com