
Should Highland Valley Strike Require Action From Teck Resources (TSX:TECK.B) Investors?
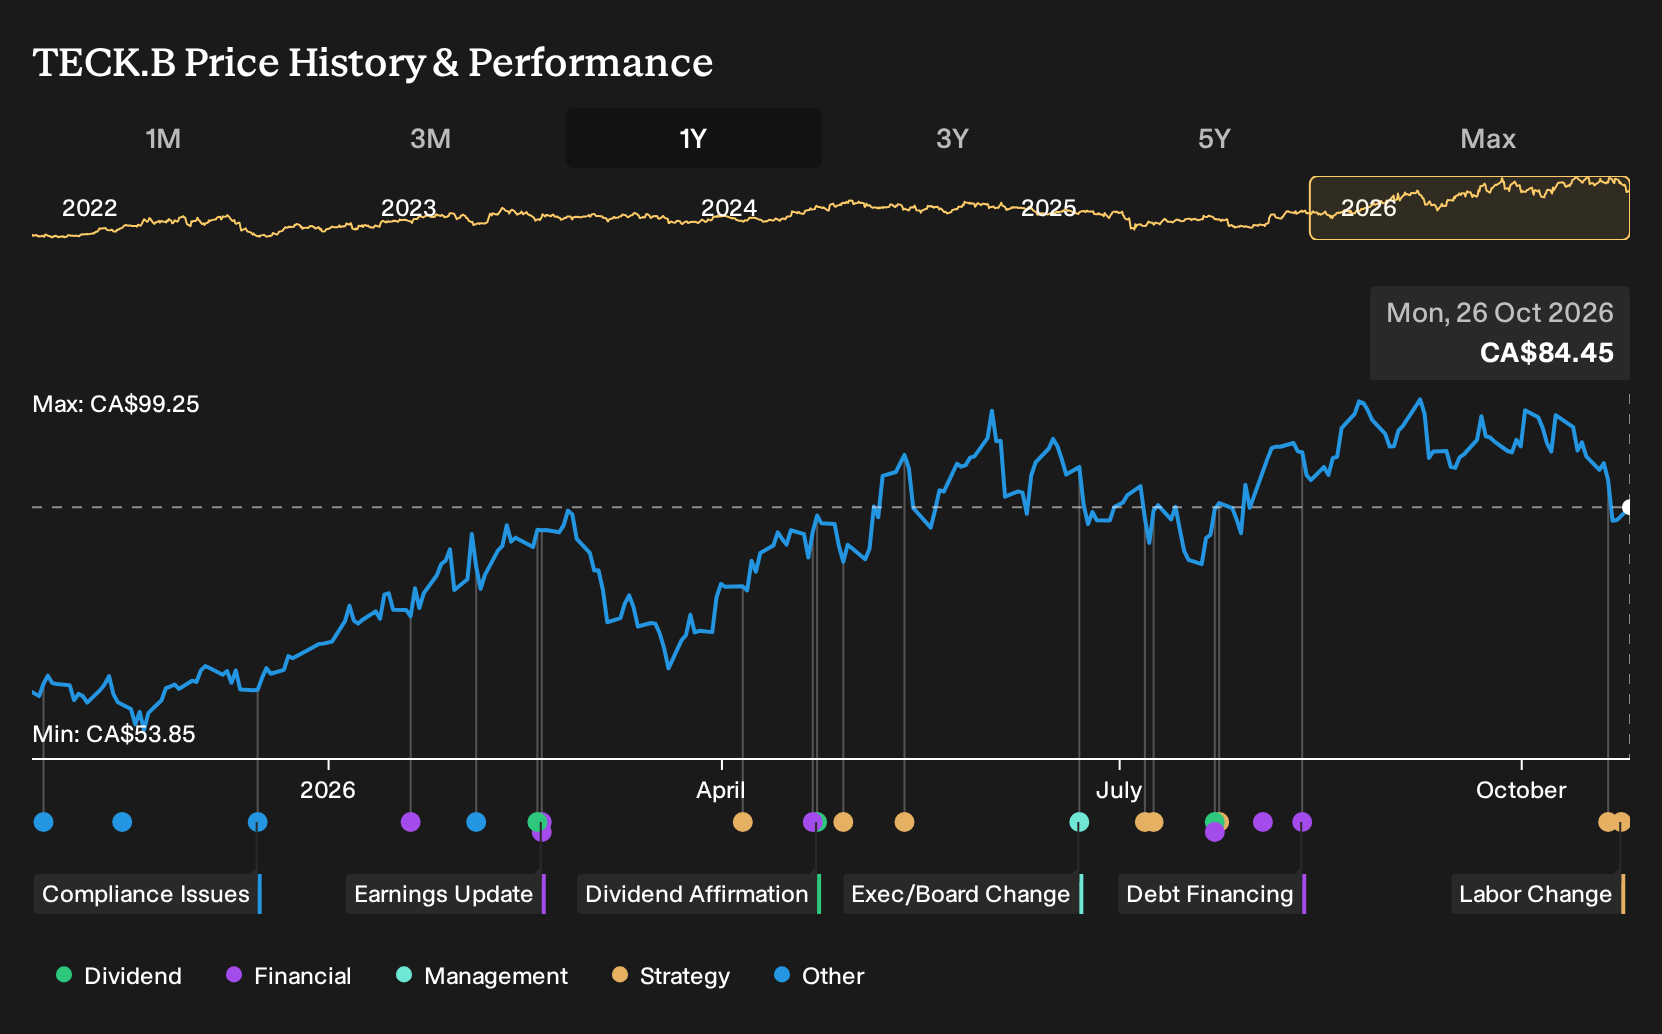
- Teck Resources has entered a strike at its Highland Valley Copper operations in British Columbia, where over 1,200 United Steelworkers members have walked off the job, pushing the mine into reduced capacity while the company runs contingency plans to protect safety and environmental standards.
- The labour dispute touches core cost and staffing issues at Highland Valley Copper, which is a key asset in Teck Resources' copper focused growth plans and long term production profile.
- We will now look at how Teck Resources' investment narrative around copper growth intersects with the Highland Valley Copper strike risk.
Teck Resources Investment Narrative Recap
To own Teck Resources, you need to believe the copper focused build out, including Highland Valley and Quebrada Blanca, will offset weaker zinc and heavy 2026 capex. The Highland Valley strike introduces execution risk at a key asset, although operations are still running at reduced capacity, so the near term production impact depends on how long the stoppage lasts.
The most important near term swing factor is whether Teck Resources can keep major copper projects and the Anglo American tie up on track while spending up to CA$3.4b on capex and up to CA$550m on capitalized stripping. The strike mainly amplifies the existing risk of delays or cost pressure at Highland Valley, rather than creating a new structural issue.
The 24 October 2026 announcement confirming strike action at Highland Valley Copper matters because it directly affects a project that already sits inside Teck Resources capital spending peak and life extension work. With over 1,200 unionized workers off site and the mine on reduced capacity, every extra week of disruption can make scheduling and budgeting more complicated.
For you as a shareholder, the link back to catalysts is clear. The Highland Valley life extension is intended to support a long copper production profile and underpin cash generation that helps fund Quebrada Blanca improvements, Trail expansion and the planned Anglo Teck merger. Prolonged labour action would increase execution risk around that copper narrative and may reduce room for error on 2026 free cash flow.
What The Highland Valley Strike Means For Teck Resources' Targets
Analysts currently frame Teck Resources around a copper heavy expansion story that still assumes gradual top line growth and slightly better profitability by the end of the decade. The Highland Valley labour action cuts across that storyline because it affects both near term production schedules and confidence in executing the longer life extension work without fresh cost surprises.
Consensus models build in revenue growth of 2.3% a year over the next three years and a lift in profit margins from 17.9% today to 18.4% by around 2029. Those are modest shifts on paper, but they rely on large, capital intensive projects like Highland Valley and Quebrada Blanca operating reliably while Teck Resources is already committing up to CA$3.4b of capex and as much as CA$550m of capitalized stripping in 2026.
On earnings, the analyst group is working with current profit of CA$2.5b and a central forecast of CA$2.8b by 2029, which is an increase of CA$0.3b. Forecasts range widely, from CA$1.0b at the low end to CA$3.2b at the high end, and that spread underlines how sensitive outcomes look to project delivery, copper volumes and unit costs. A prolonged disruption at Highland Valley would not automatically push earnings to the low end of the range, but it makes the upper end harder to justify unless Teck Resources offsets the impact elsewhere in the portfolio.
Revenue expectations also matter because the valuation work that analysts publish already factors in a 2029 top line of about CA$15.0b and earnings of CA$2.8b on a P/E of 21x. That multiple assumption is higher than the 18x P/E used today and above the broader US metals and mining sector at 15.2x. The current thesis therefore depends on Teck Resources hitting its copper growth and margin targets while convincing the market to pay a premium for that profile. Any perception that Highland Valley is structurally less reliable, whether from repeated strikes or schedule slippage, could make that premium more difficult to sustain.
Today the stock trades at CA$91.44, very close to the CA$91.82 consensus target, which suggests analyst models already view Teck Resources as roughly fairly valued on their current set of assumptions. For you as an investor, the Highland Valley strike effectively becomes a real time test of those inputs. If you think the labour dispute will be resolved on terms that keep the mine on track for its long life plan, the existing revenue and earnings path may still look reasonable. If you worry that stoppages or fresh concessions recur, the CA$15.0b revenue and CA$2.8b profit markers for 2029 could start to look more ambitious than the current share price implies.
Teck Resources is not a pure Highland Valley story. Quebrada Blanca, the proposed Anglo Teck merger and the Trail expansion each provide different levers that can cushion asset level shocks. Yet the Highland Valley strike highlights how concentrated the investment case is in a small set of copper projects that all need to move through heavy spending years without extended downtime. Your view on the strike, and on management's ability to manage relations with more than 1,200 organized workers at a key site, now sits alongside copper prices and project milestones as a central input to any risk assessment.
Teck Resources' narrative projects CA$15.0b revenue and CA$2.8b earnings by 2029. This assumes 2.3% yearly revenue growth and an earnings increase of CA$0.3b from CA$2.5b today.
Uncover how Teck Resources' fair value indicates a 9% potential upside to its current price that could narrow quickly if the copper story regains momentum.
Exploring Other Perspectives
Some of the most optimistic analysts saw the Anglo Teck merger as the real swing factor for Teck Resources, not labour stability at Highland Valley. They were pencilling in CA$17.3b of revenue and CA$3.2b of earnings by 2029 on a rich 24.9x P/E, before this strike news, which could shift those expectations. You are seeing that reasonable people can disagree sharply, so it makes sense to explore several viewpoints before deciding how this dispute fits your own thesis.
Explore 4 other Teck Resources fair value estimates, including one that suggests there could be as much as 48% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Teck Resources research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teck Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teck Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond Teck Resources?
If the Highland Valley story has you reassessing copper risk and position sizing, it can be useful to widen the lens and compare Teck Resources with other businesses that fit different return and risk profiles. The Simply Wall St Screener gives you ready made sets of opportunities so you can focus on the fundamentals that matter most to you.
- For investors who care most about quality and valuation discipline, you could review a curated 3 high quality undervalued stocks that pair solid financial profiles with prices that analysts judge as below intrinsic value.
- If resilience and capital protection sit at the top of your checklist, scan a 8 resilient stocks with low risk scores that score well on balance sheet strength and business risk.
- When you want something a little less crowded than a large cap like Teck Resources, look through a 9 high quality undiscovered gems that combine strong fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com