
Swire Properties (SEHK:1972) Climbed, So What Is Drawing Fresh Attention?
Recent commentary around discounted cash flow analysis has pushed Swire Properties (SEHK:1972) into focus, as investors weigh its expansion pipeline in Mainland China's Tier 1 and emerging Tier 1 cities against the current share price.
Swire Properties has benefited from a clear upswing in sentiment, with an 18.81% year to date share price return and a 21.23% 1 year total shareholder return. The 98.94% 3 year and 61.72% 5 year total shareholder returns point to momentum that investors are now re-testing against the latest DCF-driven undervaluation debate.
Scan 195 high quality undervalued stocks to see how Swire Properties compares with other cash flow backed real estate and infrastructure plays that may not be fully priced in yet.Swire Properties now trades at what looks like a discount to both analyst targets and intrinsic value, yet recent gains hint at lingering caution. Are investors right to hesitate, or is the gap too wide?
Most Popular Narrative: 13% Undervalued
Swire Properties is pegged with a fair value of HK$29.02 against a last close of HK$25.14. This frames the current DCF debate as a question of whether the market is underestimating its long-horizon cash flows or correctly pricing execution risk.
Robust balance sheet, low gearing, and disciplined capital recycling strategy provide Swire Properties with capacity for further opportunistic acquisitions and asset reinvestment, supporting recurring earnings and underpinning sustainable annual dividend growth.
See why 1 investors see Swire Properties as 13% undervalued.
Result: Fair Value of HK$29.02 (UNDERVALUED)
Still, weak Hong Kong and Mainland China office demand, along with a HK$100b investment program, could pressure rental income, asset values, and future returns if conditions soften.
Find out about the key risks to this Swire Properties narrative.
Another View On Swire Properties’ Valuation
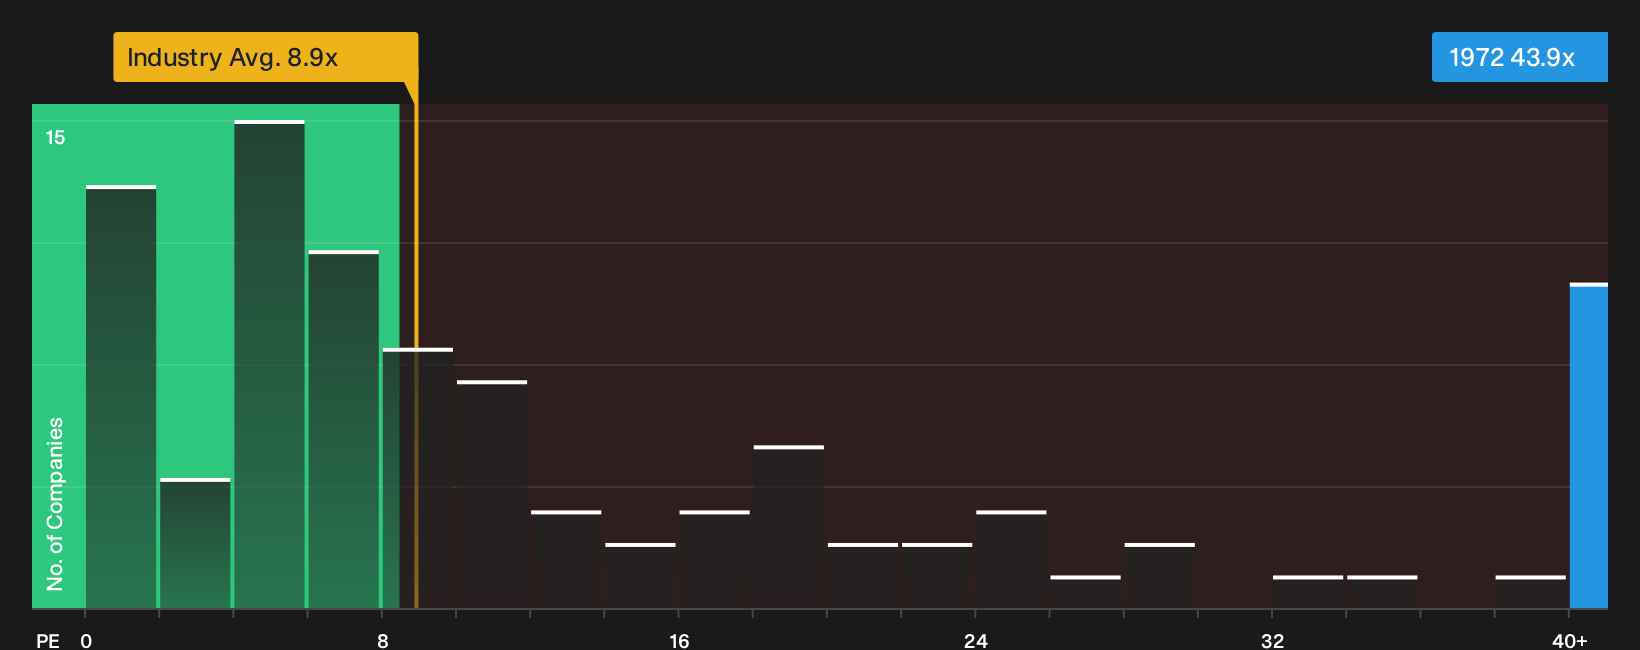
DCF work suggests Swire Properties trades below a HK$27.63 cash flow value and also below the HK$29.02 analyst fair value. Yet on a simple P/E basis it changes hands at 43.9x versus a 20x fair ratio and 8.9x for the Hong Kong real estate group. Is this a margin of safety or a valuation trap?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Swire Properties is split, with strong returns on one side and valuation questions on the other. Move quickly through the underlying numbers, read both the risks and the potential upsides, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Swire Properties?
If you want a wider view than Swire Properties alone, use the Simply Wall St Screener to spot other opportunities before they move out of reach.
- Target potential mispricings by scanning the 195 high quality undervalued stocks that align with your view on quality and price.
- Strengthen your income watchlist by checking out the 224 dividend fortresses that might help support more reliable cash flows.
- Protect the downside first by reviewing a 223 resilient stocks with low risk scores that could keep your portfolio on steadier footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com