
Job Cuts And Cost Savings Could Be A Game Changer For Volvo Cars (OM:VOLCAR B)
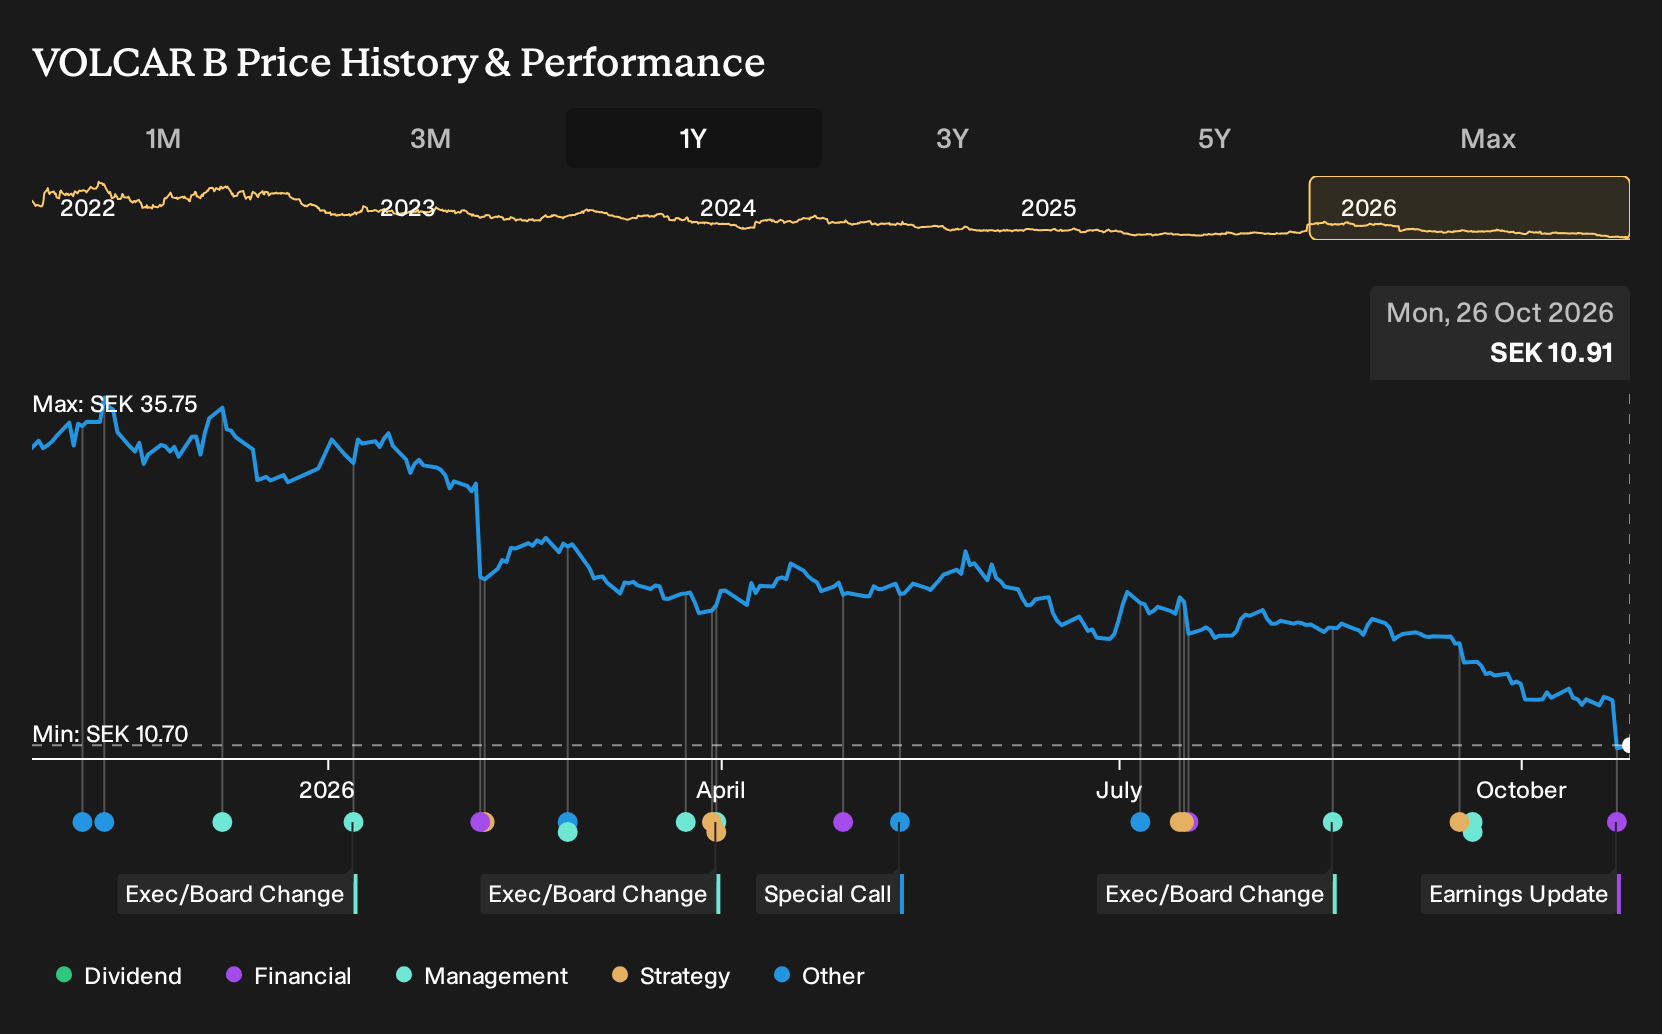
- Volvo Car AB (publ.) reported third quarter 2026 sales of SEK 66,896 million and a net loss of SEK 4,824 million, alongside a SEK 5 billion cost saving plan and about 2,500 global job cuts.
- The shift from profit to loss, combined with workforce reductions and pressure in China and the US, highlights how electrification spending and regional market stress are affecting Volvo Car AB (publ.)'s earnings profile and cash flow.
- The focus will now be on how Volvo Car AB (publ.)'s investment narrative is influenced by the sharp third quarter loss and the announced restructuring.
Compare Volvo Car AB (publ.)'s restructuring story with other businesses that may be better positioned today by scanning our hand picked 223 resilient stocks with low risk scores for sturdier balance sheets and lower risk profiles.
Volvo Car AB (publ.) Investment Narrative Recap
To own Volvo Car AB (publ.) today, you need to believe the heavy electrification spend and production shifts can eventually support a more sustainable, cash generative business. The recent third quarter loss and weaker nine month sales keep the near term focus squarely on stabilising operations in China and the US, where conditions are described as very tough.
The key short term catalyst is execution on cost reductions and working capital discipline, so that losses do not drain financial flexibility while EV demand remains pressured. The biggest risk is that pricing pressure, tariffs and ongoing electrification investment keep profitability subdued for longer than the balance sheet comfortably allows.
The most relevant development is the expanded SEK 5b cost saving programme. This includes about 2,500 global job cuts and targets almost 25% lower indirect expenditure by the end of 2027 compared with fiscal 2024. Paired with the SEK 18b turnaround plan, this provides a concrete execution yardstick rather than just a headline promise.
For shareholders, the operational story now hinges on whether Volvo Car AB (publ.) can translate these cost actions into a clearer path back to positive earnings and free cash flow, while it ramps locally produced EVs and manages exposure to China and US tariffs. Progress against those savings and EV rollout milestones is likely to shape how the next leg of the share price story develops.
Volvo Car AB (publ.) Forecasts And Valuation Anchors
Volvo Car AB (publ.) now trades against a set of expectations that are quite specific. Analysts are pencilling in 3.3% yearly revenue growth over the next few years, a marginal lift in profit margins from 2.8% today to 2.9%, and earnings that could reach SEK 10.7b by 2029 compared with SEK 9.3b today. That implies an earnings increase of about SEK 1.4b from current levels and is being paired with an assumed P/E multiple of 5.9x on those 2029 earnings, up from 4.5x right now, versus a sector reference point of 10.2x for the SE Auto industry.
On the top line, the consensus narrative has Volvo Car AB (publ.) reaching SEK 365.0b of revenue and SEK 10.7b of earnings by 2029. To get there, the model bakes in 3.3% annual revenue growth and an earnings uplift of roughly SEK 1.4b from earnings today of SEK 9.3b.
Uncover how Volvo Car AB (publ.)'s fair value indicates a 45% potential upside to its current price before sentiment around Volvo Car AB (publ.)'s turnaround shifts.
Exploring Other Perspectives
Some of the most optimistic analysts framed Volvo Car AB (publ.)'s electrification push as a major catalyst, expecting revenue to reach about SEK 396.1b and earnings of SEK 15.9b by 2029, instead of the consensus SEK 365.0b and SEK 10.7b. Those projections were set before this loss and restructuring update, so you should expect views to evolve and consider several angles yourself.
Explore 4 other Volvo Car AB (publ.) fair value estimates, including one that suggests as much as 872% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Volvo Car AB (publ.) research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Volvo Car AB (publ.). The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Volvo Car AB (publ.)'s overall financial health at a glance.
Looking for more investment ideas beyond Volvo Car AB (publ.)?
If Volvo Car AB (publ.)'s restructuring story has sharpened your focus on risk, balance sheets and future earnings power, it can help to line it up against businesses with very different profiles. The Simply Wall St Screener lets you scan for other stocks that match the kind of financial traits and resilience you want in your portfolio.
- If capital preservation is top of mind, consider focusing on resilience and stability through a 223 resilient stocks with low risk scores that screens for businesses with steadier profiles and fewer red flags.
- For income focused investors, target dependable cash distributions with a 224 dividend fortresses that surfaces companies offering higher yields with a focus on sustainability.
- If you prefer to hunt for mispriced opportunities, cast a wider net using a 195 high quality undervalued stocks that highlights stocks combining stronger fundamentals with potentially attractive valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com