
Did Earnings Beat Just Shift Sun Communities (SUI) Investment Narrative?
- Sun Communities reported Q3 2026 revenue of US$558.2 million and net income of US$120.7 million, with basic earnings per share from continuing operations of US$1.07, compared with a basic loss per share from continuing operations of US$0.45 a year earlier.
- The business recorded a net loss of US$880.7 million over the first nine months of 2026, even as earnings from continuing operations and a completed US$373.1 million buyback pointed to a focus on core profitability and capital return.
- We will now look at how Sun Communities' sharp swing to higher quarterly earnings per share may influence the longer term investment narrative.
Sun Communities Investment Narrative Recap
To own Sun Communities, you need to be comfortable with a story built on stable manufactured housing demand, RV execution and careful balance sheet work. The sharp improvement in Q3 earnings from continuing operations supports that operating thesis in the near term. The bigger swing factor remains how consistently the MH and RV portfolios can translate high occupancy and technology investments into steady, repeatable cash flows.
The short term catalyst many investors are watching is progress on portfolio simplification and debt reduction tied to the planned U.K. Park Holidays sale. That sits alongside the main risk: a mix of high leverage, past governance concerns and the large nine month net loss, which could limit flexibility if operating trends soften.
The completed US$373.1 million buyback of 3,100,000 shares, or 2.52% of the register, is the most relevant recent announcement alongside the Q3 numbers. It pairs a cleaner quarter for earnings from continuing operations with a reduced share count, which together can sharpen the focus on per share metrics rather than headline net loss volatility.
For you as a shareholder, that repurchase sits directly in the middle of the current catalysts and risks. It reinforces Sun Communities’ preference for capital return at a time when analysts highlight high debt, one off items in recent results and sensitivity in the RV mix. Execution now needs to come through in consistent MH and RV cash generation to support that capital allocation story.
Sun Communities' narrative projects US$2.3b revenue and US$483.0 million earnings by 2029. This reflects relatively flat yearly revenue trends and an earnings increase of about US$346.5 million from current earnings of US$136.5 million.
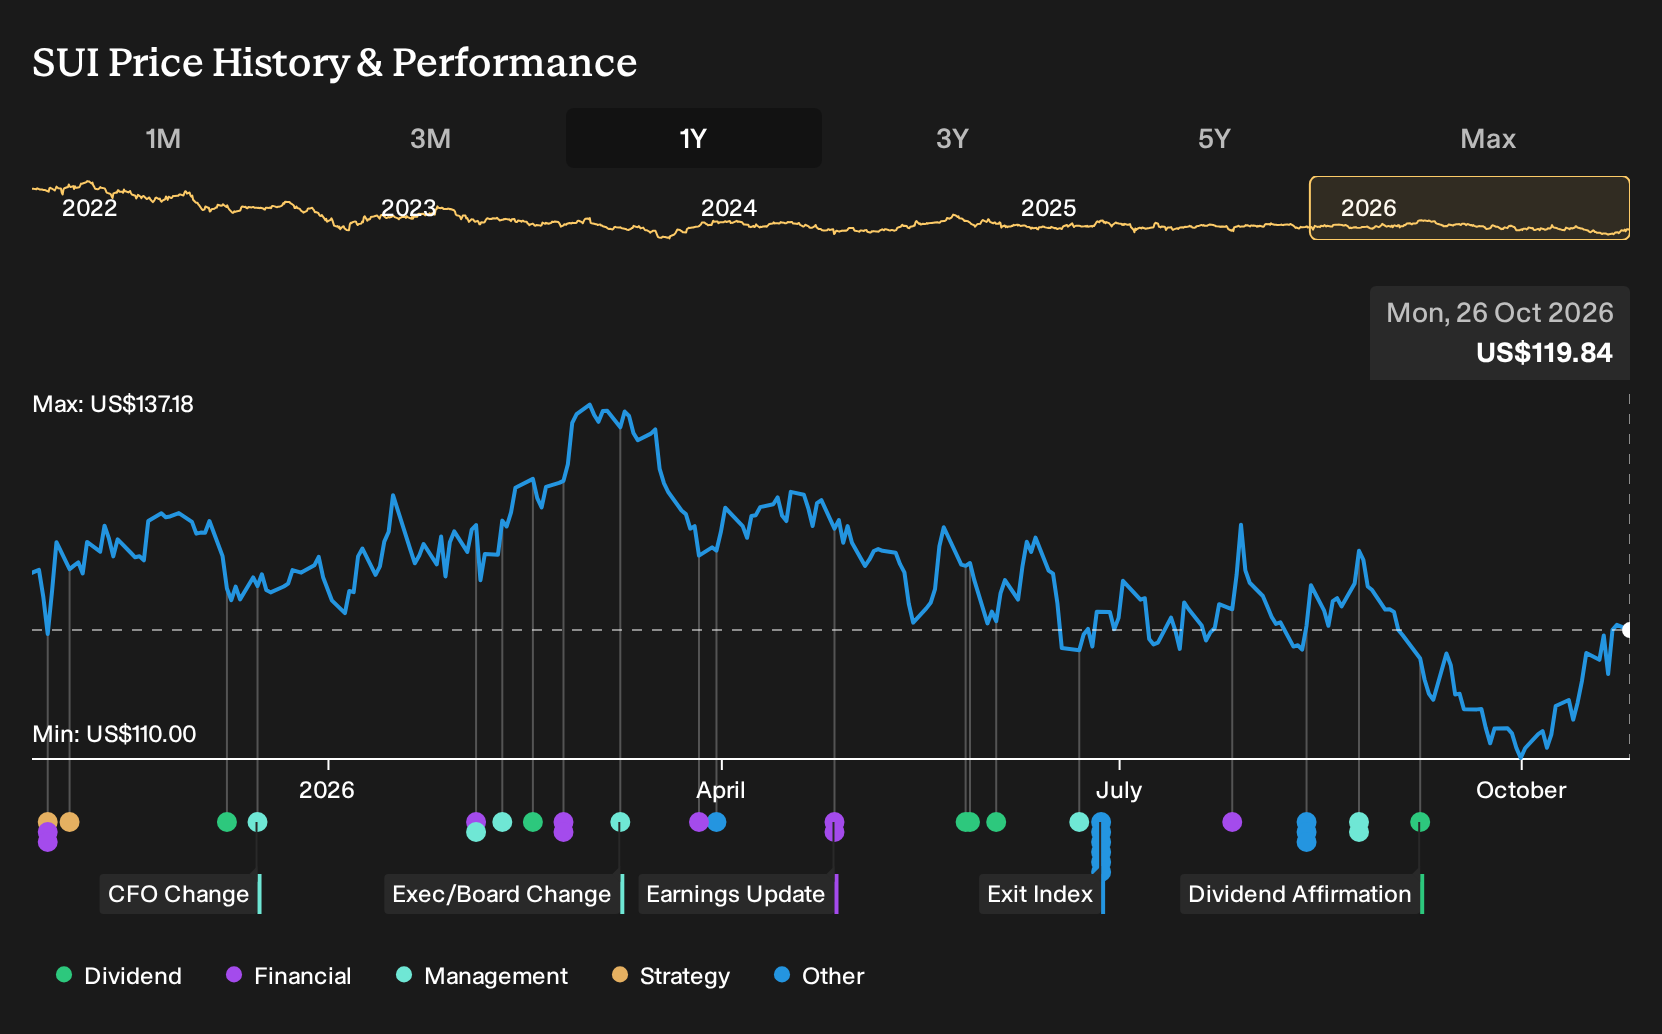
Uncover how Sun Communities' fair value indicates a 13% potential upside to its current price. This upside could narrow quickly if Sun Communities keeps cleaning up its story.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$136 to US$207 per share, so you are seeing a wide personal valuation band around Sun Communities. Those views sit beside risks around RV mix, governance history and refinancing costs, which together can materially influence how the next phase of earnings is priced.
Explore another Sun Communities fair value estimate, including one that suggests as much as 73% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sun Communities research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sun Communities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sun Communities' overall financial health at a glance.
Looking For More Ideas Beyond Sun Communities?
If you want to put Sun Communities in context and line it up against other opportunities, the Simply Wall St Screener can help you scan the market quickly and stay focused on the type of businesses that suit your style.
- For investors who care most about quality at a reasonable entry point, compare Sun Communities with a broader set of companies trading on attractive metrics through our 29 high quality undervalued stocks.
- If capital preservation and resilience matter most to you, filter for companies that pair sturdier balance sheets with cleaner financial profiles by using the list of solid balance sheet and fundamentals (24 results).
- When you want fresh angles and potential outliers, broaden your watchlist with a curated 21 high quality undiscovered gems that many investors may not be tracking yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com