
Alfa Laval (OM:ALFA) Posts Strong Q3 Growth, Is The Stock Fairly Valued?
Alfa Laval (OM:ALFA) drew attention after third quarter results showed a 36% rise in order intake, growing net sales and higher adjusted EBITA, even as management flagged slightly softer demand for the coming quarter.
Despite the strong order intake, the Alfa Laval share price has eased in the short term, with a 7 day share price return of 3.9% lower and a 30 day share price return of 2.5% lower. However, the year to date share price return of 17.3% and a 1 year total shareholder return of 18.5% show that longer term momentum has been positive.
Scan how Alfa Laval compares to other industrial heavyweights by running the list of solid balance sheet and fundamentals (207 results) that could be better placed for the next phase of the cycle.
After that pullback, Alfa Laval trades around a 7% discount to analyst targets but at a premium to some intrinsic value estimates. Is the market simply being cautious, or is it fairly pricing in softer near term demand and recent earnings?
Most Popular Narrative: 6% Undervalued
On Simply Wall St’s most followed narrative, Alfa Laval screens as slightly cheap, with a fair value of SEK584.94 against the last close of SEK549.60. This perspective places more emphasis on long term project visibility than on the recent share price wobble.
The multiyear CapEx cycle in shipping and offshore, together with cargo pumping orders now booked into 2028 and a SEK 4 billion CapEx program in Framo pumping systems, underpins a long Ocean division order book that can support future invoicing levels and divisional EBITA margins.
See why 14 investors see Alfa Laval as 6% undervalued.
Result: Fair Value of SEK584.94 (UNDERVALUED)
Still, the Alfa Laval story can quickly look different if energy transition projects stall or if marine and LNG orders fade faster than expected.
Find out about the key risks to this Alfa Laval narrative.
Another View On Alfa Laval’s Valuation
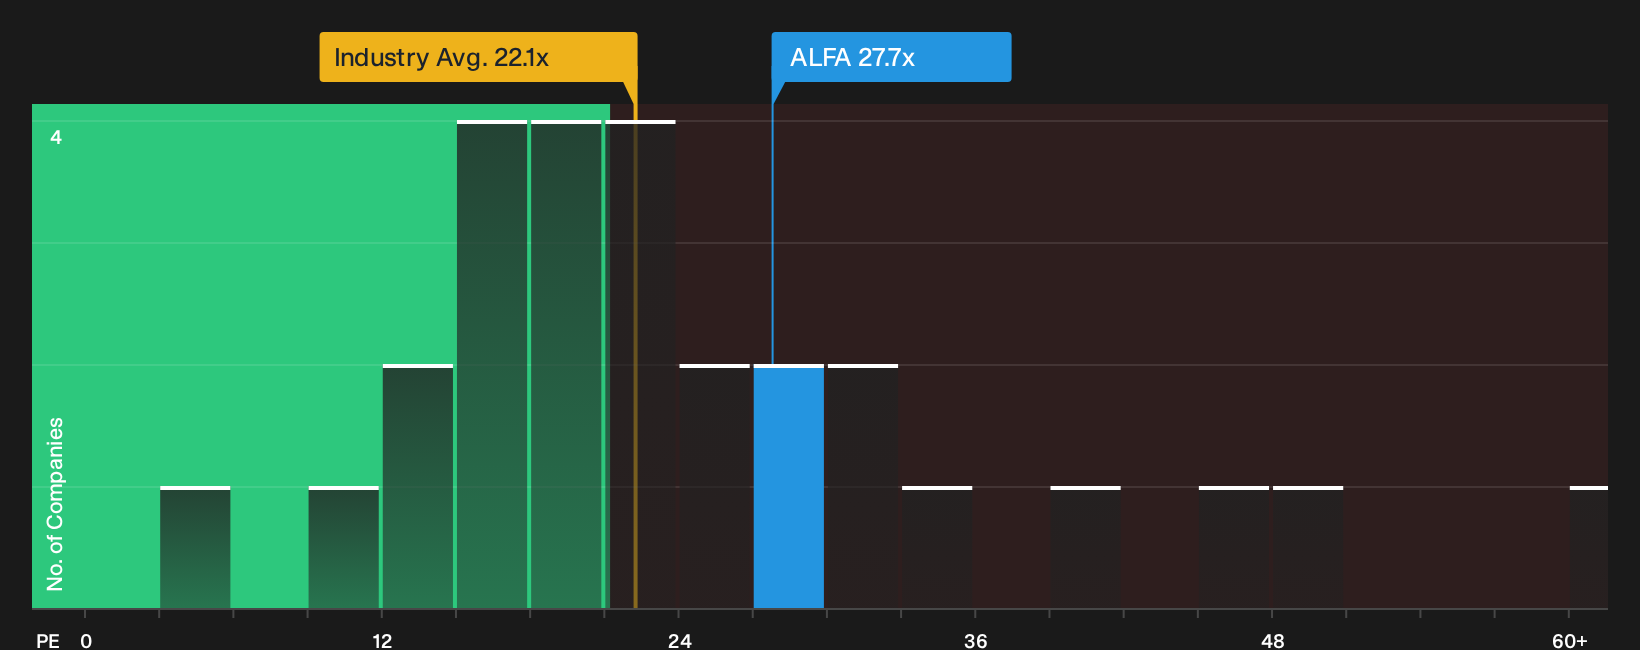
The narrative model suggests Alfa Laval is about 6% undervalued, yet the P/E picture looks tighter. The shares trade on 27.7x earnings against a fair ratio of 27.2x, above both peers at 26x and the Swedish Machinery group on 22.1x. That richer multiple raises the question of how much upside the market is really leaving on the table.
For a closer look at how this earnings multiple stacks up in practice, including where the fair ratio could pull the share price over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Alfa Laval is mixed in the short term, so take this as a prompt to act quickly, review the data, and pressure test the assumptions. Then weigh those findings against the 2 key rewards
Looking for more investment ideas beyond Alfa Laval?
If Alfa Laval is on your radar, broaden your watchlist now with a few targeted stock ideas that match different risk levels and return goals.
- Target resilient balance sheets and steady business quality by scanning the list of solid balance sheet and fundamentals (207 results) that already filters for financial strength.
- Hunt for mispriced opportunities by running the 195 high quality undervalued stocks that surfaces companies combining quality fundamentals with discounted market prices.
- Build a cash flow focused portfolio by reviewing the 224 dividend fortresses that highlights higher yielding payouts backed by underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com