
Zebra Technologies (ZBRA) Gains An AI Proof Point As Valuation Stays In Focus
Why Zebra Technologies Stock Is Back In Focus
Zebra Technologies (ZBRA) is back on investor radars after ORAFOL Fresnel Optics used its AI machine vision tools to automate inspection of over 1.5 million optical lenses.
The project replaced manual lens checks that needed up to 15 operators and specific lighting conditions. ORAFOL now runs 24/7 inspection with Zebra Aurora Vision Studio and deep learning, cutting inspection times and adding full component traceability.
The ORAFOL win comes at a time when Zebra Technologies’ share price has climbed 35.1% over the past 90 days and 54.7% year to date. The 1-year total shareholder return of 23.7% contrasts with a 5-year total shareholder return that is still down 29.2%, pointing to recovering momentum but a mixed longer-term picture.
Spot similar AI-driven industrial plays by scanning our hand picked 94 robotics and automation stocks that are moving fast on automation and machine vision.Zebra Technologies now looks like a stronger operation than its 5 year return record suggests, especially after this latest AI win. After a 54.7% jump year to date, is that strength already fully priced in?
Most Popular Narrative: 7% Undervalued
On the most followed view of Zebra Technologies, a fair value of $414.52 sits modestly above the last close at $384.15. This puts recent AI wins and automation demand into context rather than rewriting the story.
The capital light model and capital allocation approach at Zebra Technologies, which combines ongoing R&D investment at just over 9% of sales, portfolio expansion through acquisitions such as Elo and Photoneo, and sizable share repurchases that are guided to about US$700 million in 2026 while holding leverage below 2x, are expected to support free cash flow, EPS growth and support for the current valuation.
See why 30 investors see Zebra Technologies as 7% undervalued.
Result: Fair Value of $414.52 (UNDERVALUED)
Still, the Zebra Technologies story could look very different if tariff costs climb again or if price pressure in new consumer facing segments squeezes margins.
Find out about the key risks to this Zebra Technologies narrative.
Another View: Zebra Technologies On Earnings Multiples
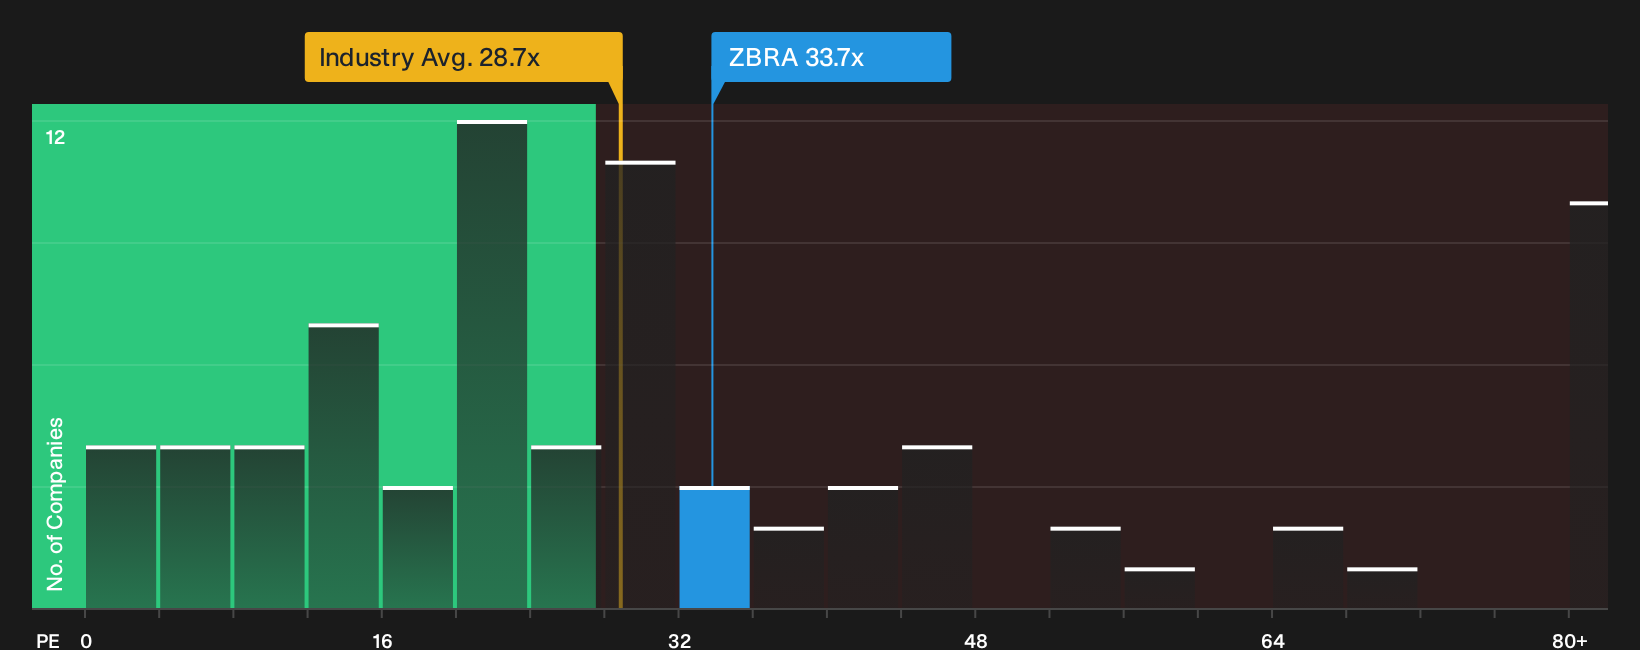
The story looks different once the focus shifts from discounted cash flows to simple earnings multiples. Zebra Technologies trades on a P/E of 33.7x, which is higher than the US Electronic industry at 28x and above its own fair ratio estimate of 30x.
A richer multiple than both the sector and that fair ratio points to less margin for error if growth or profitability fall short of expectations. It can still be good value relative to peers on 41.5x, but which comparison you trust more will shape how comfortable you feel with the current price.
See what the numbers say about this price in more detail, then decide which valuation lens you put more weight on See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and concern around Zebra Technologies feels finely balanced, consider acting quickly: review the detail and weigh both sides of the story with 2 key rewards and 2 important warning signs
Looking For More Ideas Beyond Zebra Technologies?
If Zebra Technologies has sharpened your focus on quality, do not stop here. Broaden your watchlist now or risk missing the next move.
- Target resilience by scanning a 30 resilient stocks with low risk scores that may help you sidestep fragile businesses when conditions change.
- Hunt for potential bargains through a 21 high quality undiscovered gems that highlight strong fundamentals before the crowd pays attention.
- Prioritise financial strength using a list of solid balance sheet and fundamentals (24 results) so you can focus on companies with robust cushions against shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com