
Top Canadian Dividend Stocks For October 2026
AI heavyweights such as Anthropic are racing to raise huge amounts of capital for data centers and chips, and that spending needs to be funded. As money pours into growth projects, many investors still want a stream of cash coming back to them. This piece looks at three Canadian high-yield dividend stocks from a curated screen of companies paying 3%+ with payouts that appear covered, growing and relatively steady.
The three stocks highlighted here offer a compelling starting point if you want exposure to larger dividend powerhouses where yields above 3% are paired with covered, growing and relatively steady payouts. However, if you want the names that matter most, these 3 dividend aristocrats stocks are the strongest companies we've found.
Sun Life Financial (TSX:SLF)
Overview: Sun Life Financial provides life and health insurance, wealth solutions and asset management services, using these cash-generating businesses to fund shareholder dividends.
Operations: Sun Life Financial generates most of its revenue from Canada at about CA$15.7b, the U.S. at CA$13.0b, SLAM at CA$7.7b and Asia at CA$2.6b.
Market Cap: CA$61.7b
Sun Life Financial matters in a 3%+ dividend screen because its life insurance and asset management cash flows are built for recurring payouts.
"Strong growth in Asia individual insurance sales, with $875 million of quarterly sales and over $7 billion of contractual service margin in the region, supports the view that Sun Life Financial can keep expanding its addressable market and add new premium and fee income streams that feed into earnings growth."
The biggest swing factor for Sun Life Financial’s dividend appeal is how one pressure point ultimately shapes margins and long-term earnings momentum.
That pressure point is exactly what the full narrative for Sun Life Financial unpacks, showing where dividend strength could accelerate and which risks might quietly cap Sun Life Financial’s potential.

Magna International (TSX:MG)
Overview: Magna International designs, engineers and builds automotive systems, components and complete vehicles for global carmakers, with ADAS and electrified modules helping underpin its covered 3%+ dividend.
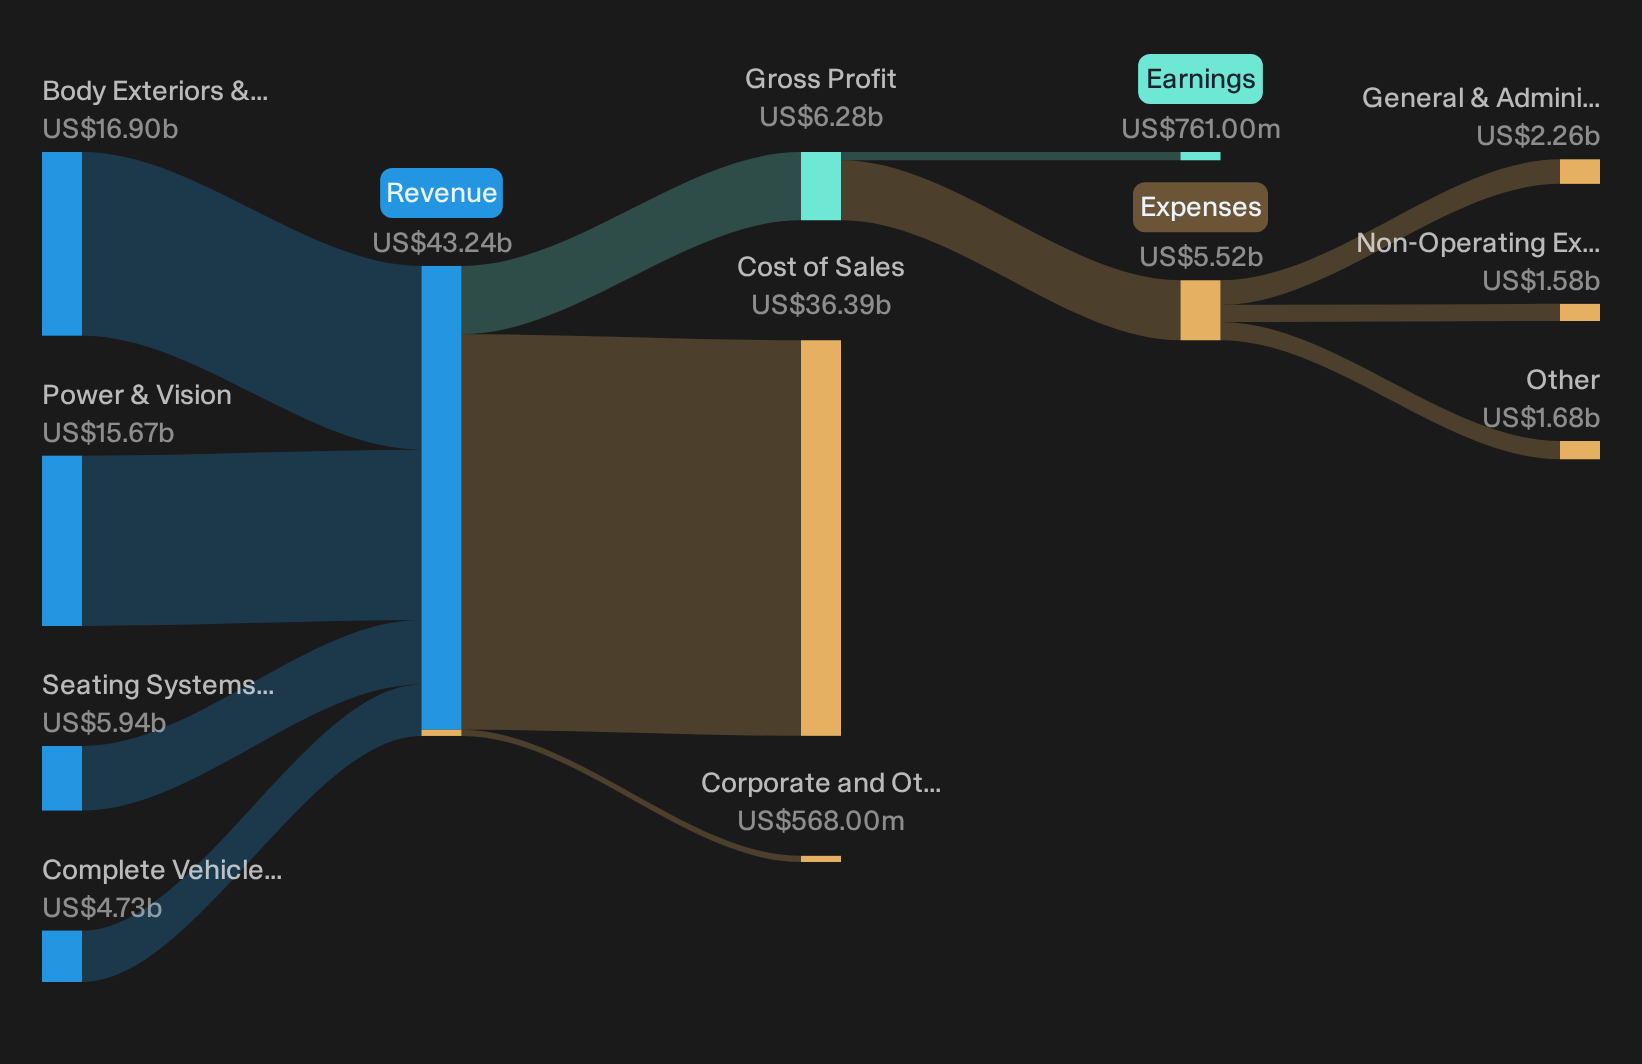
Operations: Magna International generates most of its sales from Body Exteriors & Structures at US$16.9b, Power & Vision at US$15.7b, Seating Systems at US$5.9b and Complete Vehicles at US$4.7b.
Market Cap: CA$23.8b
For income investors, Magna International matters here because its cash generation from Power & Vision and Complete Vehicles helps support a reliable, covered dividend while the broader parts portfolio spreads risk across multiple profit streams.
"The company anticipates meaningful improvements in free cash flow as sub 4% capex and greater reuse of EV equipment reduce capital intensity while structurally higher conversion supports the recent US$1.8b full year 2026 free cash flow guidance."
The real swing factor is whether margin programs translate into lasting earnings quality if a single key assumption about cost discipline changes.
If that cost discipline assumption interests you, the full narrative for Magna International shows where Magna International’s cash conversion could accelerate, stall or be quietly reshaped by EV and ADAS programs.
Bank of Nova Scotia (TSX:BNS)
Overview: Bank of Nova Scotia is a full-service bank that uses Canadian and international retail and commercial franchises to generate dividend-supporting income.
Operations: Bank of Nova Scotia earns about CA$11.9b from Canadian Banking, CA$9.6b from International Banking, and roughly CA$7.1b from Global Wealth Management.
Market Cap: CA$158.2b
Bank of Nova Scotia matters in this Dividend Powerhouses screen because its Canadian and International Banking arms generate recurring interest and fee income that underpin a covered, 3%+ yield.
"Expansion of banking and wealth management services in Pacific Alliance markets such as Mexico, Peru, Chile and Colombia remains a live driver, with International Banking revenue and loan growth in these regions and ROE above 16% pointing to further potential for fee income and earnings growth as Bank of Nova Scotia continues to deepen client relationships."
What could be especially important from here is how the balance between growth ambitions and credit discipline shapes the durability of that income stream.
To see how that balance between ambition and discipline really plays out, read the full narrative for Bank of Nova Scotia and identify where earnings strength may be accelerating or quietly stalling.

Seeking Fresh Alternatives Before Others Do
Fresh dividend and AI stories gain momentum fast while old ideas get caught dropping out of focus. Scan what is still under the radar for now and get in early.
- Spot resilient income payers before the crowd by zeroing in on a curated 3 dividend fortresses that focus on durability while yields remain compelling, then decide which ones fit your portfolio.
- Chase real business traction instead of hype by filtering for 39 profitable AI stocks that aren't just burning cash where revenue and cash generation already support operations, keeping your AI watchlist grounded in fundamentals.
- Position ahead of long-cycle infrastructure themes by scanning 42 power grid technology and infrastructure stocks powering transmission upgrades and grid modernization while this story is still building, and act while it matters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com