
LXP Industrial Trust (LXP) Could Be 34% Below Fair Value Following Buyout Approval
LXP Industrial Trust (LXP) shareholders have overwhelmingly approved a buyout by Brookfield Asset Management and Canada Pension Plan Investment Board, paving the way for a planned November 2, 2026 closing and subsequent NYSE delisting.
LXP Industrial Trust shares now trade at US$61.11, and the steady share price return over the year contrasts with much stronger total shareholder return figures, helped by dividends and the takeover premium as momentum builds ahead of the planned acquisition closing.
Scan other industrial REITs with similar momentum and income profiles by reviewing our curated list of list of solid balance sheet and fundamentals (24 results)
LXP Industrial Trust now trades slightly above analyst targets yet still screens at a sizeable intrinsic discount. Is that a mispriced cushion, or a warning that the market’s caution on the pending buyout is justified?
Most Popular Narrative: 3% Overvalued
LXP Industrial Trust closed at $61.11 against a narrative fair value of $59.24, so the current buyout driven price slightly exceeds that modeled estimate, with the gap hinging on how future earnings and margins evolve under existing assumptions.
The current valuation and recent third party assessments indicate that LXP Industrial Trust’s share price already reflects much of its industrial rent growth and balance sheet progress, with limited upside and risk skewed toward a bearish outcome if expectations are not met.
See why 2 investors see LXP Industrial Trust as 3% overvalued.
Result: Fair Value of $59.24 (OVERVALUED)
Still, any persistent pressure on same store NOI growth or difficulty re leasing large single tenant assets could quickly challenge the current LXP Industrial Trust narrative.
Find out about the key risks to this LXP Industrial Trust narrative.
Another View: Cash Flow Says Undervalued
The narrative fair value pegs LXP Industrial Trust at $59.24 and labels the stock as slightly overvalued. A different lens tells a very different story. Our DCF model estimates future cash flows at $81.95 per share, which frames the current $61.11 price as trading at a sizeable discount.
The contrast is stark. One approach leans heavily on earnings and a 61.9x P/E that screens as expensive against peers, while the cash flow model focuses on long term rental streams and suggests underpricing. Which yardstick do you trust more for a REIT driven by contractual rents and development yields?
Look into how the SWS DCF model arrives at its fair value. Look into how the SWS DCF model arrives at its fair value.
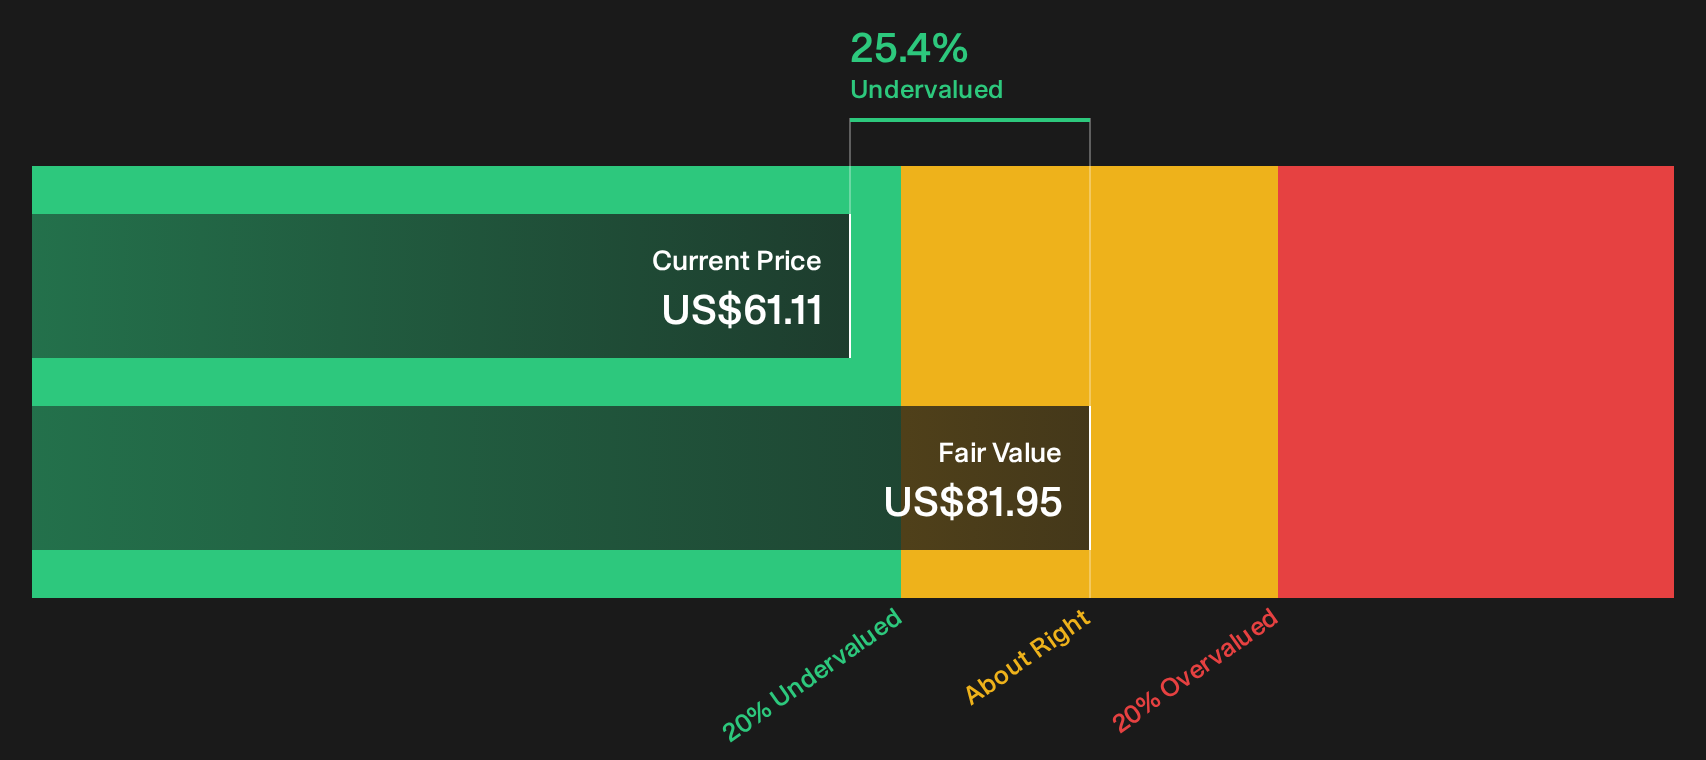
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LXP Industrial Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With narratives split between modest overvaluation and a DCF driven discount, the picture around LXP Industrial Trust is clearly mixed. Consider acting before the buyout timeline firms up further, and weigh the trade off between these signals yourself by reviewing the 1 key reward and 3 important warning signs
Looking for more ideas beyond LXP Industrial Trust?
Do not stop with one potential opportunity. Broaden your watchlist now with a few focused stock ideas that match different risk, income, and value preferences.
- Hunt for mispriced quality by scanning our curated pool of 29 high quality undervalued stocks that pair solid fundamentals with attractive valuations.
- Strengthen your income stream by reviewing 5 dividend fortresses that combine higher yields with business profiles built around consistent payouts.
- Keep risk in check and protect your downside by filtering for 30 resilient stocks with low risk scores that show more resilient balance sheets and cleaner financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com