
CrowdStrike (CRWD) Stock May Look Fully Priced As AI Security Ties Expand
CrowdStrike Holdings has delivered very strong share-price gains in recent years, which puts a spotlight on whether the current valuation lines up with the sales the company is generating. With the stock now in focus after a sharp multi year run, the open question is how much of its growth story is already reflected in the price you see on screen today.
- Over the past 3 years the share price has risen by a very large amount, which raises the stakes on whether that move is matched by the underlying revenue base.
- The collaboration with NVIDIA to extend CrowdStrike's Falcon Guardian security into AI infrastructure can support higher expectations for future sales if enterprises adopt these combined solutions at scale.
- Your read on CrowdStrike Holdings is one view; the desks covering it have another. See what analysts think CrowdStrike Holdings's shares could be worth.
The issue now is whether CrowdStrike's current market value is justified by its sales when you look past the recent share-price performance and headline partnerships.
If you are weighing CrowdStrike Holdings against other AI security and infrastructure plays, it can help to compare it with a broader group of 55 AI infrastructure stocks.
Has CrowdStrike Holdings Run Too Far on Sales?
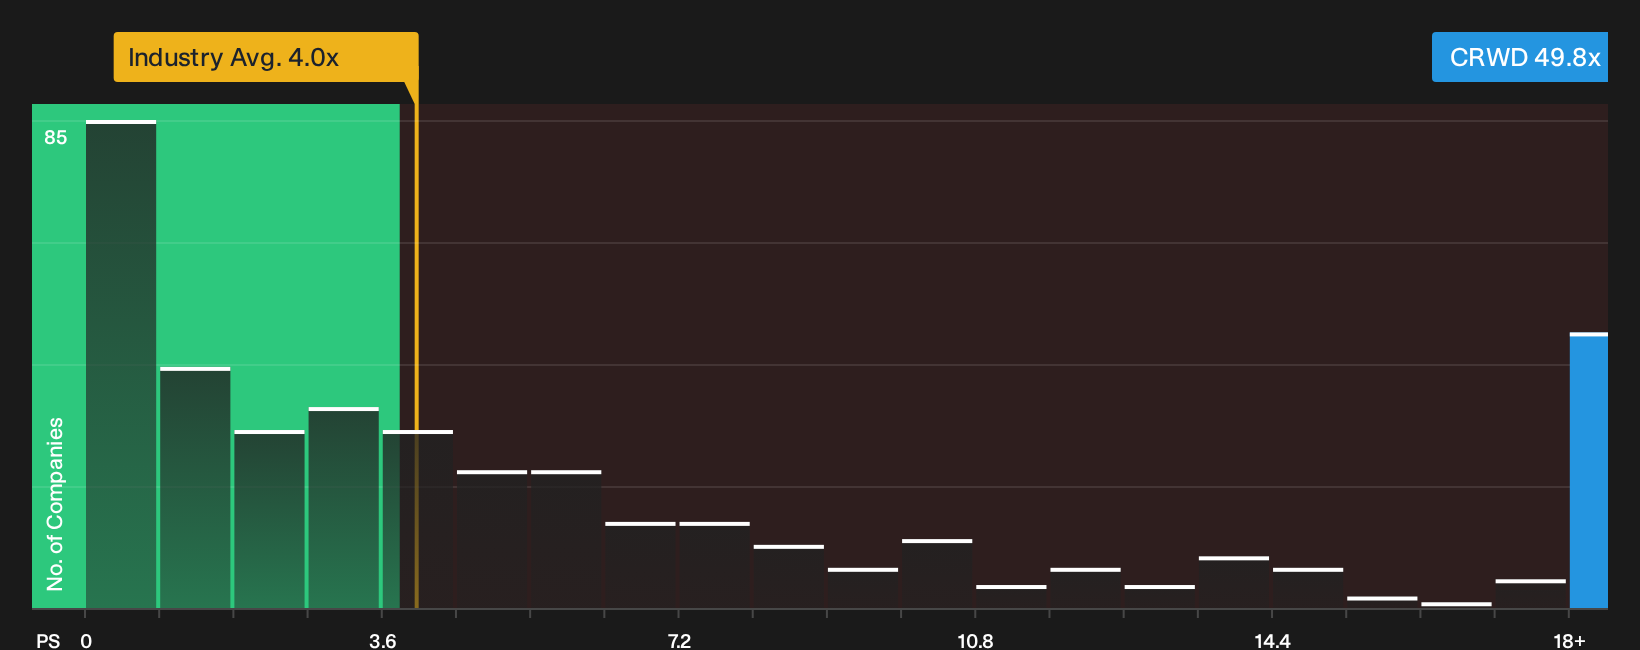
P/S is a useful yardstick for CrowdStrike Holdings because investors often focus on its top line rather than current earnings. Right now the stock trades on a P/S of 49.8x, well above the broader software industry on 4.0x and also ahead of the AI focused peer group around 15.5x. Based on the fair multiple implied by its own profile, that gap points to the shares screening as overvalued on sales.
Because the NVIDIA collaboration puts CrowdStrike directly into high profile AI security infrastructure conversations, it can help explain why buyers are willing to pay such a steep sales multiple compared with both sector and peer benchmarks. For a holder, the key question is whether the revenue opportunity and margin potential that the market is factoring in justify paying more than three times the peer group P/S for each dollar of current annual revenue. Explore the numbers behind CrowdStrike Holdings's P/S valuation.
The CrowdStrike Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CrowdStrike Holdings' stock pick up where the P/S puzzle leaves off and turn it into a set of clear future conditions that would need to play out in growth, margins and earnings for the shares to be worth much more or much less than today. Instead of just giving a single number from a model, Narratives spell out the future that number assumes so you can watch CrowdStrike Holdings' actual progress against it over time on the Community page.
Community views on CrowdStrike Holdings split between those who see more AI driven upside ahead and those who think a lot is already in the price.
Bull case: 19% undervalued
"Deepening integrations with AI and data partners such as Anthropic, NVIDIA, OpenAI and Snowflake give customers ways to apply existing AI compute and token budgets to Falcon and SafeMind usage..."
Discover why this Narrative puts CrowdStrike Holdings at 19% undervalued.
Bear case: 7% overvalued
"The current valuation reflects a share price that, according to this narrative, already assumes CrowdStrike achieves multi billion dollar ARR contributions from newer businesses such as AI security, next generation SIEM, identity and cloud security, together with high free cash flow margins..."
Explore why this Narrative puts CrowdStrike Holdings at 7% overvalued.
CrowdStrike Holdings' next puzzle, who is steering the ship and what are they working toward?
Valuation only tells you what the market is willing to pay, not whether the people running CrowdStrike Holdings are rewarded for the same outcomes you care about as a shareholder. See who runs CrowdStrike Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com