
Canadian Stock Market Today: TSX Futures Steady As Traders Brace For BoC Hike
The Morning Bull - Canadian Market Morning Update Tuesday, 27 Oct 2026
Canadian stocks look set for a slightly cautious open, with attention anchored on the Bank of Canada rather than offshore headlines. The central bank’s rate decision tomorrow is the single factor shaping sentiment across the Canadian market today.
Consensus expects the BoC policy rate to move from 2.25% to 2.5%, with the decision, statement and Monetary Policy Report all due on Wednesday. That cluster of events gives investors a clear focal point for how the bank currently sees inflation and growth risks.
Rate expectations feed directly into borrowing costs for households and businesses, which in turn influence credit demand and capital spending plans. When investors reassess the path for policy, they also reassess earnings sensitivity in more leveraged sectors and reprice longer dated Canadian bond yields.
The open question now is how forcefully the BoC signals its next steps. Any hint that 2.5% is not the peak, versus language that suggests a wait and see stance, could quickly tilt both equity and currency positioning.
Stocks to Watch Before the Opening Bell
Energy Fuels (EFR)
Energy Fuels just secured conditional credit approval for up to A$180 million from two Australian government lenders to help fund Phase 1 of the Donald Rare Earth and Mineral Sands Project. The funding supports construction planning and moves the asset closer to a final investment decision expected by the end of 2026.
For you, the key angle is rare earth supply. The Donald Project is positioned as an upstream feed source for Energy Fuels' mine to magnet chain, so progress here affects the whole strategy.
Elemental Royalty (ELE)
Elemental Royalty closed on four of five royalty and streaming assets from funds managed by Orion Mine Finance and expanded its revolving credit facility to US$250 million, with an option to add another US$50 million. The package includes exposure to Ruby Hill, Granite Creek, Kouroussa, Homestake and La Negra.
This is a sizeable portfolio shift. Watch how management deploys the enlarged credit line and how quickly the new royalties begin contributing cash flow to the royalty business.
BlackBerry (BB)
BlackBerry is leaning into physical AI, with the CEO highlighting AI powered robots as a major opportunity for the QNX software unit. QNX already has a royalty backlog above $1.2b, and the tie up with Nvidia is opening channels in robotics and industrial automation beyond the core auto market.
The story to monitor is monetization. Keep an eye on how quickly that backlog converts into recognized QNX revenue and whether non automotive deals start to scale.
Top Movers
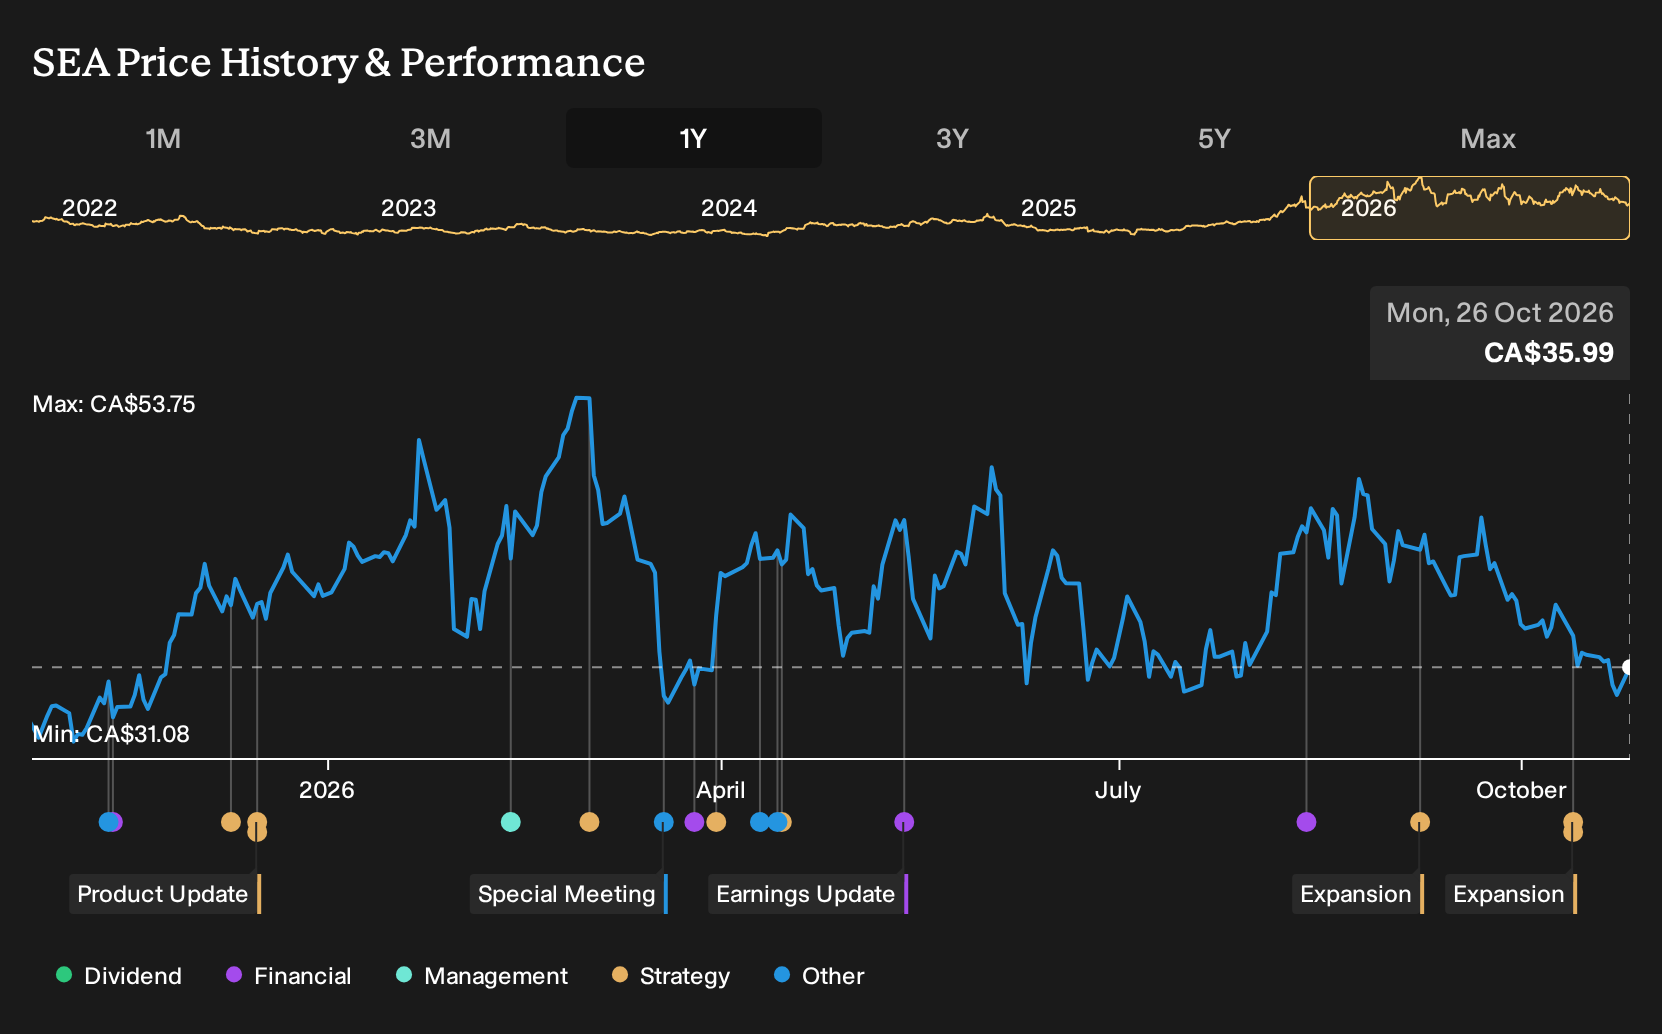
- Seabridge Gold (TSX:SEA) rose 5.36% after a BC Conservative landslide increased expectations for faster mining project permitting.
- Precision Drilling (TSX:PD) gained 5.09% after National Bank upgraded the stock to Outperform with a higher C$185 target.
- CAE (TSX:CAE) added 4.57% after agreeing to sell its Flightscape airline software unit to SITA for US$500 million.
Top Losers
- Extendicare (TSX:EXE) fell 2.20% after CIBC raised its price target to C$40 and reiterated an Outperformer rating.
- StorageVault Canada (TSX:SVI) declined 2.13% after CIBC and BMO both reduced their price targets on the stock.
- Parex Resources (TSX:PXT) fell 2.12% following a recent Outperform initiation from ATB Cormark with a C$35 price target.

On The Radar
For Canadian investors, the next stretch is all about central banks and a run of heavyweight domestic earnings that will feed directly into rate expectations and sector positioning.
- BoC Interest Rate Decision, Wed 28 Oct. The policy rate is expected to go from 2.25% to 2.5%, and any signal that borrowing costs could stay higher for longer would matter for Canadian banks, housing exposed stocks and the loonie.
- BoC Monetary Policy Report and Press Conference, Wed 28 Oct. Fresh projections on inflation and growth will shape how investors think about Canadian bond yields and could influence how rate sensitive areas like utilities, REITs and consumer lenders trade.
- Imperial Oil, Fri 30 Oct. Q3 results will put the focus on upstream cash generation and downstream margins, which feeds into how energy holders judge capital return potential across the Canadian oil and gas sector.
- Canadian National Railway, Fri 30 Oct. When the railway posts Q3 numbers before the open, freight volumes and revenue performance will give a direct read on Canadian trade flows and industrial activity.
- Canada GDP MoM, Fri 30 Oct. August GDP is forecast at 0.2% after a flat prior month and a softer print would tend to ease pressure on further tightening while a stronger one could support the Canadian dollar.
Sector & Industry Watch
Energy: Deal activity keeps sector busy
Energy has inched higher over the past week, with Oil and Gas moving in step as producers benefit from firm crude pricing and steady cash generation. A run of transactions, including Ovintiv buying Logan Energy and TopSpin partnering with Pine Cliff, shows buyers still willing to commit capital to Canadian fields.
The single lever to watch now is this week’s US crude inventory data, since any signal on tightness or surplus can quickly filter into Canadian producer sentiment and the loonie.
Materials: Miners slide as sentiment cools
Materials has retreated over the last month, and the slump has deepened in the past seven days, with Metals and Mining seeing even steeper weekly declines. Project headlines keep coming, from Seabridge Gold and Spanish Mountain Gold in BC to copper and tungsten updates abroad, yet recent share price weakness shows investors are cautious on funding needs and project risk.
The key checkpoint is the next batch of Canadian miner production and earnings updates, because any shift in cost guidance or timelines can reset how much portfolio risk investors want in this resource heavy group.
Real Estate: Rate sensitive rally pauses for BoC
Real Estate has pushed higher over the past week and posted a modest gain over the month, although 1 year performance still trails the broader CA Market. Higher debt costs remain an issue, since pricier loans can eat into REIT payouts and delay new builds, which matters if you rely on property holdings for income.
The sector’s main catalyst is Wednesday’s Bank of Canada interest rate decision, because any move toward the expected 2.5% policy setting or a different tone on future changes feeds directly into funding costs for landlords and developers.
Financials: Banks watch households and rate path
Financials has edged higher over the last week, with Banks slightly stronger and showing solid 1 year gains versus the CA Market. Recent commentary from Canadian lenders highlights both resilient household credit and rising mortgage arrears at renewal, so investors are weighing stable income streams against pockets of stress.
The BoC Monetary Policy Report that lands with Wednesday’s rate call is the key event, since its signals on future borrowing costs will shape expectations for loan growth, credit losses, and savings demand across major Canadian Financials.
Tech: Sector mixed as chips stay under pressure
Tech has eased back over the past week, and both year to date and 1 year returns sit below the broader CA Market, with Semiconductors showing especially sharp declines. Company news is more upbeat than the chart suggests, with BlackBerry talking up QNX opportunities in physical AI and Celestica reporting strong Q3 results and a higher outlook.
The catalyst to keep on the radar is the upcoming Canadian Tech earnings run, since fresh commentary on AI, automation, and IT budgets will help investors judge whether recent Tech weakness still lines up with the underlying business picture.
Identify The Next Market Leaders
With the Bank of Canada expected to lift its policy rate to 2.5% and rate sensitive sectors back in focus, start with this list of 8 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com