
MedinCell (ENXTPA:MEDCL) Financing Reset Puts Its Undervalued Narrative Back In Focus
MedinCell (ENXTPA:MEDCL) reshaped its funding mix after securing €41.8 million in non dilutive bank financing since July 2026, repaying half of its European Investment Bank loan and extending debt maturities to 2031.
Recent trading suggests investors are cautiously re-rating MedinCell. The 1 month share price return of 14.25% and 6.39% year to date gain contrast with a 1 year total shareholder return that declined 27.59%, even though the 3 year total shareholder return is very large at about 4.7x.
Spot opportunities in other funded-but-still-executing stories by scanning the hand picked 610 high quality undiscovered gems that share MedinCell’s mix of runway, product pipelines, and market skepticism.So is MedinCell’s latest jump a clear indication of improving fundamentals after the funding reshape, or primarily a shift in sentiment that the valuation section now needs to examine?
Most Popular Narrative: 25% Undervalued
MedinCell’s most followed narrative framework points to a fair value of about €35.07 per share compared with the latest close at €26.30. That gap rests on aggressive earnings forecasts, but it is anchored in specific product and partnership milestones rather than vague optimism.
Recent tripling of revenues driven by successful commercialization of UZEDY and the strong ongoing ramp in prescriptions suggest that MedinCell's growth assumptions remain underappreciated, with continued expansion into new indications (like bipolar disorder) likely to further enhance royalty revenue streams and accelerate top-line growth.
MedinCell's demonstrated ability to secure large-scale partnerships (recent AbbVie deal, high ongoing partner interest) and expansion into emerging global markets for long-acting injectable therapies position it to capture rising demand fueled by broader healthcare access and aging populations, directly supporting future revenue expansion potential.
See why 6 investors see MedinCell as 25% undervalued.
Result: Fair Value of €35.07 (UNDERVALUED)
Still, MedinCell’s heavy dependence on UZEDY and Olanzapine LAI, along with its need for smooth regulatory approvals, could quickly challenge that 25% undervalued narrative.
Find out about the key risks to this MedinCell narrative.
Another View: MedinCell Looks Expensive On Sales
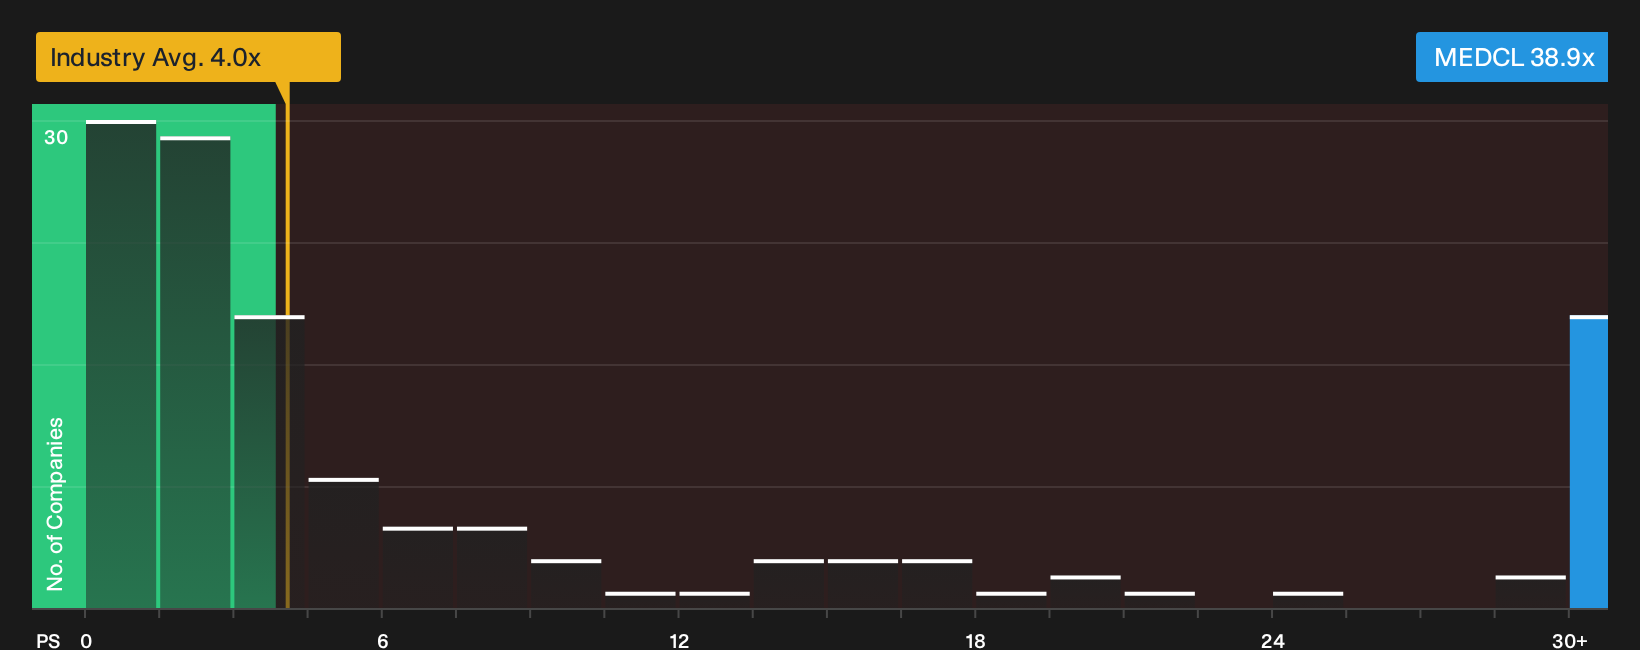
The popular MedinCell narrative leans on future earnings, yet today the stock trades on a P/S of 38.9x. The fair ratio is 8.6x, and peers cluster nearer 4.7x in France and 4.1x across Europe. That kind of gap can signal rich expectations. Is that a risk you are comfortable with, or a premium you think the business can grow into?
For a closer look at how this price compares to fundamentals, review the full valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around MedinCell can make the story feel unresolved, so move quickly, test the assumptions against the data, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more MedinCell style investment ideas?
Do not stop with MedinCell. Put fresh ideas on your radar now so you are not looking back later wishing you had acted sooner.
- Explore potential opportunities by scanning a curated pool of ideas through the 195 high quality undervalued stocks.
- Prioritise resilience and focus on companies highlighted in the 223 resilient stocks with low risk scores.
- Balance growth ambitions with financial strength by filtering for businesses on the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com