
Is CarMax (KMX) Cheap Following Buyback Plans And Fed Rate Pause Hopes?
CarMax (KMX) is back in focus after management signaled a return to share repurchases, while investors weigh how a potential pause in Federal Reserve rate hikes could influence auto financing costs and used car demand.
CarMax shares have been choppy, with a 1-day share price return of 2.08% and a 7-day gain of 1.88% following a 30-day decline of 8.02% and a 90-day drop of 10.63%. The year-to-date share price return sits at 33.93%, and the 1-year total shareholder return is 16.73%, compared with much weaker 3- and 5-year total shareholder returns. This suggests that recent momentum has improved from a softer long-term record as investors respond to buyback plans, the latest leadership appointment in the finance function, and shifting expectations for funding costs.
Scan opportunities that echo CarMax's rate sensitivity and balance-sheet focus by zeroing in on our hand picked list of solid balance sheet and fundamentals (24 results) for ideas beyond this used car retailer.
CarMax appears to be a solid used car platform with its own finance arm and renewed buyback plans. However, the share price rebound raises a sharper question: is this business strength already fully reflected in the valuation or not?
Most Popular Narrative: 2.7% Undervalued
CarMax closed at $52.62 against a narrative fair value of $54.09, a small gap that still puts management language under the microscope.
Beyond that near term, our goal is to self-fund strong competitive positioning through more efficient operations rather than lowering GPU. Mayor-Mora said it, and Barr’s prepared remarks had made the same promise: price competitiveness “through more efficient operations, rather than a combination of lower GPUs and efficiency gains, as we are doing this year.”
See why 1 investors see CarMax as 3% undervalued.
According to LunaRodas, the narrative hinges on whether that promise to fund lower prices through cost efficiencies survives intact as the calendar moves toward fiscal 2028 and beyond. The latest call language softens the pledge, which matters when earnings are forecast to grow 21.68% per year while reported net margins sit at 1% on $29.5b of revenue.
The same narrative flags tension between a modest 0.6% annual revenue growth forecast and much faster expected profit growth of 21.7% per year. That mix implies a larger share of the story rests on margin repair, SG&A discipline, and the CarMax Auto Finance contribution rather than on outsized volume expansion.
Leverage and funding also sit in the frame. Debt is described as not well covered by operating cash flow and 100% of liabilities come from higher risk sources of funding, which puts more weight on how consistently the business can convert sales into cash while running a buyback and owning a finance arm.
Layer in the valuation signals and the gap tightens further. CarMax trades at a P/E of 25.5x, which is expensive compared with both the US Specialty Retail average of 17.4x and a peer average of 11.6x, and above an estimated fair P/E of 21.3x that the market could move toward if sentiment cools.
Result: Fair Value of $54.09 (ABOUT RIGHT)
Explore the SWS fair ratio for CarMax.Still, the CarMax narrative could be knocked off course if margin repair proves harder than management language implies, or if leverage and funding costs stay tight while buybacks resume.
Find out about the key risks to this CarMax narrative.
Another View: What The P/E Is Really Saying About CarMax
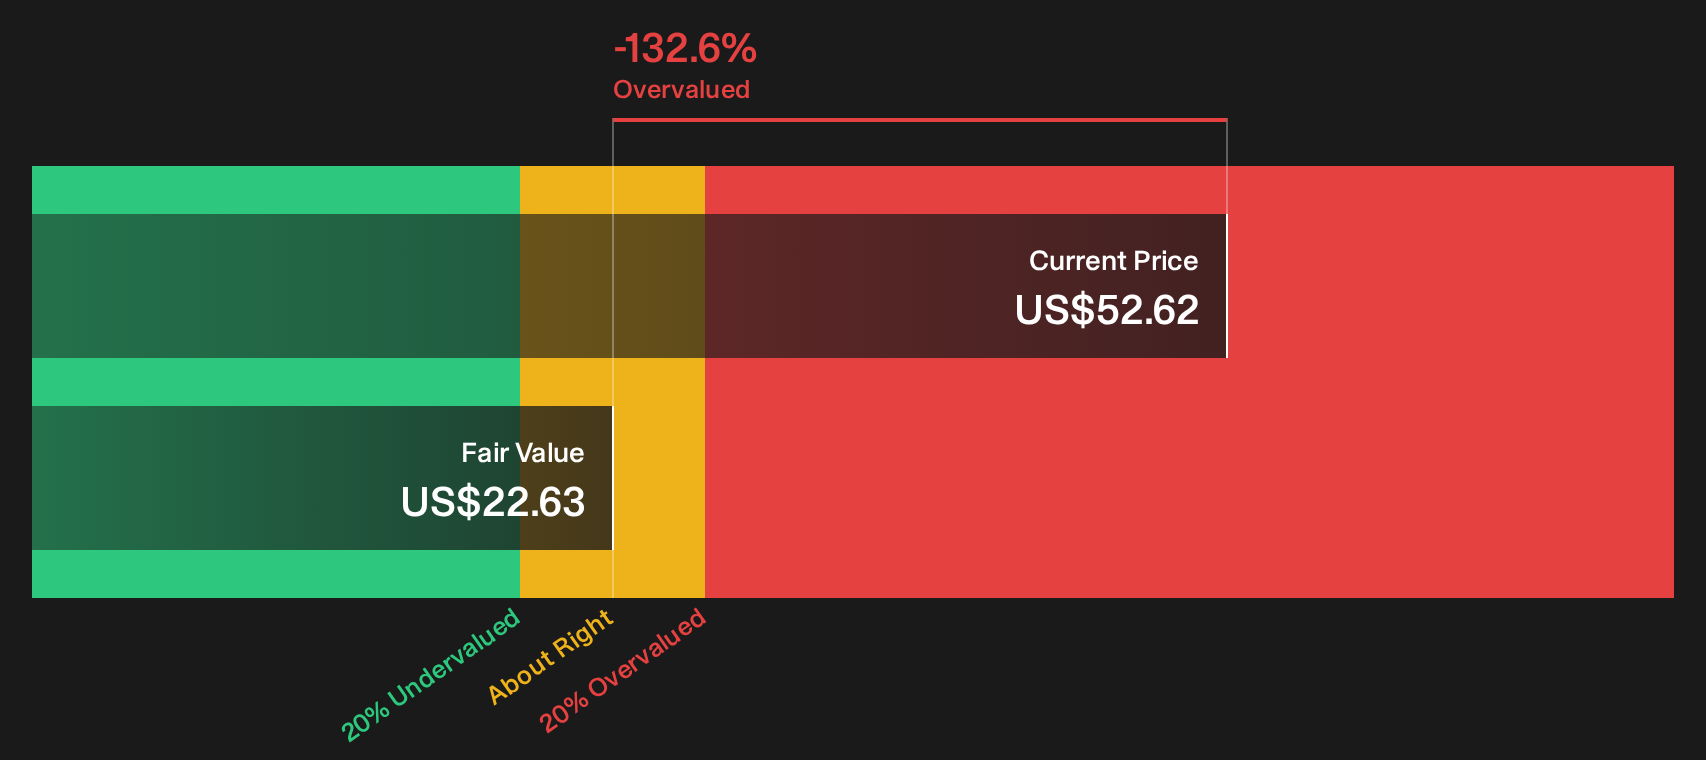
The SWS DCF model flags CarMax very differently. While the narrative fair value sits at $54.09, the DCF output estimates future cash flows at $22.63 per share, which implies the current $52.62 price is rich rather than slightly cheap. That gap raises a simple question for you: Which story feels more robust when the cycle turns?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on CarMax can cut both ways, which is why it pays to move quickly, pull up the full data set, and stress test the story for yourself with the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond CarMax?
If CarMax has sharpened your focus on quality and pricing power, do not stop here. Broaden your watchlist now so the next opportunity does not slip past.
- Target resilient cash generators that still look practical on valuation by running your filters through 29 high quality undervalued stocks.
- Strengthen your income stream with companies built around robust payouts by scanning 5 dividend fortresses.
- Dial down portfolio risk while keeping upside on the table when you sort ideas using 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com