
Bank of China (SEHK:3988) Completes RMB 50b Bond Issue As Valuation Questions Linger
Bank of China (SEHK:3988) has just completed a RMB 50b issue of write down tier 2 capital bonds at a fixed 1.74% coupon. This is a sizeable funding move aimed at reinforcing regulatory capital.
At a share price of HK$6.06, Bank of China has paired a 33.77% year to date share price return with a 44.00% total shareholder return over 12 months, while the 167.00% three year and 214.71% five year total shareholder returns point to sustained momentum rather than a short term bounce.
Spot other banks and financials with similar balance sheet moves by scanning our curated list of solid balance sheet and fundamentals (207 results) alongside Bank of China after this bond issuance.After a 167.00% three year and 214.71% five year total return, plus fresh tier 2 capital in place, is most of Bank of China’s upside already captured, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 6.5% Overvalued
According to the most followed narrative, Bank of China is priced modestly above its implied worth, with a fair value of HK$5.69 against the HK$6.06 last close. This puts recent bond funding and strong past returns against a slightly stretched tag.
Bank of China Limited (“BOC”) is one of China’s “Big Four” state-owned commercial banks, with a leading position in global banking services and cross-border finance.
The investment thesis centers on:
- Strong sovereign backing
- Global footprint
- Diversified revenue mix
See why 6 investors see Bank of China as 7% overvalued.
Result: Fair Value of HK$5.69 (OVERVALUED)
Still, Bank of China’s narrative could be tested if credit quality weakens or if policy driven lending weighs on profitability and investor confidence.
Find out about the key risks to this Bank of China narrative.
Another View On Bank of China’s Valuation
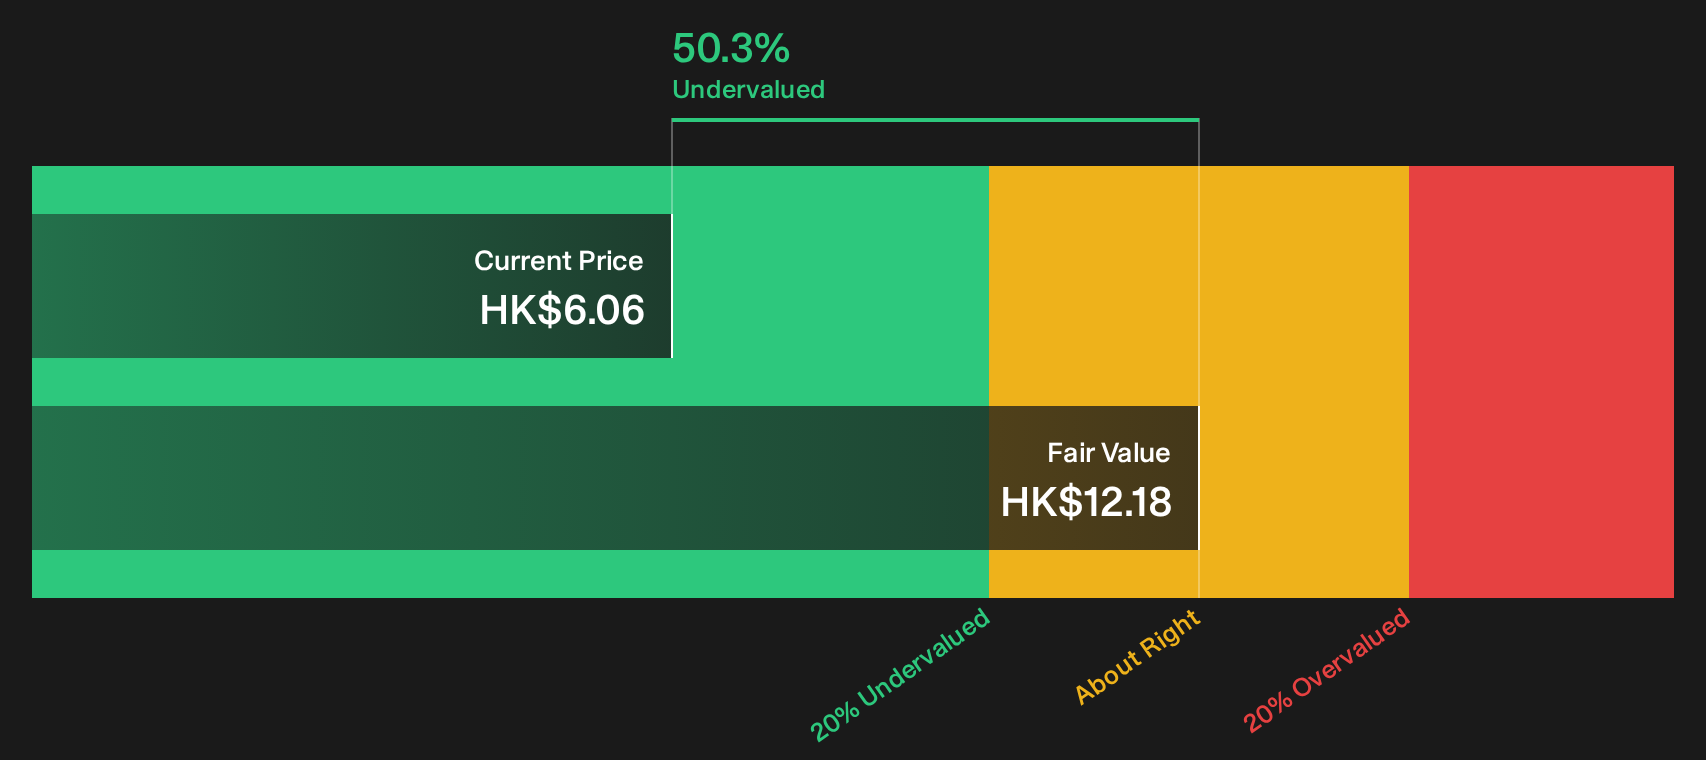
The first narrative suggests that Bank of China is about 6.5% overvalued at HK$6.06 compared with a fair value of HK$5.69. Our DCF model presents a different view, with a fair value estimate of HK$12.18 and the shares trading at roughly a 50% discount. Which story appears more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of China for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Bank of China’s value can be useful if they push you to check the numbers directly and move before sentiment shifts. To see which positives investors are focusing on right now, review the 4 key rewards.
Looking for more investment ideas beyond Bank of China?
If you stop with Bank of China, you might miss other opportunities where balance sheets, valuations, and dividends line up with what you want your portfolio to do.
- Target more resilient portfolio anchors by scanning companies with lower risk profiles through the 223 resilient stocks with low risk scores.
- Hunt for potential value gaps by checking businesses that appear mispriced on quality and fundamentals using the 195 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies offering stronger yield profiles and payout histories in the 224 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com