
How Investors Are Reacting To CMS Energy (CMS) Capital Plan Updates
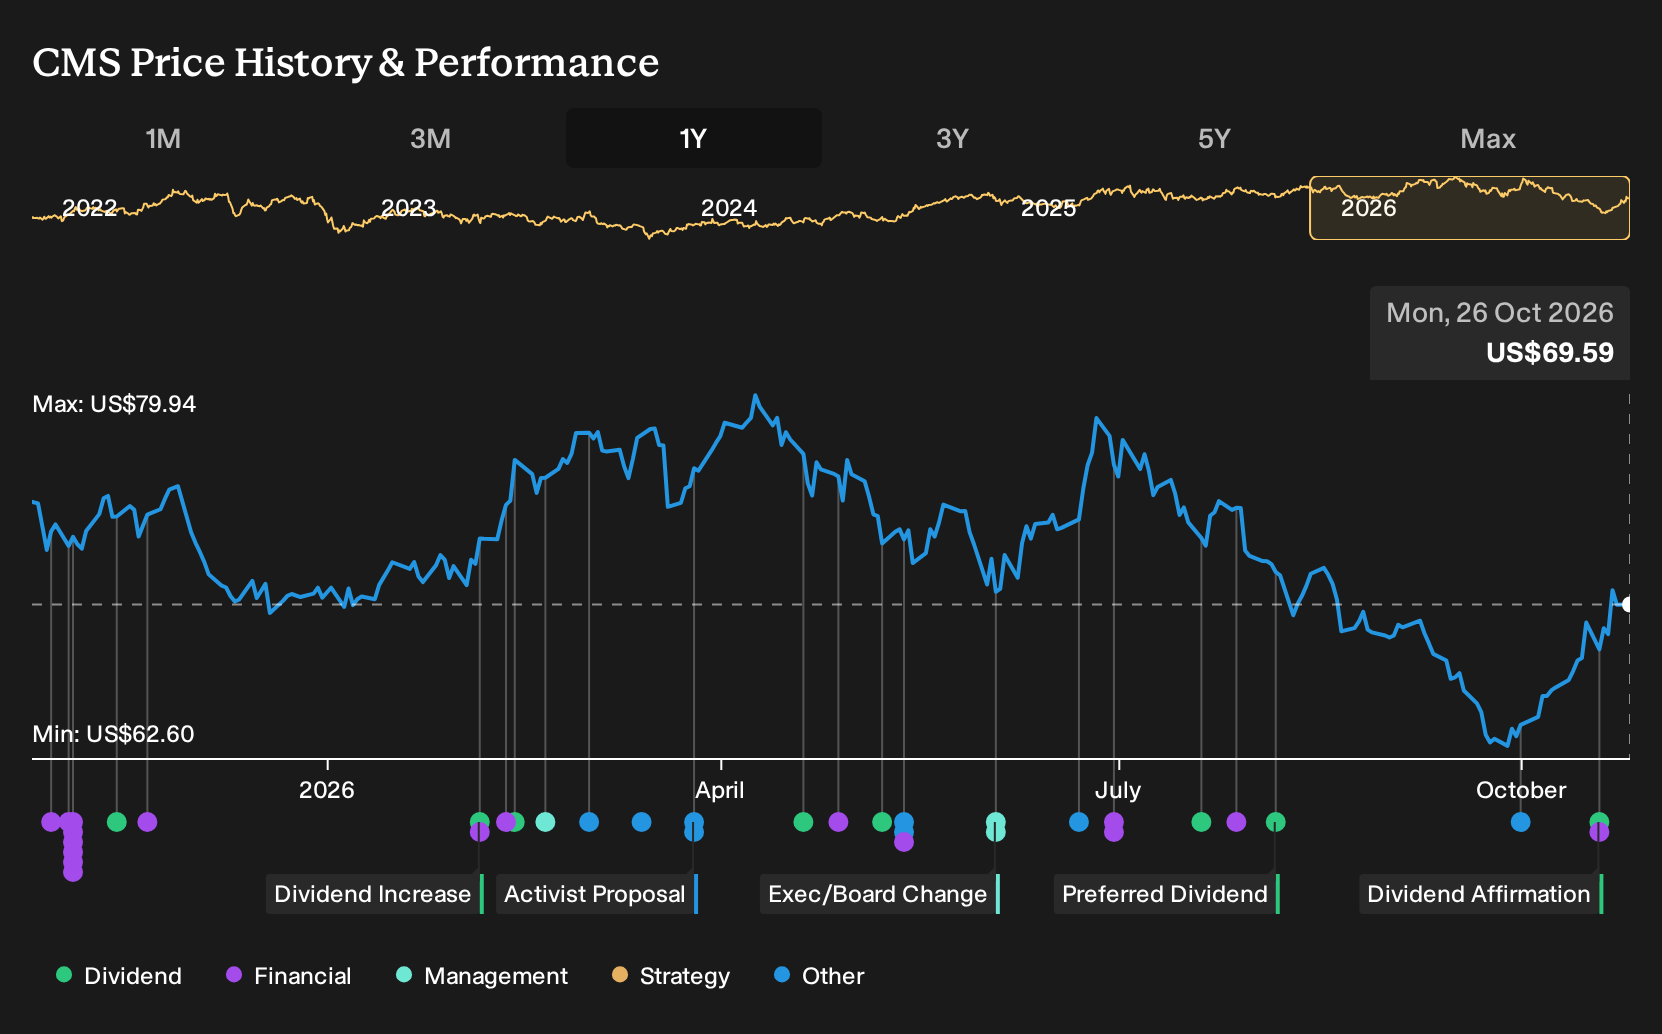
- CMS Energy confirmed a quarterly dividend of $0.57 per share and registered up to 2,000,000 common shares for a dividend reinvestment plan, aligning cash payouts with a potential equity funding channel.
- The combination of a maintained cash dividend and fresh shelf capacity under a reinvestment program highlights how CMS Energy is seeking to balance shareholder returns with future capital needs tied to its Michigan utility operations.
- This article examines how CMS Energy's dividend affirmation and reinvestment share registration influence the investment narrative around its utility focus.
Compare CMS Energy's income-focused profile and grid investment push with a curated set of regulated utilities and infrastructure stocks in our 42 power grid technology and infrastructure stocks for potential dividend and capital deployment ideas.
CMS Energy Investment Narrative Recap
To own CMS Energy, you need to be comfortable with a Michigan focused utility leaning on a roughly $24b grid and clean energy investment plan and a 20 year resource roadmap. The near term story still hinges on smooth execution of that spending and constructive regulatory decisions that let the utility earn on those projects while keeping customer bills manageable.
The biggest swing factor right now is how regulators treat cost recovery for that capital program and for unplanned storm spending, which has already pressured operations and maintenance this year. The latest dividend and reinvestment news does not materially change those near term operational and regulatory catalysts or the core funding risks.
The most relevant announcement for this setup is the shelf registration for up to 2,000,000 CMS Energy common shares tied to a dividend reinvestment plan. That filing gives the business a defined way to raise equity as it works through the NorthStar restructuring, the planned $24b utility build out, and the shift away from nonutility renewable development.
For you, the question is how that potential equity issuance might interact with an income profile where the $0.57 quarterly dividend and a 3.28% yield are not well covered by free cash flow today. Layer in interest costs that are flagged as not well covered by earnings, and this reinvestment capacity becomes part of the near term watch list around funding mix, execution on the grid program, and any future rate case outcomes.
CMS Energy's current analyst narrative points to revenues of $10.2b and earnings of $1.5b by 2029, based on an assumed 4.9% yearly revenue growth rate and a move from $1.0b of earnings today to that 2029 consensus. This represents a $0.5b increase from current earnings.
Uncover why CMS Energy's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$56.18 and about US$76.92, so retail opinions on CMS Energy span a wide price band. Those views sit alongside earnings, regulation, and funding risks on one side, and the US$24b utility plan and data center load agreements on the other. That gap is a reminder that investor opinions can differ sharply, so it is worth testing CMS Energy against several contrasting viewpoints before leaning on any single fair value line.
Explore 2 other CMS Energy fair value estimates, including one that suggests as much as 19% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CMS Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CMS Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CMS Energy's overall financial health at a glance.
Looking For More Ideas Beyond CMS Energy?
If the CMS Energy story has you thinking about how to balance income, balance sheet strength, and risk, it can help to compare it with a wider field of opportunities first. The Simply Wall St Screener lets you filter for very specific traits so you can build a watchlist that actually matches your goals instead of a generic utility basket.
- If capital preservation sits near the top of your priority list, start with companies that screen as relatively robust on risk metrics through 30 resilient stocks with low risk scores.
- For investors who care about resilient finances behind any dividend or buyback, focus on businesses that show up in the list of solid balance sheet and fundamentals (24 results).
- Those looking for ideas with strong fundamentals that are not widely followed yet can scan the 21 high quality undiscovered gems and see which stories may warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com