
Radware (RDWR) Launches AI Security Tool As Valuation Questions Grow
AI security launch puts Radware stock in focus
Radware (RDWR) is drawing fresh attention after launching its Model Context Protocol Server Protection product, a new offering aimed at securing MCP servers as companies expand AI agent access to core business systems.
That AI security launch lands at a time when Radware’s momentum has been picking up, with a 1-day share price return of 3.96% capping a 7-day share price gain of 13.13% and a year-to-date share price return of 35.83%. At the same time, the 3-year total shareholder return of 116.34% contrasts with a 5-year total shareholder return that is down 6.97%, pointing to strong recent gains after a weaker stretch for longer term holders.
Scan beyond Radware and see how other security and AI infrastructure players are lining up in our hand-picked list of 55 AI infrastructure stocks.
Bulls see Radware’s AI security push and recent share price strength as confirmation of a rerating in progress. Bears point to a zero value score and past 5-year drag. Which case do the current valuation signals lean toward?
Price-to-earnings of 78.7x: Is it justified?
Valuation flags on Radware are hard to miss, with the stock trading on a P/E of 78.7x while the last close sits at $32.30 and analysts as a group see a lower target price of $30.50.
The P/E ratio compares what investors pay today for each dollar of current earnings. For a cyber security and application delivery specialist like Radware, such a high multiple usually signals that the market is baking in meaningful profit expansion or a sustained improvement in profitability, even if headline revenue forecasts of 7.9% a year are not especially fast.
Context matters here. Radware shows earnings growth of 16% per year over the past 5 years and 21.9% over the past year, with net profit margins at 5.4% versus 4.9% a year earlier. At the same time, return on equity is 4.8%, which is classified as low, there are large one-off items affecting reported earnings, and the SWS DCF model estimates a future cash flow value of $19.63 per share compared with the current $32.30 trading level. That creates a wide gap that suggests the current earnings multiple leaves limited room for disappointment if growth or profitability cools.
The comparison to peers is also sharp. Radware’s 78.7x P/E is described as expensive both against the peer average of 35.8x and against the broader US Software industry on 32.9x. In practice, this means investors in this stock are paying more than double the sector average earnings multiple, while relying on profit trends and AI security momentum to justify a premium that is already substantial.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 78.7x (OVERVALUED)
Still, any wobble in Radware’s AI security traction or a reset in rich valuation assumptions could quickly challenge the recent rerating story.
Find out about the key risks to this Radware narrative.
Another view on Radware’s valuation
The earnings multiple presents Radware as expensive, yet the SWS DCF model approaches the question from the cash flow side and reaches a different conclusion. On that basis, estimated future cash flows support a value of $19.63 per share, well below the current $32.30 level.
That kind of gap suggests the market price is relying heavily on optimism around AI security, while the cash flow analysis reflects a more cautious stance. Which perspective do you rely on when the narrative and the spreadsheet point in opposite directions?
Look into how the SWS DCF model arrives at its fair value.
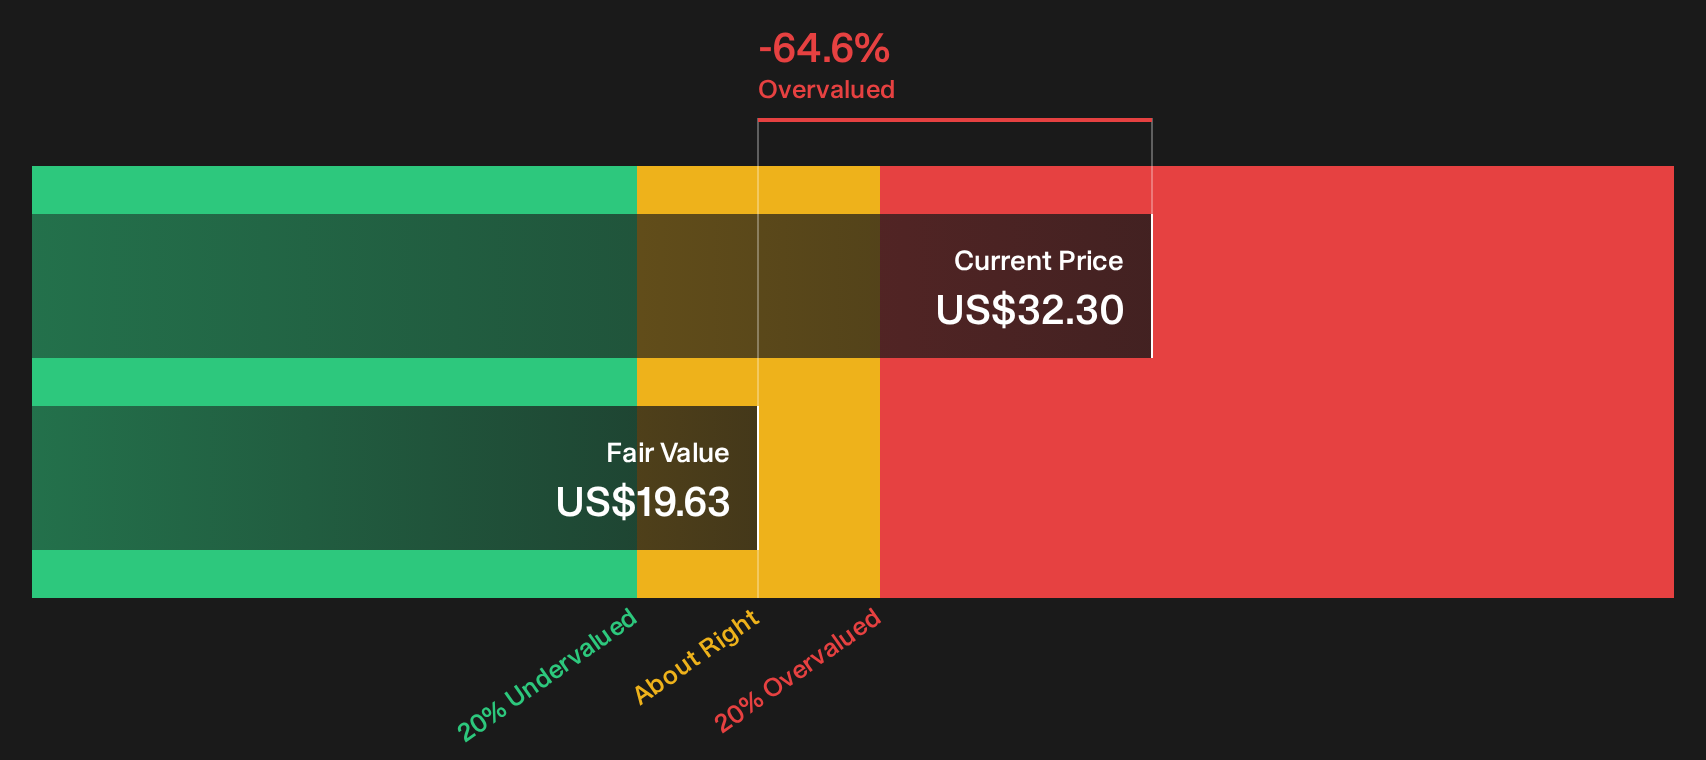
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Radware for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Radware’s valuation story so far. If you want your view to be based on evidence rather than headlines, move quickly through the data and weigh both sides using the 1 key reward and 2 important warning signs.
Looking for more Radware-sized opportunities?
If Radware has your attention, do not stop at one idea. Use the Simply Wall St screener to quickly surface fresh candidates that match your investing style.
- Target quality at a discount by scanning a hand picked group of 29 high quality undervalued stocks that pair stronger fundamentals with cheaper valuations.
- Prioritise resilience by searching through 30 resilient stocks with low risk scores that score well on stability and risk checks before you commit fresh capital.
- Hunt for underfollowed stories by reviewing 21 high quality undiscovered gems that combine solid business traits with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com