
Earnings Guidance Could Be A Game Changer For Halliburton (HAL)
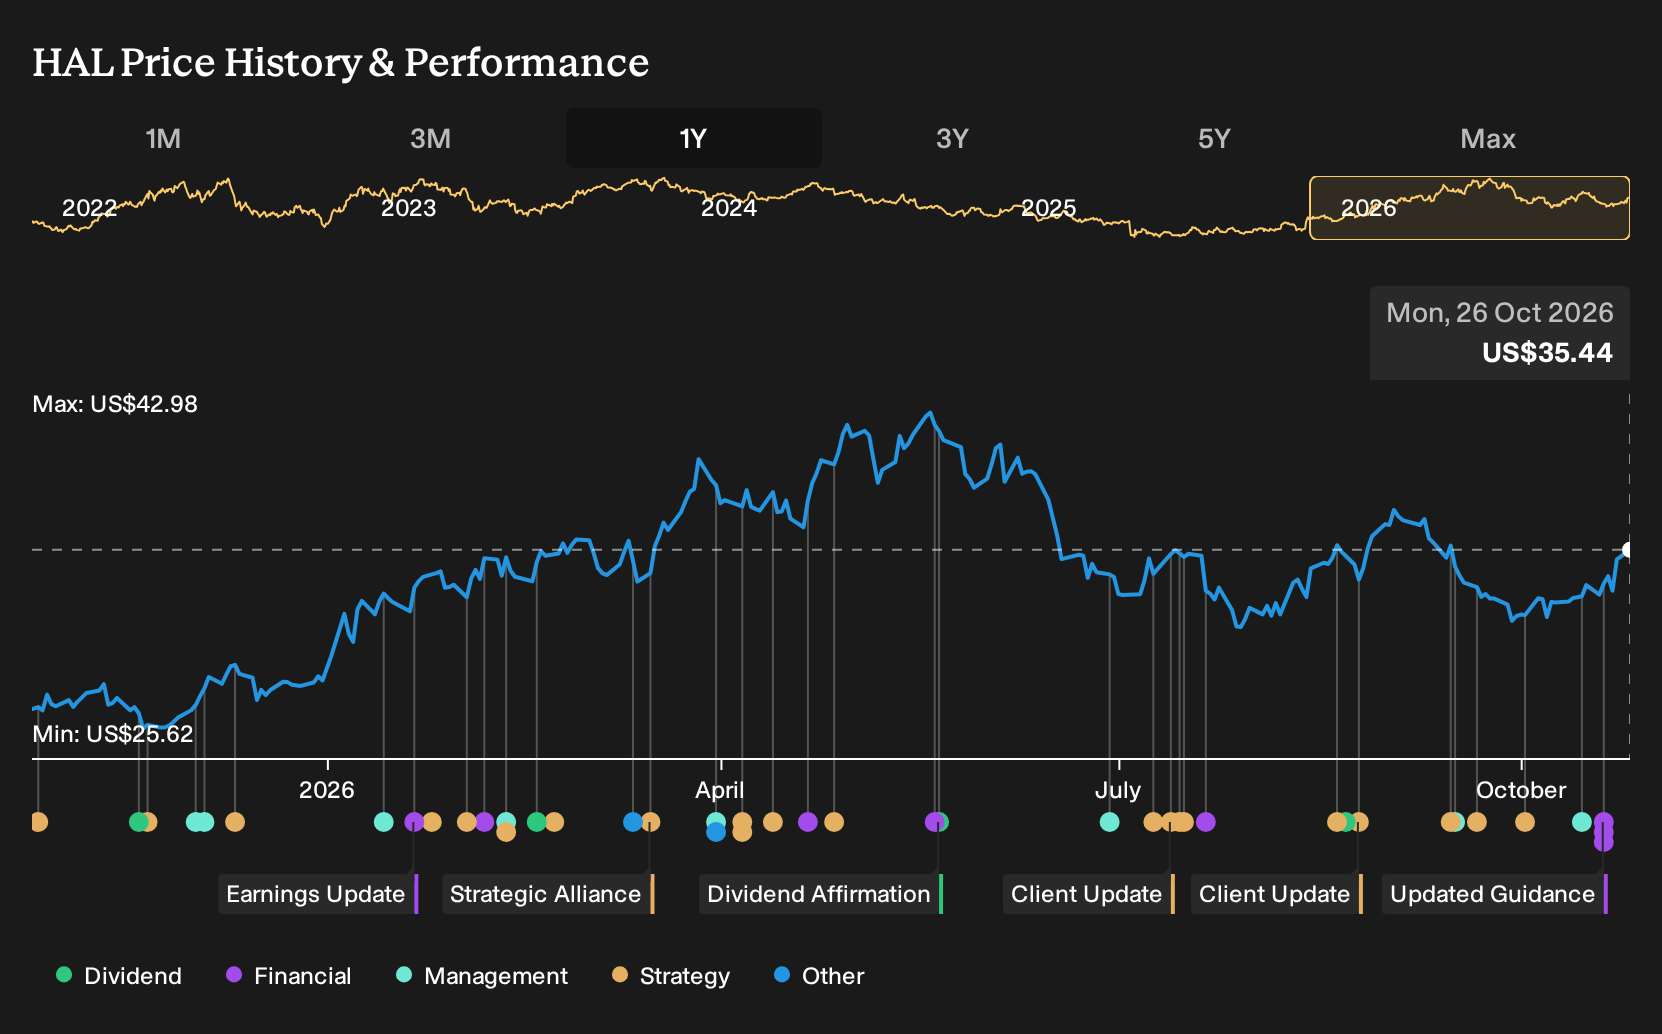
- Halliburton reported third quarter 2026 results that showed higher revenue and net income compared with a year earlier, and issued fourth quarter guidance calling for roughly flat revenue of about US$5.7b and a modestly higher operating margin, with earnings per share projected at US$0.62 to US$0.64.
- The group paired this detailed near term guidance with an early 2027 outlook that points to mid single digit revenue expansion and a planned operating margin step up to about 15%, signaling a clear focus on profitability and execution in its core oilfield services business.
- We will now explore how Halliburton's margin focused guidance and earnings progress could reshape the existing investment narrative around the stock.
Scan peer opportunities by reviewing the hand picked 29 high quality undervalued stocks that also present disciplined margin stories similar to Halliburton's latest guidance.
Halliburton Investment Narrative Recap
To own Halliburton, you need to be comfortable with a service provider that is leaning hard into efficiency and pricing discipline rather than chasing volume. The near term hinge point is whether management can turn roughly flat Q4 2026 revenue of about US$5.7b into better profitability through a 70 basis point margin lift and EPS of US$0.62 to US$0.64. That is an execution test, not a growth story.
The biggest operational swing factor right now is how resilient activity stays in Halliburton’s key regions as decarbonization pressures, conflicts and logistics costs keep shifting project timing. The early 2027 outlook for mid single digit revenue expansion and about 15% margins points to a margin focused setup. If those conditions change materially, that roadmap could look more ambitious.
The most relevant update for this catalyst discussion is the third quarter 2026 earnings print. Halliburton reported Q3 revenue of US$5,703m compared with US$5,600m a year earlier and net income of US$417m versus US$18m. Diluted EPS from continuing operations was US$0.50 compared with US$0.02, which provides a clearer view of recent profitability improvement.
That step up in earnings, alongside nine month net income of US$1,412m compared with US$694m last year, frames the new margin targets as an attempt to build on existing progress rather than start from scratch. For you, the question is whether that run rate can hold against risks such as high debt, unstable dividends and potential demand pressure from decarbonization and regional disruptions.
Halliburton's current analyst narrative points to forecast revenue of US$25.1b and earnings of US$2.7b by 2029, based on revenue growth of 3.9% per year, compared with earnings of about US$1.6b today. This implies an earnings increase of roughly US$1.1b over that period.
Uncover why Halliburton's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The bearish narrative for Halliburton leans heavily on Middle East conflict risk. The lowest ranked analysts were working off slower top line assumptions of about US$23.2b of revenue and roughly US$2.8b of earnings by 2029. You are effectively comparing that caution to fresh margin-focused guidance that could prompt those views to shift.
Explore 4 other Halliburton fair value estimates, including one that suggests it could be worth just $34.03.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Halliburton research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Halliburton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halliburton's overall financial health at a glance.
Looking for more Halliburton sized investment ideas?
If the Halliburton story has you thinking about risk, resilience and where to put fresh capital to work, the Simply Wall St Screener can help you cast a wider net without losing that focus on quality.
- For investors who care most about balance sheet strength and consistent fundamentals, the list of solid balance sheet and fundamentals (24 results) can surface candidates that may handle tougher conditions more comfortably.
- If capital preservation and smoother return profiles matter to you, the 30 resilient stocks with low risk scores can help narrow the field to businesses with more muted risk scores.
- When you want a fresh source of ideas beyond the usual large caps, the 21 high quality undiscovered gems can highlight lesser known stocks with stronger underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com