
Learn Why The Bull Case For BWX Technologies (BWXT) Could Change Following Earnings Beat Expectations
- BWX Technologies is heading into its September 2026 quarter with the market expecting earnings of $1.19 per share on higher revenue than the prior year, supported by forecast year over year earnings growth of 19%.
- The key twist is that a modestly positive Earnings ESP of 0.22% and recent upward estimate revisions suggest investors are focused on whether BWX Technologies can translate its large nuclear backlog into stronger quarterly profitability.
- Next, the focus turns to how BWX Technologies' expected year over year earnings uplift might shape the longer term investment narrative.
Scan nuclear-focused peers that could also surprise the market on earnings using our curated list of 16 nuclear energy infrastructure stocks for ideas beyond BWX Technologies.
BWX Technologies Investment Narrative Recap
To own BWX Technologies, you need to believe the nuclear backlog and long term U.S. government work can keep translating into resilient earnings, even as programs move through different build phases. The current focus is on whether higher September 2026 EPS, if achieved, comes from better execution on that US$8.4b backlog rather than one off items.
The key short term catalyst is margin progress in both Government and Commercial Operations as big contracts ramp and capacity investments remain high. The main operational risk is that heavy reliance on defense funded projects and a high debt load limit flexibility if budgets, schedules or cost inflation pressure returns.
The most relevant recent data point for this earnings setup is the record backlog, supported by a 1.7x trailing 12 month book to bill ratio and roughly nine quarters of revenue coverage. That contract base is what gives this quarter its importance, because investors are watching how quickly awarded work turns into profit and cash generation.
Large multi year special materials awards, such as the US$1.63b high purity depleted uranium contract and the US$1.5b Defense Fuels Enrichment program, frame the catalyst and risk on timing. Strong reported EPS would suggest BWX Technologies is converting that work efficiently, while any margin pressure would highlight how sensitive the story is to execution, cost control and future reinvestment needs.
BWX Technologies' current earnings sit at $355.2 million, with analyst consensus pointing to $536.6 million and revenue of $4.8 billion by 2029. That profile assumes revenue growth of 10.7% per year and an earnings increase of about 51% from today's level to the 2029 forecast.
Uncover why BWX Technologies' fair value indicates a 60% potential upside to its current price that could narrow quickly.
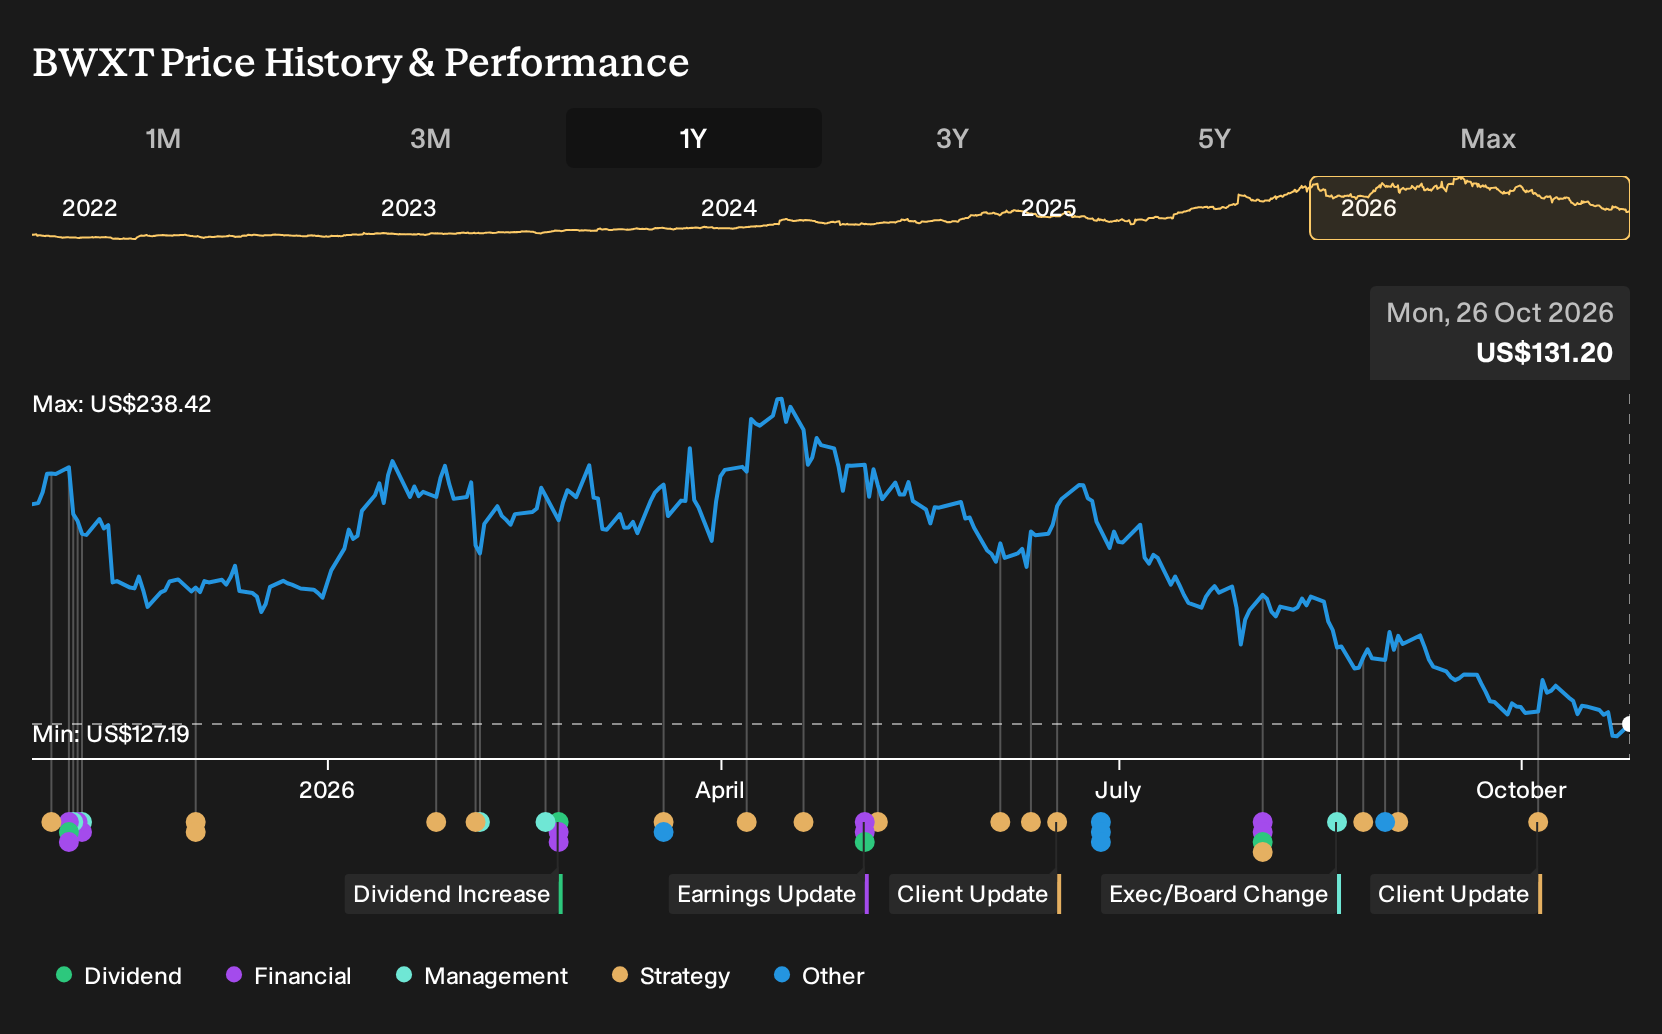
Exploring Other Perspectives
One alternate view on BWX Technologies leans heavily on capital spending risk. The most cautious analysts were working off roughly US$4.5b of 2029 revenue and about US$520.5 million of earnings, well below the higher forecasts. Those estimates came before this earnings setup, so you may see those narratives shift as new information lands.
Explore 5 other BWX Technologies fair value estimates, including one that suggests it could be worth just $135.33.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your BWX Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BWX Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BWX Technologies' overall financial health at a glance.
Looking for more investment ideas beyond BWX Technologies?
Once you have formed a view on BWX Technologies, it can help to benchmark that thinking against other opportunities using the Simply Wall St Screener.
- For investors hunting for mispriced quality, you can start with companies that pair solid fundamentals with attractive valuations by reviewing the 29 high quality undervalued stocks.
- If your priority is capital preservation and steadier profiles, you can filter for resilient businesses using the 30 resilient stocks with low risk scores as a jumping-off point.
- When you want balance sheets that can better absorb shocks and fund future projects, you can narrow the field with a curated list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com