
Fermi (FRMI) Stock Looks About Right After Its 89% Fall
Fermi has seen its share price fall heavily over the past year, which puts a spotlight on whether the market is now valuing the business in line with what its balance sheet can support. With the stock under pressure and book value in focus, the key issue is how much of the company’s future potential around its grid projects is already reflected in today’s price.
- The share price has declined 89.3% over the past year, which raises a direct question about how much equity value investors are still willing to assign relative to the company’s underlying net assets.
- Management’s recent letter on financing Project Matador highlights a plan to lean on project-level debt and outside capital, which can influence how much of the grid platform’s economic value ultimately sits on Fermi’s own balance sheet versus external investors.
- Your read on Fermi is one view; the desks covering it have another. See what analysts think Fermi's shares could be worth.
For investors, the debate is whether Fermi’s current share price around US$2.54 is sensibly aligned with its book value when compared with the industry average.
If you are weighing whether Fermi’s book-value trade off still appeals after this drawdown, it can help to compare it with other companies in our 29 high quality undervalued stocks for context.
Does Fermi Look Fairly Valued on Book Value?
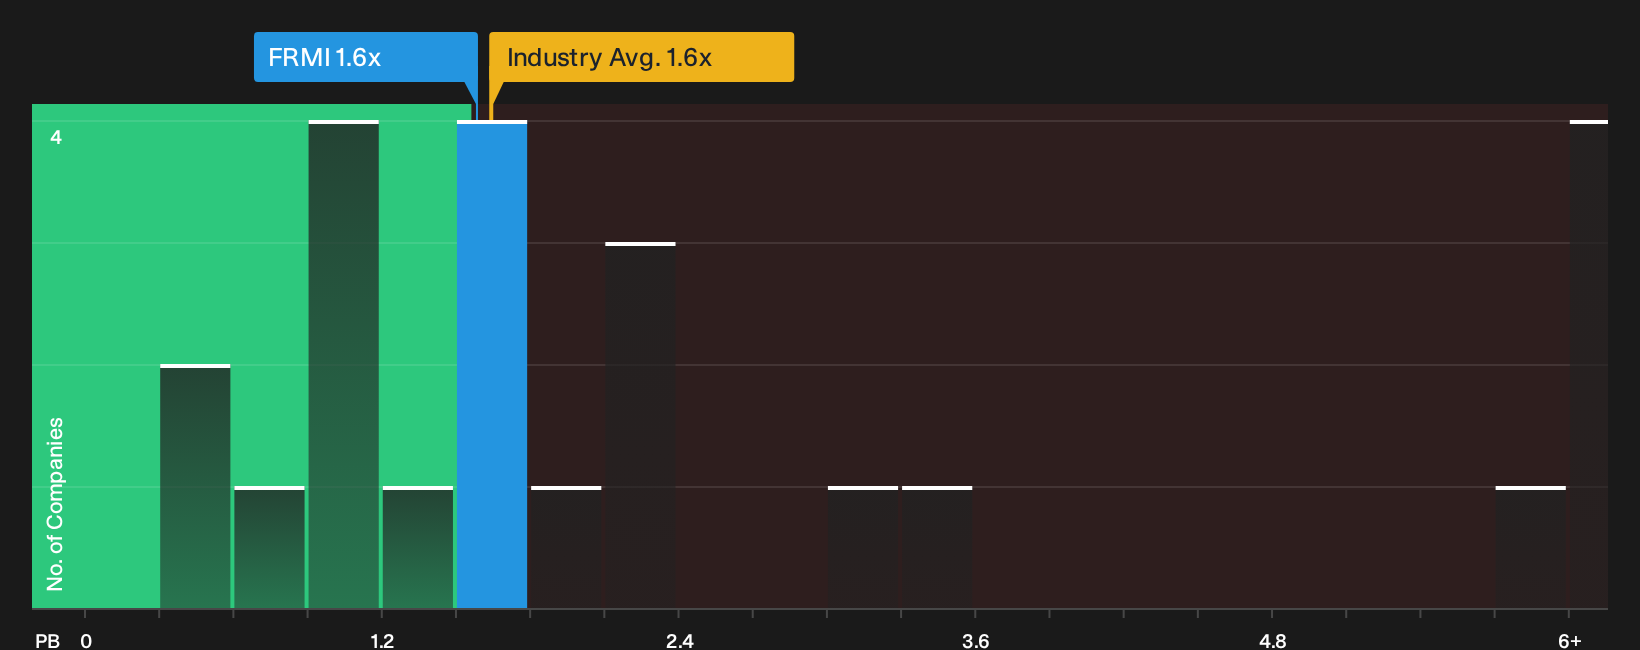
P/B suits Fermi because investors are weighing it as an asset backed grid platform rather than on near term earnings. On this measure, the stock trades at around 1.6x book value, close to the Specialized REITs sector average of about 1.6x and below the peer group at roughly 3.1x. That points to a valuation that is about right against the broader industry, even if more growth focused peers carry richer tags.
Because management is steering new grid projects like Project Matador toward project level debt and external capital, equity holders are effectively paying a near sector standard multiple for a balance sheet that may stay relatively asset light. Despite that funding model and the recent shareholder letter outlining it, the market is not assigning a clear premium or discount on P/B compared with the typical Specialized REIT. Explore the numbers behind Fermi's P/B valuation.
The Fermi Narrative: What Would Justify Today's Price?
Fermi’s valuation puzzle points straight to Simply Wall St Narratives on the Community page. These Narratives set out in plain terms what kind of future for grid projects, earnings and margins would need to play out for today’s share price to look materially higher or lower. Instead of a single ratio or model output, Narratives unpack the business future that number relies on so you can watch over time whether those expectations stay realistic.
One of the top community narratives on Fermi: 85% undervalued
"Rising power needs from artificial intelligence workloads are pushing large tenants to seek long duration, dedicated power solutions…"
Discover why this Narrative puts Fermi at 85% undervalued.
The Fermi share price is only one part of the story
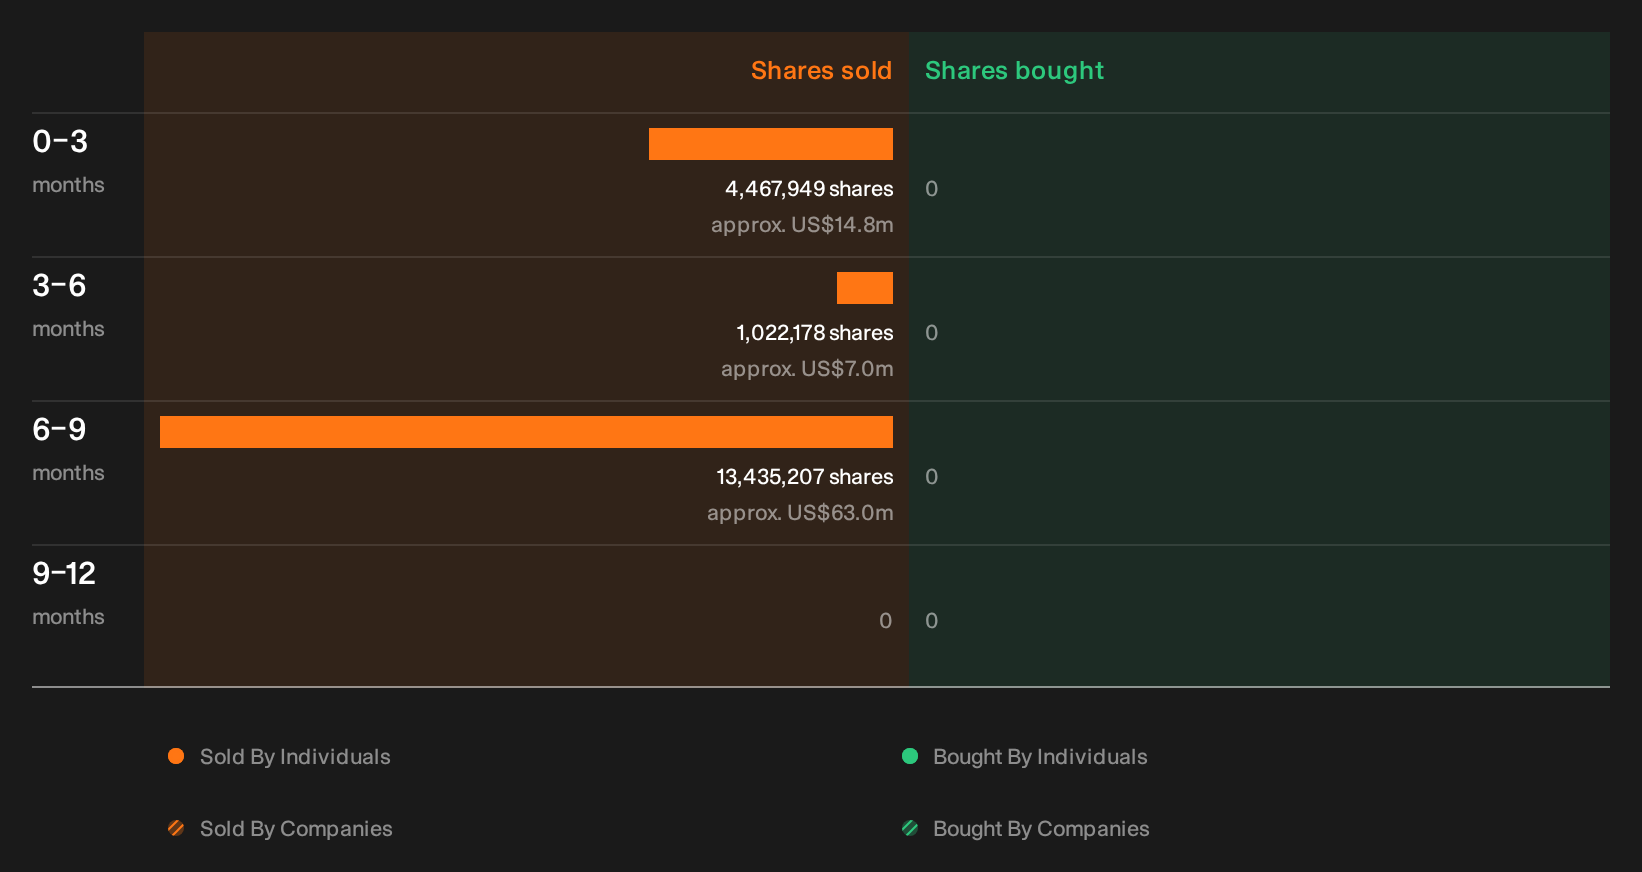
Price and book value frame Fermi today, but the recent selling activity by people inside the business that our checks have picked up can add a very different dimension to your decision. See the recent insider selling flagged for Fermi.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com