
ATOSS Software (XTRA:AOF) Could Be 23% Undervalued On Strong Q3 With Cautious Guidance
ATOSS Software earnings trigger fresh questions for the stock
ATOSS Software (XTRA:AOF) just posted third quarter 2026 results, reporting higher revenue, net income and earnings per share, along with more cautious guidance that puts execution risks around cloud and AI adoption in sharper focus for investors.
ATOSS Software shares jumped after the Q3 release, with a 1-day share price return of 8.71% and a 30-day share price gain of 14.34%. However, the year-to-date share price is still down 16.02% and the 1-year total shareholder return has declined 18.57%, suggesting recent momentum is rebuilding from a weaker longer-term base.
Capitalize on the renewed interest in ATOSS Software by comparing it with a hand-picked 195 high quality undervalued stocks that also pair recurring revenue strength with more cautious market expectations.The rebound in ATOSS Software leaves a clear gap between a €94.90 share price and valuation markers pointing higher. Is that spread a genuine margin of safety, or a sign estimates need to adjust?
Most Popular Narrative: 23% Undervalued
ATOSS Software closed at €94.90 while the most followed narrative points to a fair value around €123.38, putting the current enthusiasm after Q3 into the context of a still sizeable implied discount built on cloud and AI adoption assumptions.
The shift toward cloud based workforce management is already visible in ATOSS Software, with cloud and subscription revenues now at 53% of total revenue and cloud ARR of €109.8 million. This can support higher recurring revenue visibility and a more stable earnings base over time.
See why 2 investors see ATOSS Software as 23% undervalued.
Analysts in that narrative anchor their view on revenue growth of about 13.5% per year and profit margins near 24.9%. They then discount those future earnings at 6.7% to arrive at the implied fair value. To align with this, you would need to be comfortable with earnings reaching €72.9 million and the stock trading on a P/E of roughly 32x those 2029 profits.
The same storyline leans heavily on ATOSS Software converting its workforce management base to cloud subscriptions and on AI driven productivity to support an EBIT margin target of at least 34% for 2026. If contract wins, migration from maintenance and AI adoption track those expectations, the narrative argues that the current gap between €94.90 and the €123.38 fair value can be justified by recurring earnings quality and cash generation.
Result: Fair Value of €123.38 (UNDERVALUED)
Still, ATOSS Software faces a softer manufacturing and SMB backdrop, plus slower maintenance to cloud migration, which could challenge those upbeat AI and margin assumptions.
Find out about the key risks to this ATOSS Software narrative.
Another view on ATOSS Software valuation
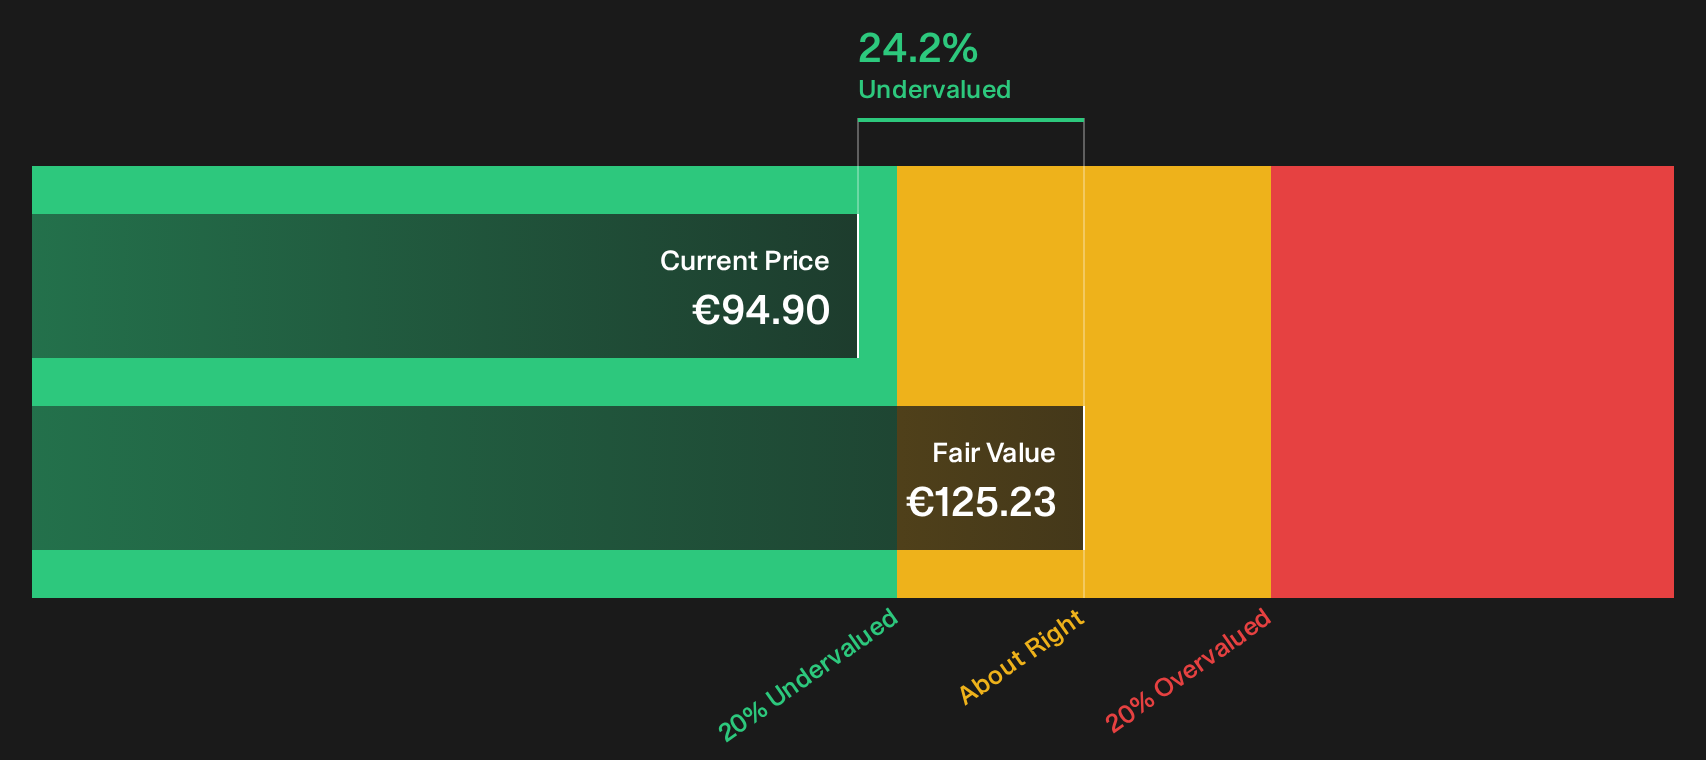
Our DCF model points to a fair value of about €125.23 per share, which is above the current €94.90 price and close to the €123.38 narrative fair value. Both methods lean in the same direction, so the question becomes which set of assumptions you trust more around cash flows and risk.
Before relying on any single model, it helps to understand how the cash flow math is built and where it could be wrong under different scenarios for cloud demand and AI spending. Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this all feels upbeat, treat it as a prompt rather than a conclusion, and stress test the assumptions yourself while sentiment is still resetting. To see which specific positives analysts are focused on, review the 5 key rewards
Looking for more investment ideas beyond ATOSS Software?
Do not stop your research with a single ticker. Broadening your watchlist across different styles can reveal opportunities you did not expect at first glance.
- Target potential mispricing by scanning a 195 high quality undervalued stocks that combines solid fundamentals with prices the market has not fully rewarded yet.
- Build more resilient income by reviewing a 224 dividend fortresses that focuses on payout strength and consistency.
- Reduce guesswork around financial stability by checking a list of solid balance sheet and fundamentals (207 results) that already filters for robust finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com