
Scandic Hotels Group (OM:SHOT) Shares Sit 5% Above Fair Value After Hilton Deal
Scandic Hotels Group (OM:SHOT) has entered a multi year development agreement with Hilton in the Nordics, tying Scandic's regional hotel platform to Hilton's global brands and loyalty reach.
Scandic Hotels Group's agreement with Hilton lands at a time when momentum in the share price has been picking up, with a 30 day share price return of 14.19% and a 90 day gain of 20.43%. The 3 year total shareholder return of 192.81% and 5 year total shareholder return of 159.80% point to a long term uptrend that this new partnership could potentially influence further.
Scan for other hotel and travel operators showing similar momentum and regional expansion by running the curated 610 high quality undiscovered gems alongside Scandic Hotels Group in your idea list.
Bulls point to Scandic Hotels Group's long run of strong shareholder returns and the Hilton agreement, while bears see recent gains and execution risk. Which story do the valuation numbers lean toward next?
Most Popular Narrative: 5% Overvalued
Scandic Hotels Group last closed at SEK101.4 compared with a widely followed fair value narrative of SEK96.75. The market is therefore pricing in a premium to that story and to the 10.49% discount rate underpinning it.
The planned full acquisition of Dalata’s operations, after an initial period of management fee income and with guidance for at least 15 to 20% EPS accretion based on 2024 pro forma figures, signals further scope for earnings growth once the portfolio is fully consolidated.
Rapid rollout of the Scandic Go economy concept, including new openings in Sweden and Finland, a first hotel in Oslo and signed projects in Tromsø, Stavanger and central Stockholm, creates additional room capacity at lower capital intensity that can lift revenue while supporting margins.
See why 10 investors see Scandic Hotels Group as 5% overvalued.
Result: Fair Value of SEK96.75 (OVERVALUED)
Still, a broader slowdown in Nordic or UK and Ireland travel, or a prolonged drag from Finland, could quickly challenge the current Scandic Hotels Group narrative.
Find out about the key risks to this Scandic Hotels Group narrative.
Another View: SWS DCF Model Flags Deep Undervaluation
The analyst fair value story pegs Scandic Hotels Group at SEK96.75 and frames the stock as about 5% overvalued. A different lens tells a very different story. The SWS DCF model estimates fair value at SEK292.04 per share, which implies the current SEK101.4 price could be far below that cash flow based mark. This raises the question of which anchor to treat as more reliable when the gap is this wide.
Before leaning on either signal, it helps to understand how the cash flow maths are built and where the biggest sensitivities sit in that SEK292.04 figure. Look into how the SWS DCF model arrives at its fair value.
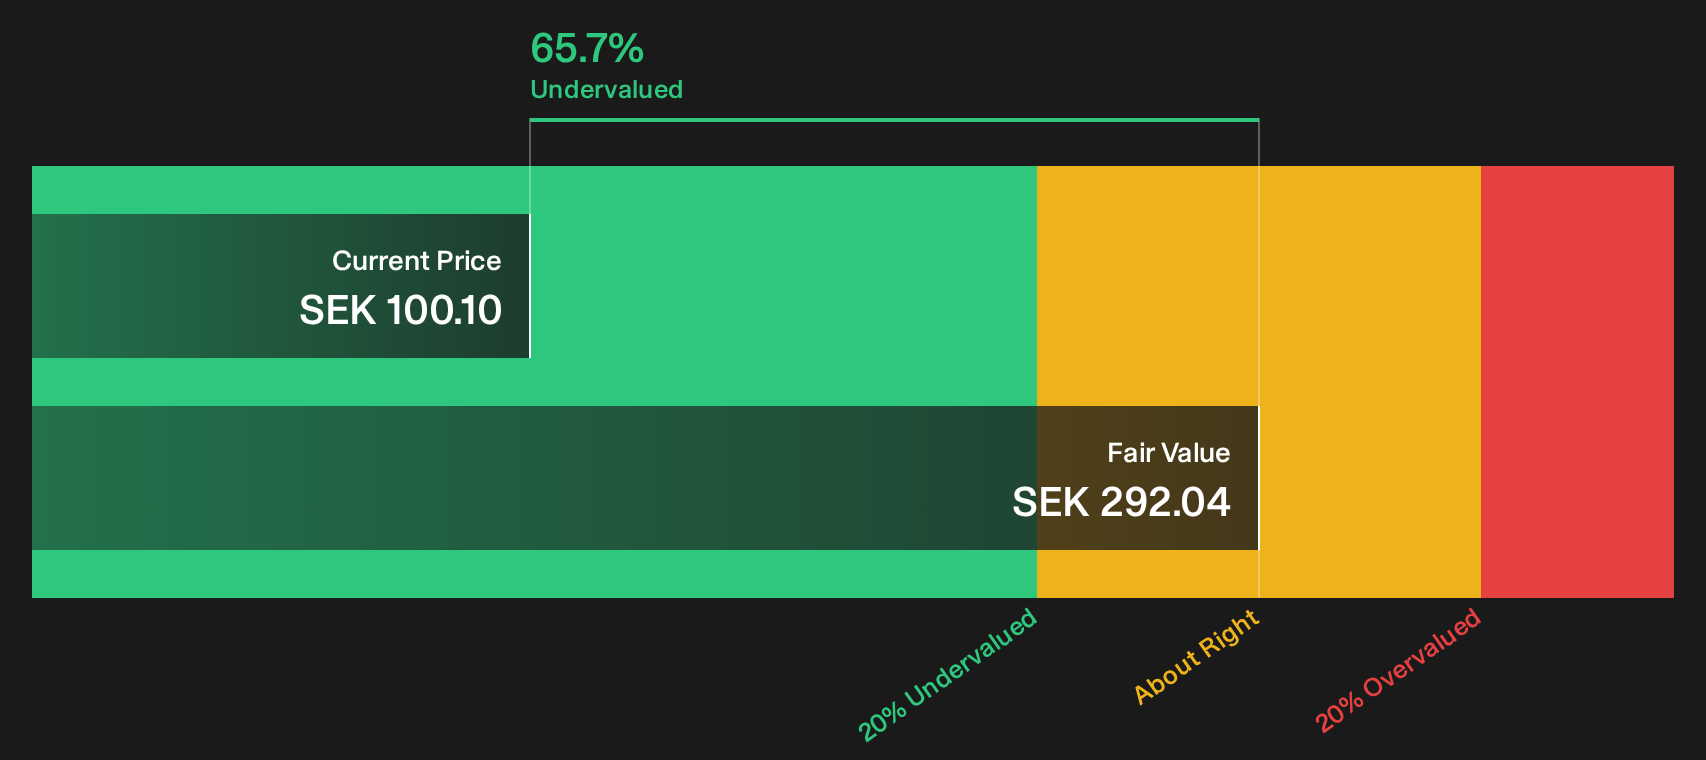
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Scandic Hotels Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Confident in the story so far or unsure what to make of the mixed signals around Scandic Hotels Group? Move fast, review both the concern side and the upside case, and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Scandic Hotels Group?
If you only stop at Scandic Hotels Group, you risk missing other stocks where the risk reward trade off might suit your goals even better.
- Target potential mispricings by comparing quality and valuation across the 195 high quality undervalued stocks to see which businesses look out of sync with their fundamentals.
- Prioritise resilience by filtering companies with strong finances using the list of solid balance sheet and fundamentals (207 results) so you focus on sturdier balance sheets.
- Hunt for future standouts early by scanning the 610 high quality undiscovered gems and flagging lesser known stocks with promising fundamentals before they gain wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com