
WD-40 (WDFC), Why Is Its Latest Update Drawing Attention?
WD-40 (WDFC) just released a busy earnings update, combining fourth quarter and full year 2026 results with fresh 2027 guidance that indicates a focus on higher sales and profit, along with an update on its ongoing share repurchase activity.
At a share price of US$216.06, WD-40 has logged a 1-month share price return of 8.48% and a year to date share price gain of 9.81%, while the 1-year total shareholder return of 12.72% contrasts with a 3-month share price decline of 5.79%. This pattern hints that recent earnings, guidance, the Duluth Trading collaboration and progress on buybacks have refreshed momentum after a softer patch.
Capitalize on the fresh momentum around WD-40 by scanning a curated shortlist of other quality companies with resilient earnings profiles in our 30 resilient stocks with low risk scores.Bulls see WD-40 as a quality compounder back on track, while bears point to richer expectations after the rebound. Which case holds up once the valuation is unpacked next?
Most Popular Narrative: 20.5% Undervalued
At a last close of $216.06, the most followed narrative for WD-40 points to a fair value of $271.67, implying meaningful upside once those assumptions are stress tested against the actual cash generation and market size.
The main thing that has to go right is for WD-40 to execute on premiumization of its Multi-Use Product and growth of Specialist lines and e-commerce while managing higher petroleum-based input costs so that margins remain resilient.
See why 9 investors see WD-40 as 20% undervalued.
Using a 7.24% discount rate, this narrative anchors on mid single digit annual revenue growth, an 11.49% long run profit margin and a P/E of 47.2x on projected 2029 earnings, which is well above the 22.0x level cited for the wider US household products group. The result is a fair value estimate of $271.67 per share, compared with the current market capitalization of about $2.9b and analysts in broad agreement that the share price could move higher if those earnings and margin paths materialize.
The same storyline leans heavily on WD-40’s remaining headroom in its estimated $1.9b attainable maintenance market, the relatively low penetration of premium formats such as Smart Straw and EZ-REACH in emerging regions, and Specialist products that currently touch only around 12% of their addressable category. E-commerce, which is running at under 10% of revenue but growing a little above 20% year to date, is treated as a further lever for mix, pricing power and return on equity. Return on equity is already assessed as high at 30.2% today and is forecast to reach 35.2% in 3 years.
Risks inside the same framework are not ignored, including pressure on gross margin from higher petroleum based inputs and a homecare and cleaning portfolio that now represents less than 2% of sales yet trims about 40 basis points from consolidated gross margin while gently shrinking. A key swing factor is how long the market is willing to pay a premium multiple, since a shift closer to the 16.8x to 22.0x P/E ranges cited for peers and the US household products industry could compress the share price even if earnings follow the current forecast path.
Result: Fair Value of $271.67 (UNDERVALUED)
Still, the WD-40 narrative can crack if higher petroleum based input costs squeeze margins longer than expected, or if the premium P/E multiple fades faster than earnings grow.
Find out about the key risks to this WD-40 narrative.
Another View: WD-40 On Earnings Multiples
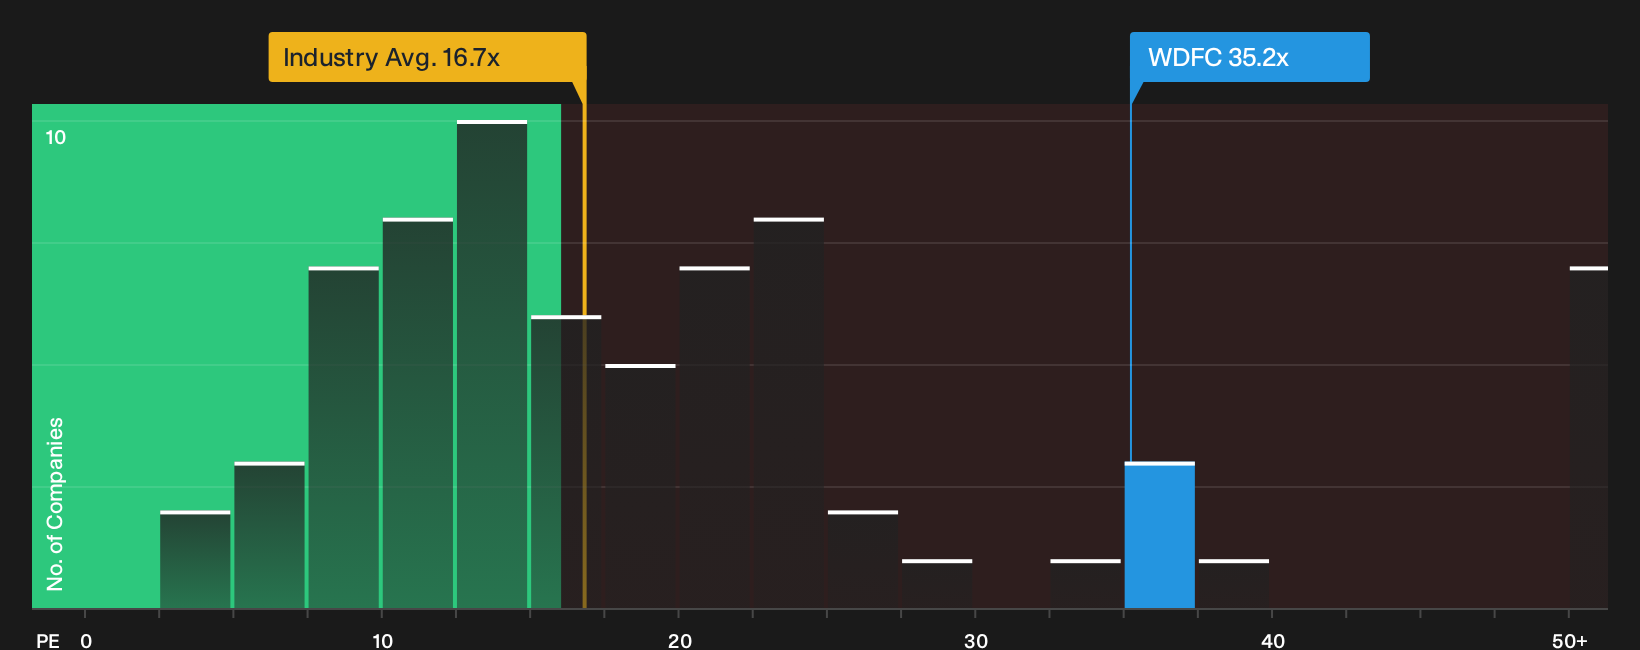
That fair value story for WD-40 runs straight into a very different signal from simple P/E math. The stock trades on 35.2x earnings, compared with 16.8x for the global household products group, 18.3x for peers and a fair ratio of 15.5x that the market could move toward. That gap points to valuation risk rather than a clear edge. How comfortable are you paying more than double the sector on this earnings profile?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on WD-40 is split, which is exactly why looking at the underlying data yourself can be so powerful. To see what optimistic investors are focusing on, start with the 3 key rewards.
Looking for more WD-40 style investment ideas?
You have seen how investors are weighing WD-40. Now widen your opportunity set by using focused stock lists that surface different edges in the market.
- Target potential mispricings by scanning a curated pool of quality companies that screens for valuation support through the 29 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by hunting for businesses with durable balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Get ahead of the crowd by tracking underfollowed opportunities with robust fundamentals through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com