
What Cathay Pacific Airways Buyers Were Betting On
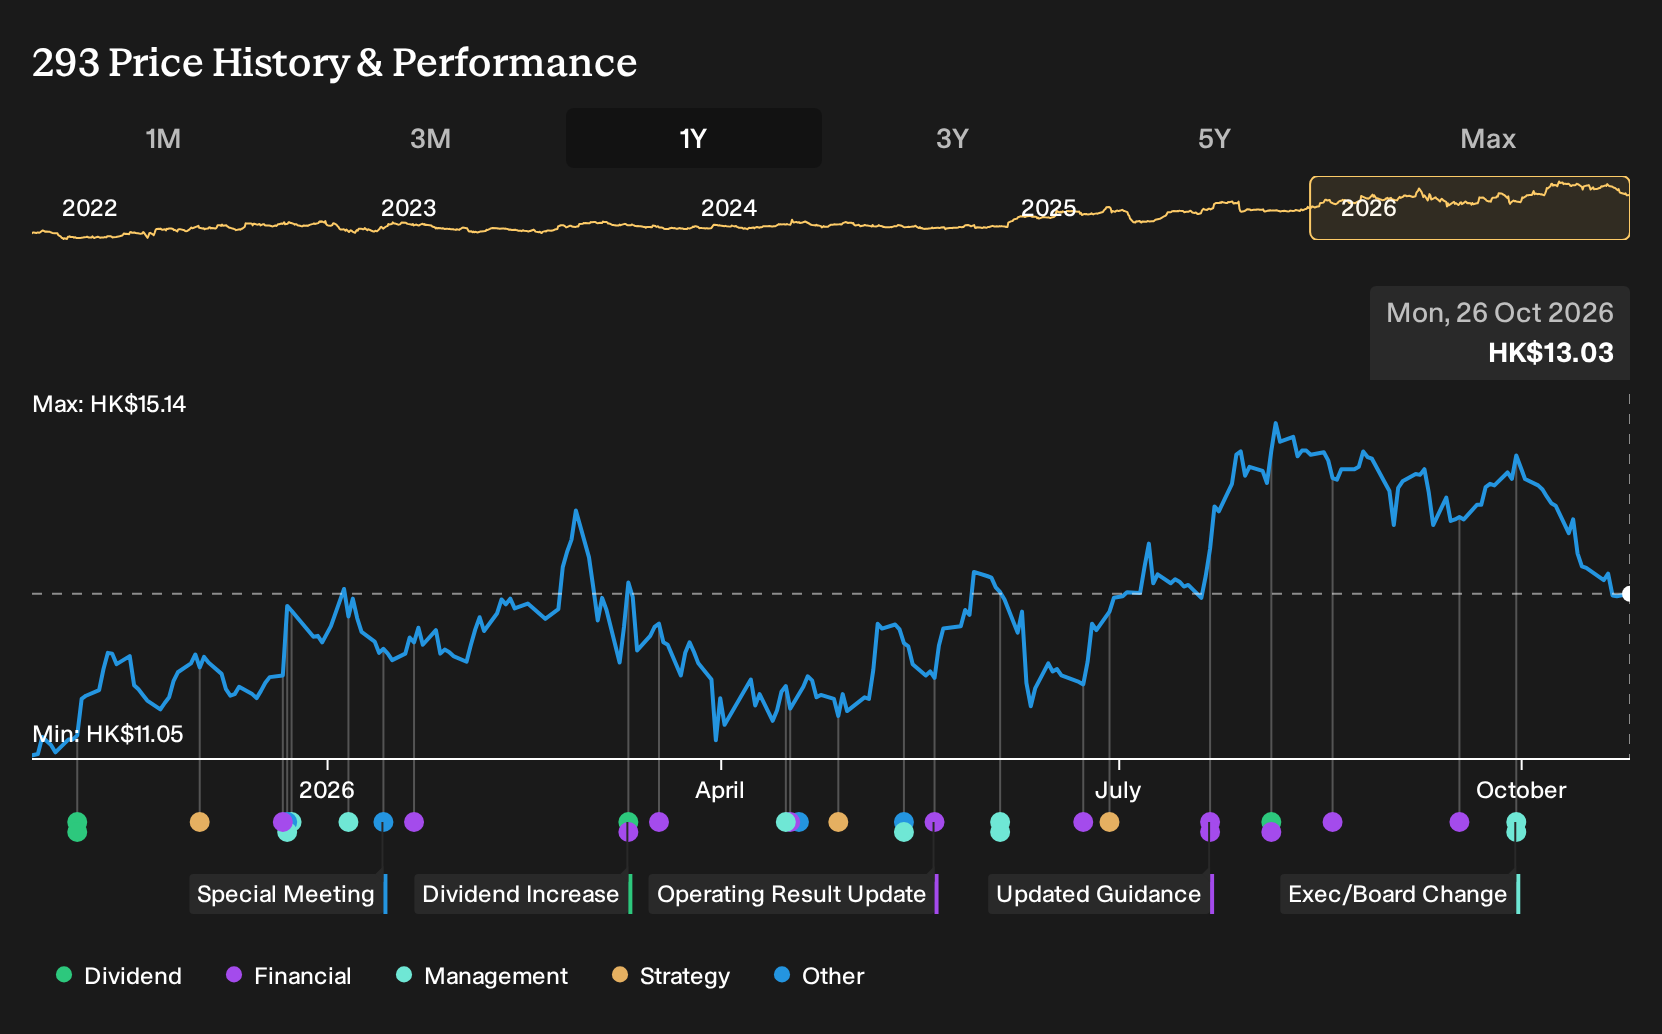
If you only glanced at the early 2025 debate around Cathay Pacific Airways, you probably focused on the tug of war between aggressive expansion hopes and worries about trade wars and cargo reliance. For Cathay Pacific Airways shareholders, the return over the past year was 26.9%, including dividends. If you had been weighing those opposing narratives back on 26 October 2025, what specific evidence would have justified taking the risk?
The easy part of this move is behind Cathay Pacific Airways. Zero in on 195 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Cathay Pacific Airways
The shares cost HK$11.01 at the start of the period, which left Cathay Pacific Airways investors choosing between an expansion story and a trade-war worry list.
On the optimistic side, the bullish view saw a Fair Value of HK$13.1, a price implied by rapid network growth and premium positioning. That rested on an assumption that revenue could rise 8.4% a year with earnings reaching HK$11.9b by 2028.
The cautious case put Fair Value at HK$9.15 and focused on trade conflict. This narrative assumed revenue growth of 5.5% and an 8.0% profit margin, with a future P/E of 8.0x if cargo exposure hurt through a prolonged US China dispute.
What The Results Changed For Cathay Pacific Airways
The clearest new fact came from Cathay Pacific Airways reporting H1 2026 numbers. Revenue moved from HK$54,309m in H1 2025 to HK$68,061m, while net income rose from HK$3,651m to HK$6,243m and net margin widened from 6.7% to 9.2%. That pattern supported the optimistic case more than the cautious one, although it did not remove trade-war or cargo risk.
The lesson to carry to the next stock is simple. When a thesis hangs on higher profitability, check whether net margin and absolute earnings both move in the direction the story assumes, and not just the share price.
What Cathay Pacific Airways’ Price Now Assumes
Cathay Pacific Airways trades at HK$13.03 today, up 26.9% over the past year. The selected Narrative’s Fair Value sits below the current price, which reflects a more cautious lens on what the airline’s spending and cost base might mean for future profitability.
The Narrative’s argument focuses on fuel, heavy capex and higher non fuel unit costs. For today’s valuation to hold, a buyer needs to judge that Cathay can convert HK$150b of fleet and product investment into pricing power strong enough to cover a larger, more volatile cost structure.
"Cathay’s commitment of about HK$150b for fleet and product investment, including 105 aircraft already on order and a long term target of 150 new aircraft and 150 destinations, creates a rising depreciation and financing burden that may pressure earnings and free cash flow if passenger and cargo yields do not keep pace with the enlarged asset base."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
One Step Beyond Cathay Pacific
Cathay Pacific shows how valuable a strong route network can be. Your next question is who helps cities feel closer even before takeoff.
Passengers still need to get to and from airports smoothly. That first and last stretch can decide whether a long trip feels manageable.
Another business focuses on stitching those ground journeys together. Its platform connects riders and drivers across mobility, deliveries and freight.
As long-haul flying grows more complex, this connector’s role may matter more. You might find its economics look very different from a traditional airline.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 75% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com