
Is MetLife (MET) Undervalued After Its New ChatGPT Pet Insurance Push?
MetLife (MET) just pushed its pet insurance business further into AI. The insurer launched a ChatGPT plugin that lets pet owners move from casual questions to personalized quotes and policy purchase in a single conversational flow.
MetLife’s ChatGPT move comes during a strong run in the shares, with the stock up 24.55% on a year-to-date share price return and a 30.46% total shareholder return over 1 year. The 3-year total shareholder return of 84.01% points to momentum that investors will be watching closely.
Scan how other insurers and AI-focused financial stocks are pushing into conversational tools with our curated 34 healthcare AI stocks to see where this kind of MetLife move might echo across the market.
MetLife is leaning into AI at the same time its shares are coming off a strong run. The real call now is whether that ChatGPT push justifies stepping in at US$100.04 today or waiting for a cheaper shot later, which is where valuation comes in next.
Most Popular Narrative: 7% Undervalued
The most followed MetLife valuation narrative puts fair value at $107.38, above the last close of $100.04. This frames this ChatGPT push against a stock already viewed as modestly cheap on long term cash generation.
Ongoing investment in technology and AI, including more than US$3.2b of spend over five years and visible automation in underwriting, claims and RFP processing, points to further unit cost efficiency that can support net margins and earnings quality. Continued execution of the New Frontier program, which has already been associated with 10% EPS growth in 2025, a 17% adjusted ROE in the first half of 2026 and direct expense ratios at or better than target, suggests further scope to sustain earnings and free cash flow that underpin MetLife’s current valuation.
See why 29 investors see MetLife as 7% undervalued.
Result: Fair Value of $107.38 (UNDERVALUED)
Still, the MetLife story can wobble if fee based earnings at MetLife Investment Management stay soft, or if Retirement and Income Solutions keeps feeling pressure on spreads.
Find out about the key risks to this MetLife narrative.
Another View: MetLife Looks Expensive On Earnings
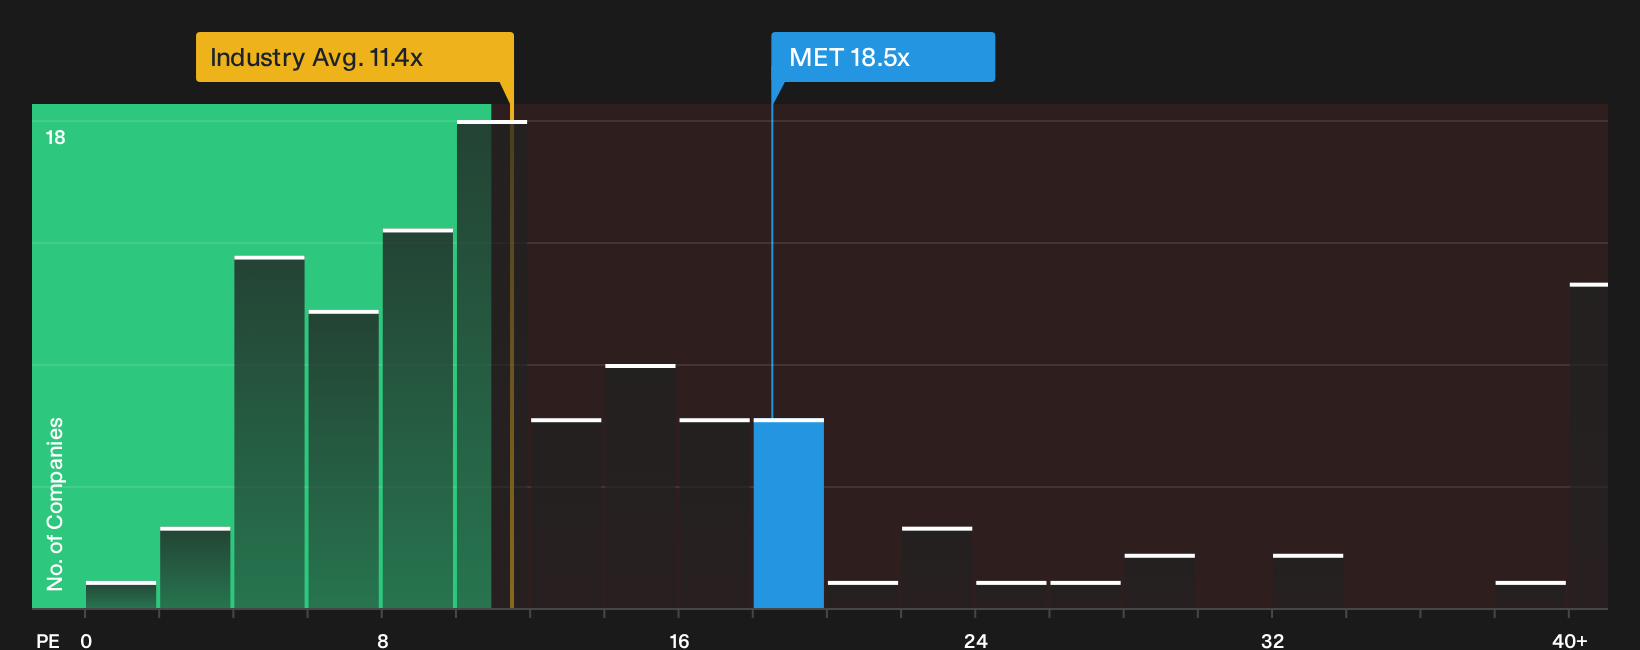
There is a very different picture when you look at MetLife through its P/E. The shares trade around 18.5x earnings, compared with 14.6x for peers and a fair ratio of 13.6x. That gap suggests investors are already paying up, which raises the question of how much upside is really left.
For a closer read on what this richer earnings multiple could mean in practice for future valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on MetLife so far, with both upside potential and clear concerns in play, mean you should move quickly and check the underlying data yourself. To weigh that tension directly, review the 3 key rewards and 1 important warning sign.
Looking for more MetLife style investment ideas?
If MetLife has you thinking more broadly about where to put fresh capital to work, let a focused screener surface a few targeted ideas worth your time.
- Target resilient value by scanning a 29 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritize income and stability by reviewing a hand picked 5 dividend fortresses built for investors who care about yield backed by fundamentals.
- Limit downside risk by running through a 30 resilient stocks with low risk scores that highlights companies with sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com