
What Johnson Controls Holders Bought Into
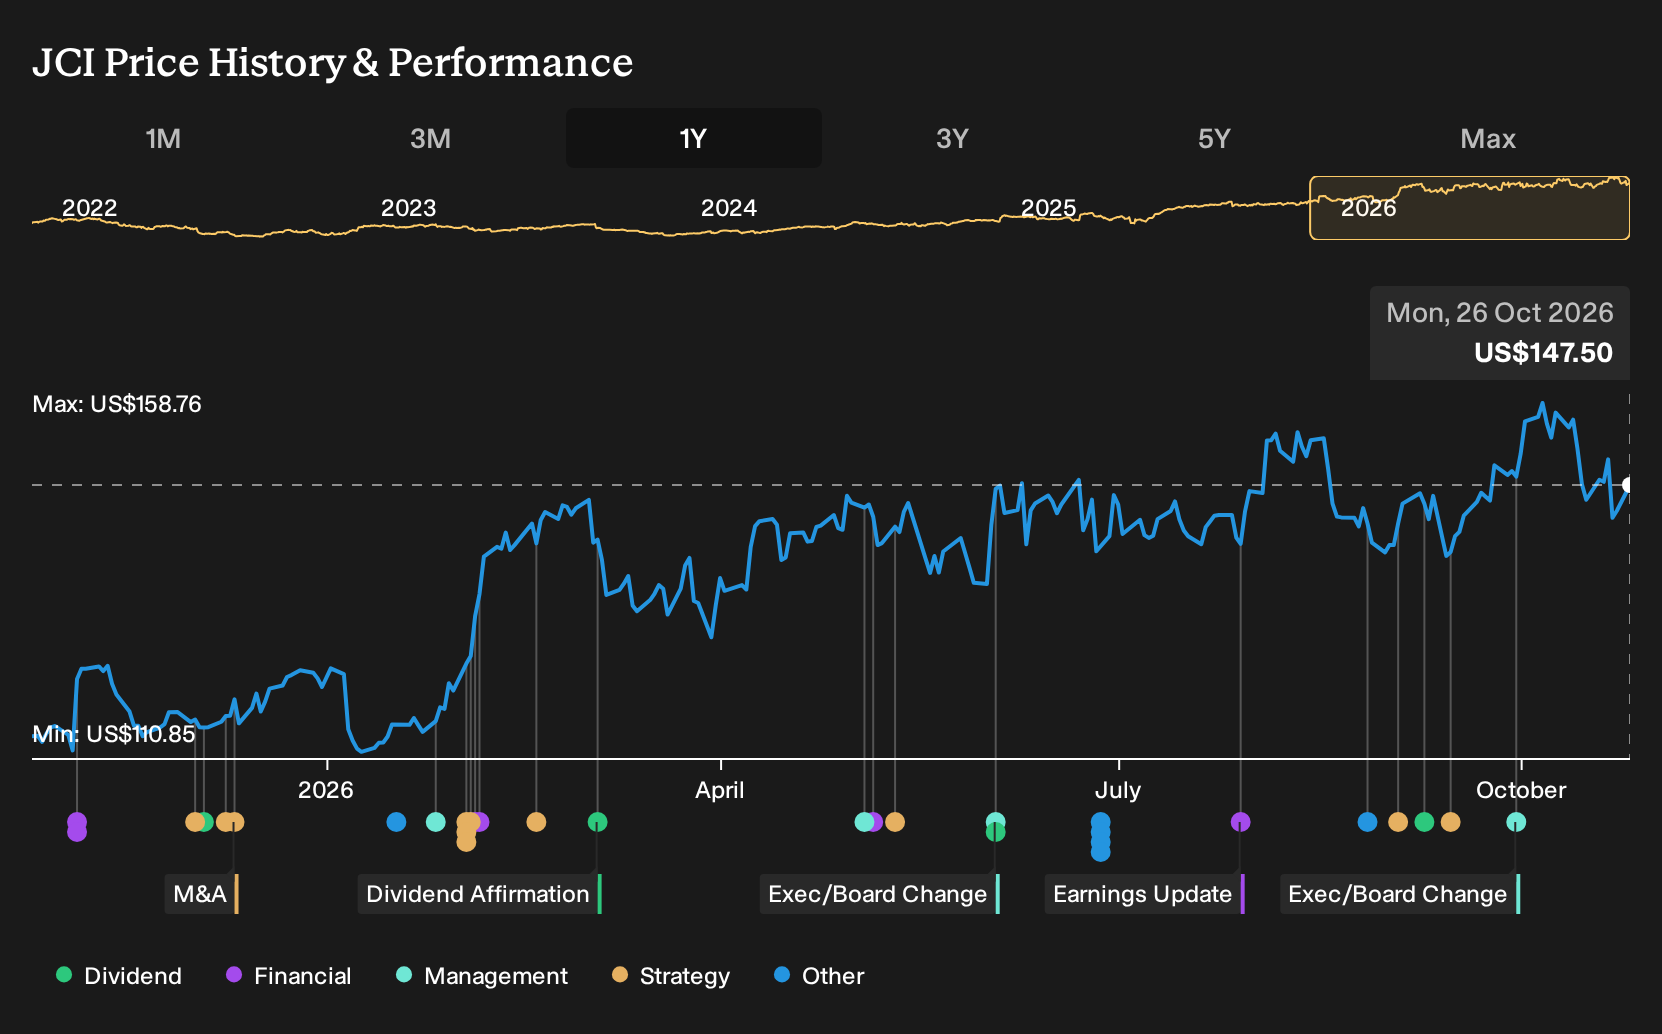
If you had bought Johnson Controls International on 26 October 2025 and simply held on, the result is in the rear-view mirror now. Investors who held Johnson Controls International over the past year are up 32.0%, including dividends. Early on, you were choosing between a bullish story tied to OpenBlue, Lean execution, and data center cooling, and a bearish script focused on mature markets and geopolitical risk. Which of those competing pictures looked more convincing at the time you had to decide?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
This theme extends beyond Johnson Controls International. See which of 55 AI infrastructure stocks may still merit a closer look.
The Two Johnson Controls International Stories Investors Were Weighing
The shares cost US$113 at the start, and anyone looking at Johnson Controls International then had to choose between two very different but reasonable stories.
On the bullish side, the Narrative put Fair Value at US$131. That view leaned on OpenBlue, smart city demand, and data center cooling, plus an assumption that margins could reach 13.1% with earnings of US$3.6b by 2028.
The cautious Narrative set Fair Value at US$79. It focused on mature markets, geopolitical risk, higher procurement costs, and the possibility that rising competition and commoditisation might cap revenue growth at 3.5% with earnings of US$3.3b by 2028.
What The Results Changed For The Johnson Controls International Thesis
Johnson Controls International reported Q3 2026 revenue of US$6.6b and net income of US$749m, with net margin at 11.3% compared with 10.2% a year earlier. That profitability shift, plus a record US$20b to US$21b backlog tied to data center cooling and AI related projects, pointed to the more optimistic story built on Lean execution and OpenBlue driven demand.
The takeaway is simple. When a thesis leans on higher returns from better operations, you track revenue, profit and margin together and see whether efficiency and mix are actually lifting all three at the same time.
What Johnson Controls International’s Price Now Assumes
Johnson Controls International trades at US$148 today, with this cautious Narrative arguing that its Fair Value sits below the current price.
The Narrative leans on concerns about delayed data center projects, PFAS related cash demands, and service execution. A buyer here needs confidence that high single digit organic growth with strong operating leverage actually lands despite those risks.
"While Johnson Controls International highlights record orders and a growing data center pipeline, customer projects are already seeing 3 to 4 month delays in electrical infrastructure versus typical lead times. This can push out equipment delivery and revenue recognition and create a risk that the expected shift of data center revenue toward roughly one third of sales drags on overall revenue and earnings timing."
The price and this Narrative do not agree. → Uncover what this Narrative says Johnson Controls International is actually worth
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 35% below our estimate - uses record power systems demand and added capacity to support high horsepower computing.
- Company 2 - 26% below our estimate - sells injectable therapies for weight management and diabetes to a rapidly expanding patient base.
- Company 3 - 40% below our estimate - expands coconut based beverages as private label and international buyers increase category exposure.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com