
Should Strong Q3 Earnings Require Action From Roper Technologies (ROP) Investors?
- Roper Technologies reported third quarter 2026 sales of US$2,171.8 million and net income of US$484.7 million, with higher basic and diluted earnings per share from continuing operations than a year earlier.
- For the first nine months of 2026, Roper Technologies recorded US$6,376 million in sales and US$2,162.1 million in net income, alongside new GAAP EPS guidance for the fourth quarter and full year.
- We will now look at how Roper Technologies' stronger third quarter earnings and updated GAAP EPS guidance could influence its investment narrative.
Roper Technologies Investment Narrative Recap
To own Roper Technologies, you need to be comfortable with a portfolio built around vertical software and technology products that depend on consistent execution in dozens of end markets. The third quarter and year to date results show higher sales, net income and EPS versus a year earlier, which supports that operating model rather than changing it. The short term swing factor still looks like how well management keeps organic growth steady while absorbing prior deals.
The biggest near term risk remains capital deployment into new software acquisitions on top of already higher debt levels and one off items in recent earnings. If future targets do not deliver, the group’s revenue mix and margins could come under pressure. Recent numbers do not remove that risk, but they give investors fresh data to judge how existing businesses are holding up while Roper Technologies lines up its next transactions.
The fresh GAAP diluted EPS guidance for the fourth quarter of 2026 of US$4.27 to US$4.32 and full year EPS of US$25.60 to US$25.65 is the most relevant update for this earnings release. That range connects the strong nine month print with what management thinks is achievable over the next few months, which matters if you are tracking execution rather than just headline growth.
For catalysts, that guidance becomes a reference point against the longer term story of AI driven products, vertical SaaS expansion and potential software M&A capacity above US$5b. If reported EPS lands outside the guided band, it could change how investors weigh those opportunities against the flagged risks such as forecast earnings declines over the next three years and sensitivity to any slowdown across Roper Technologies’ 29 businesses.
Roper Technologies’ current narrative points to revenue of US$10.2b and earnings of US$2.1b by 2029, built on analyst assumptions of 6.5% yearly top line growth and a decline in profit from US$2.6b today to that 2029 consensus. This implies earnings would need to fall by about US$500m over the period.
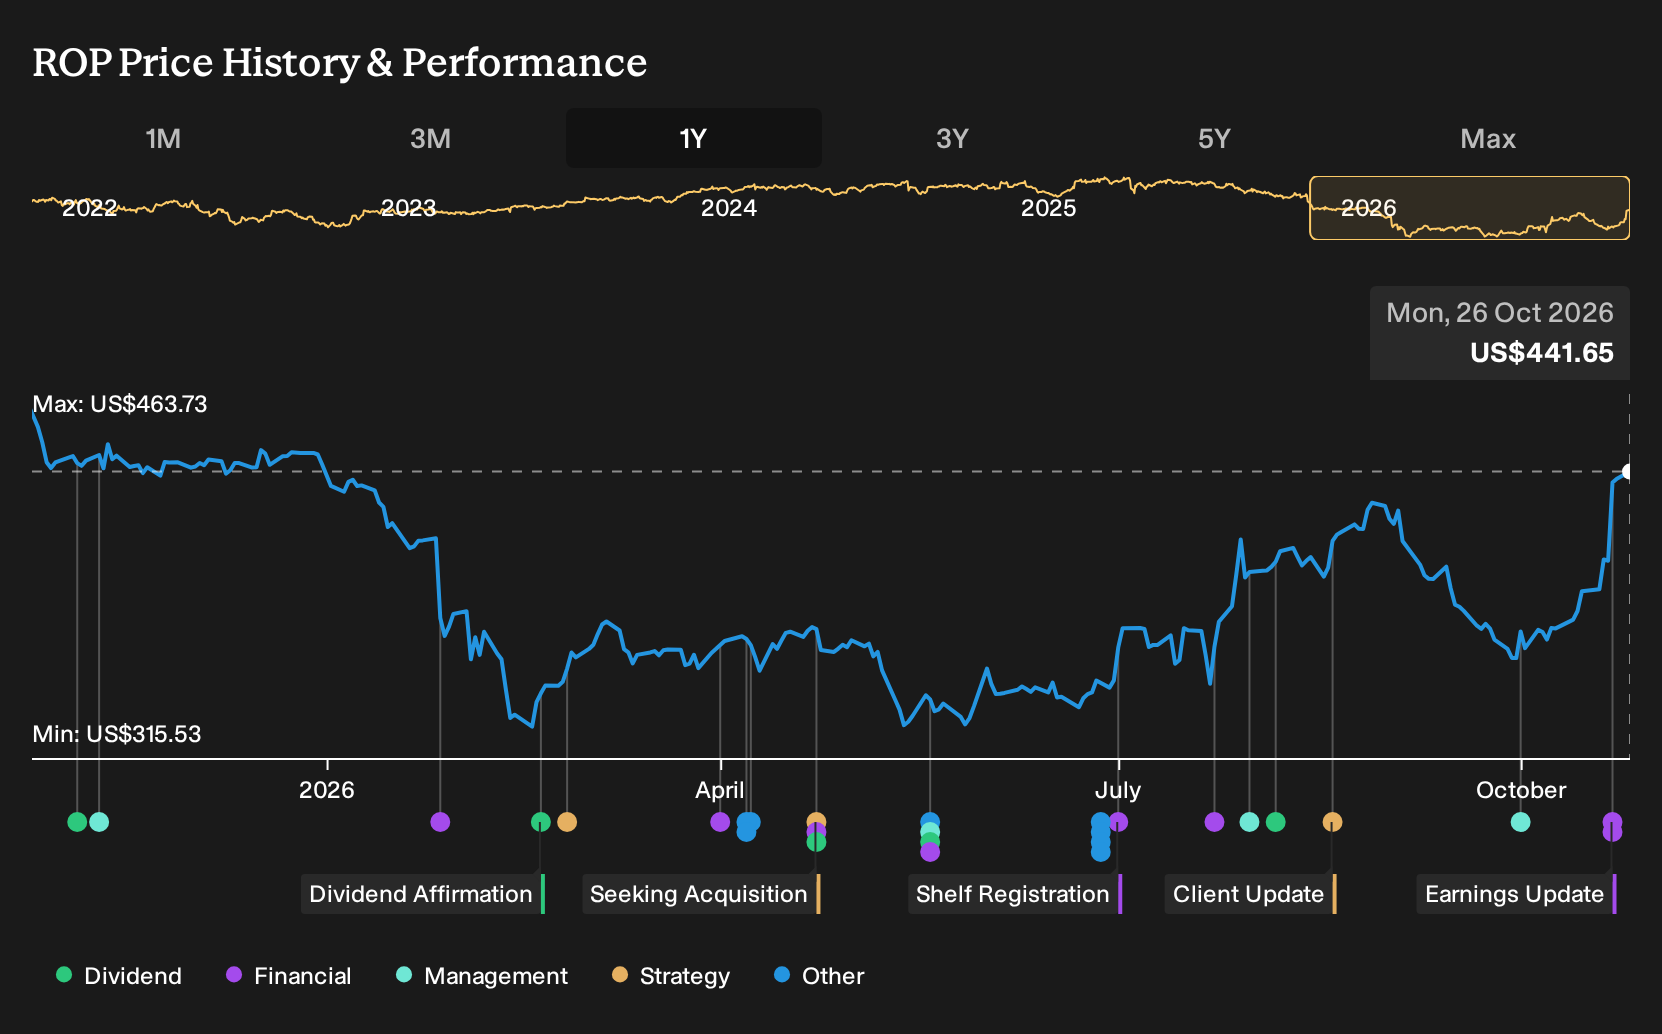
Uncover why Roper Technologies' fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$457 and US$524 per share, which already shows how far private views on Roper Technologies can stretch. When you set that against the planned US$5b plus acquisition capacity and AI related product push, you may reach very different conclusions on future resilience. Opinions clearly diverge. You should explore several of these alternative viewpoints before leaning on any single narrative.
Explore 2 other Roper Technologies fair value estimates, including one that suggests it could be worth just $457.29.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Roper Technologies research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Roper Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Roper Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Roper Technologies?
Once you have a view on Roper Technologies, it can help to set that opinion against a broader watchlist of potential opportunities. Using the Simply Wall St Screener, you can quickly compare different themes, balance sheet profiles and income characteristics without losing sight of risk.
- For investors who want potential upside with strict financial quality filters, start with a curated set of 21 high quality undiscovered gems that pair strong fundamentals with lower visibility.
- If resilience and capital preservation sit at the top of your checklist, compare Roper Technologies with a list of solid balance sheet and fundamentals (24 results) to see which businesses match your tolerance for volatility and debt.
- For readers who care about regular cash returns as well as fundamentals, use the income focused lens of 5 dividend fortresses to find higher yielding stocks that still clear quality hurdles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com