
Will Earnings Beat Change Mycronic Stock Narrative (OM:MYCR)
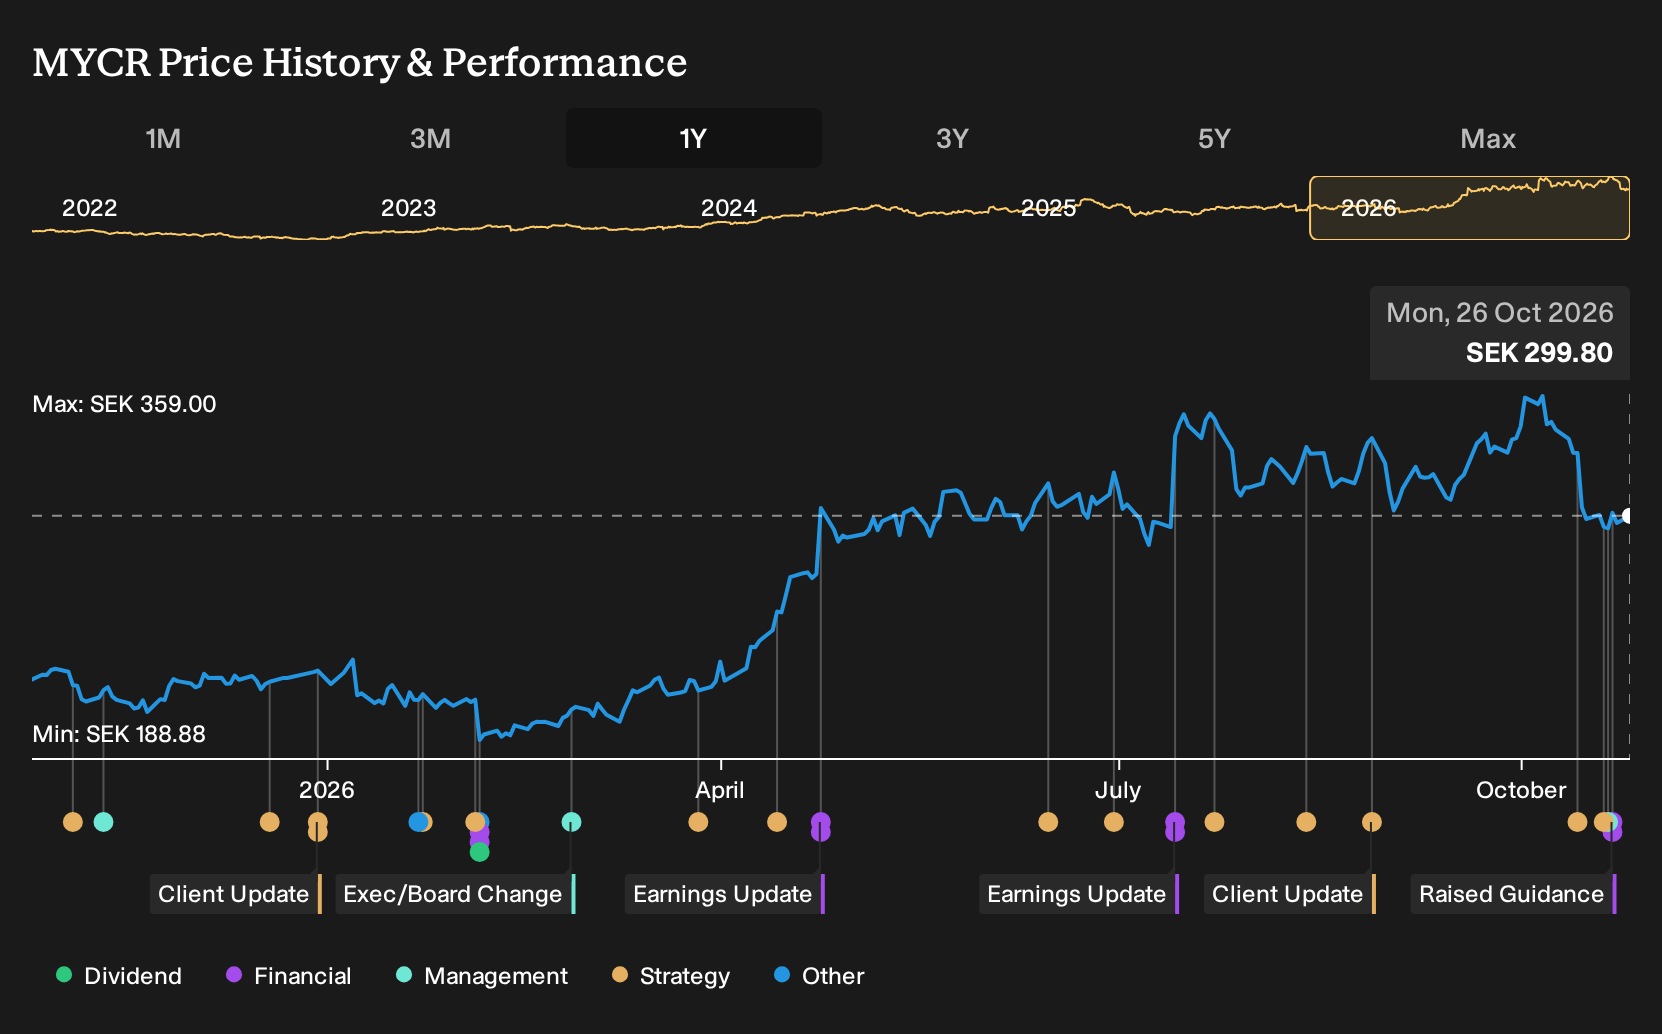
- Mycronic reported third quarter 2026 sales of SEK 2,356 million and net income of SEK 471 million, and raised full year 2026 net sales guidance from SEK 9.25b to SEK 9.75b.
- The higher guidance, combined with fresh SLX mask writer orders in Europe and the US, points to firm demand visibility in Mycronic’s core equipment franchises.
- This article examines how Mycronic's investment narrative is shaped by the raised 2026 sales guidance following strong third quarter earnings.
Compare Mycronic's upgraded outlook with a hand-picked peer group by scanning 94 robotics and automation stocks that are also riding demand for advanced production equipment and automation gear.
Mycronic Investment Narrative Recap
To be a shareholder in Mycronic, you need to believe that demand for advanced production equipment, especially in Pattern Generators and High Volume, can support sustained earnings quality while weaker units are repaired. The Q3 figures, with SEK 2,356 million in sales and SEK 471 million in net income, plus raised 2026 sales guidance, point to management seeing solid visibility.
The most important near term catalyst is execution on the order pipeline in AI and advanced packaging gear without squeezing margins as the mix shifts. The key risk still sits in PCB Assembly Solutions and newer Pattern Generators lines, where lower profitability and missed improvement targets could cap group earnings progression.
The raised full year 2026 net sales guidance to SEK 9.75b is the announcement that really matters for this earnings print. It ties directly to whether Mycronic can turn a strong order backdrop into consistent top line delivery while expanding its role along the semiconductor back end and advanced packaging chain.
For catalysts, that higher sales view supports the idea that SLX mask writers, IQX inspection tools and acquired platforms such as Cowin and Hprobe can be absorbed into a larger revenue base. Execution risk remains, especially if lower margin lines grow faster than legacy mask writers, but the updated guidance suggests management is comfortable with that mix for now.
Mycronic's narrative projects SEK 12.6b revenue and SEK 2.9b earnings by 2029. This reflects 13.4% yearly revenue growth and an earnings increase of SEK 1.2b from SEK 1.7b today.
Uncover why Mycronic's fair value indicates a 7% potential upside to its current price, a discount that could narrow quickly if sentiment continues to improve.
Exploring Other Perspectives
One alternate storyline places demand for Pattern Generators at the center of the concern. Before this news, the most pessimistic analysts were working with only 5.1% annual revenue growth and SEK 2.1b in 2029 earnings, compared with the SEK 12.6b and SEK 2.9b consensus path. Use this guidance hike to test which version you find more convincing.
Explore 2 other Mycronic fair value estimates, including one that suggests it could be worth just SEK321.67.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Mycronic research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Mycronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mycronic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mycronic?
Once you have formed a view on Mycronic, it can help to widen the lens and compare it with other businesses that share similar qualities or offer different risk and income profiles.
- If you want potential upside with a margin of safety, consider using the screener focused on attractively priced quality companies by reviewing 195 high quality undervalued stocks.
- For income focused investing and a focus on reliability, sort through companies with resilient payout profiles by checking the 224 dividend fortresses.
- When capital preservation matters most, narrow the universe to sturdier balance sheets and steadier risk profiles using the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com