
Ashland (ASH), Why Is Fresh Attention Building Around The Stock?
Ashland (ASH) heads into its November 3 earnings release with the market already focused on an expected $1.30 per share and revenue of $500.66 million, which implies year-over-year top-line growth.
The Ashland share price has climbed 20.84% year to date to US$72.32, while a 46.72% total shareholder return over the past year far outpaces its 3 year and 5 year records. This suggests momentum has recently been building as investors reposition ahead of the earnings release.
Scan for other materials stocks showing similar pre earnings momentum using our curated list of 29 high quality undervalued stocks.
Ashland now appears to be a stronger business based on recent numbers and share price performance. The tougher question is whether that improved story is already fully reflected in today’s valuation.
Most Popular Narrative: 10% Undervalued
Ashland is trading at $72.32 against a widely followed fair value estimate of $80.18, which frames the stock as modestly mispriced and puts execution on future projects under the spotlight.
Strong commitment to R&D and platform based product development, highlighted by the transformed vegetable oil and multifunctional starch platforms, new life sciences excipients and growth in biofunctional actives, is already tied to early commercial orders and pipelines that point to future revenue contribution and earnings leverage as these technologies scale.
See why 2 investors see Ashland as 10% undervalued.
Result: Fair Value of $80.18 (UNDERVALUED)
Still, Ashland faces ongoing securities fraud investigations and plant-level operational issues, which could pressure margins and keep the market cautious on the story.
Find out about the key risks to this Ashland narrative.
Another View On Ashland’s Valuation
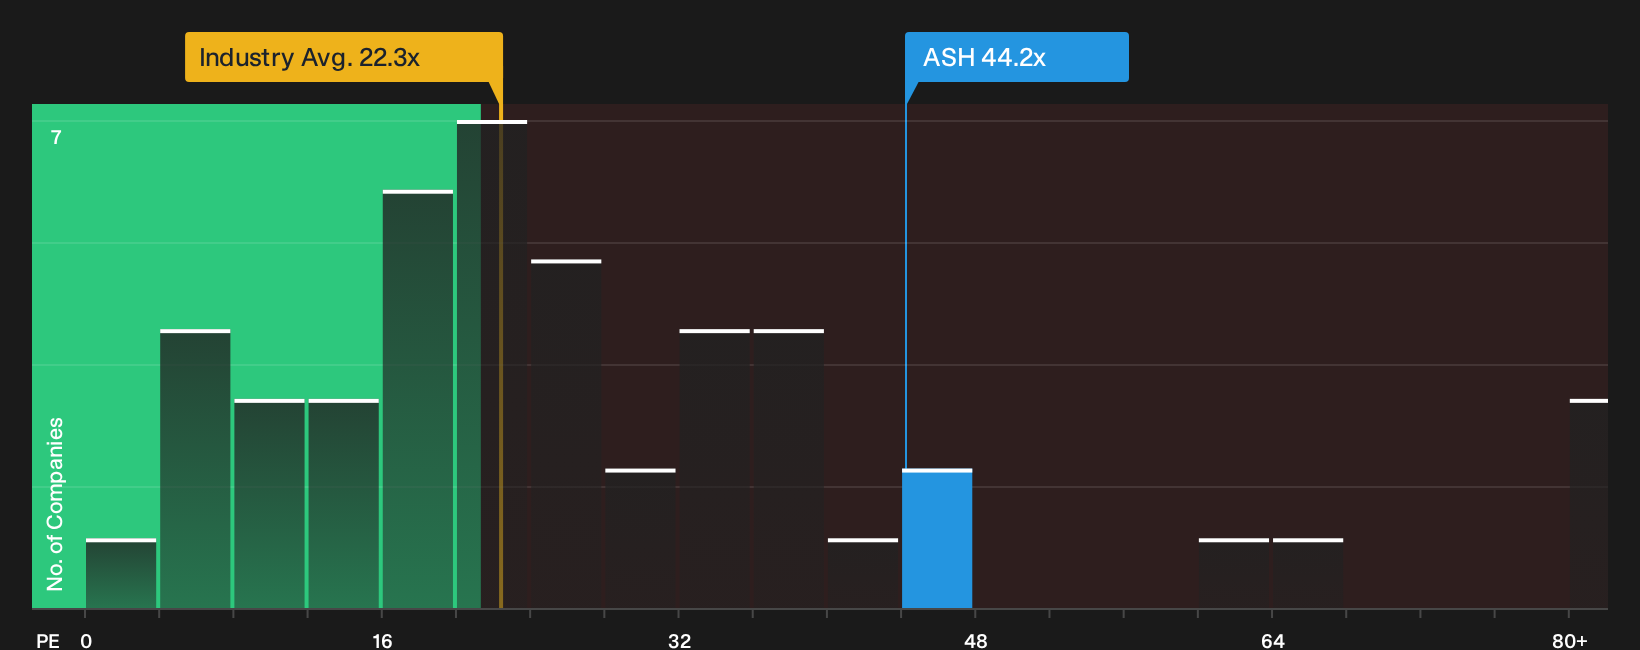
The earlier fair value of $80.18 leans on analyst forecasts and a target P/E of 23.8x by 2029. On current numbers, Ashland trades on a P/E of 44.2x, versus a fair ratio of 26.8x, the US Chemicals industry on 22.1x, and peers on 20.8x. That premium signals clear valuation risk if sentiment cools.
Investors who rely more on earnings multiples than discounted cash flows may want to understand why the current ratio sits so far above both the industry and the fair ratio, and what would need to change in the story for that gap to feel comfortable.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With mixed signals around Ashland’s valuation and story, now is the moment to test the numbers yourself and pressure check the narrative. To see both sides of the ledger in one place, review the 3 key rewards and 2 important warning signs
Looking for more Ashland sized investment ideas?
If Ashland has sharpened your focus, do not stop here. Broader opportunity sits with the investors who keep hunting for the next strong setup.
- Target resilient compounding potential by scanning our 30 resilient stocks with low risk scores for businesses with steadier risk profiles and fewer balance sheet surprises.
- Hunt for mispriced quality using the curated 29 high quality undervalued stocks and spot companies where fundamentals and current pricing look out of sync.
- Unearth under followed stories before the wider market catches on through the hand picked 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com