
Has Appian (APPN) Run Too Far As Cloud Growth And Federal Demand Lift Views?
Recent commentary around Appian (APPN) focuses on stronger operational execution, faster cloud subscription momentum, and firmer demand from federal customers. Together, these factors help explain the stock’s recent move and current valuation debate.
Across the past quarter the share price has surged, with a 90 day share price return of 88.56% and a year to date gain of 51.41%. The 1 year total shareholder return of 65.93% contrasts with a weaker 5 year total shareholder return that remains in decline.
Scan how Appian compares to other fast moving software players by reviewing the hand picked 21 high quality undiscovered gems now catching market attention.
The recent surge in Appian now collides with a wide gap between the current US$51.57 share price and the analyst target at US$34.80. Where does a reasonable view of fair value actually land in that spread?
Most Popular Narrative: 52% Overvalued
The most followed narrative currently anchors Appian’s fair value at $34, which sits well below the latest close at $51.57. That gap reflects a view that the recent surge has run ahead of the long term cash flow story, even with improving execution and AI driven demand.
Ongoing improvements in sales execution, leadership alignment, and sales & marketing productivity (highlighted by eight consecutive quarters of increased go-to-market efficiency) suggest potential for further margin expansion and enhanced operating leverage, supporting long-term earnings growth.
See why 17 investors see Appian as 52% overvalued.
Based on this narrative, the analysis applies a discount rate of 8.88% to Appian’s projected cash flows and arrives at that $34 fair value anchor. The valuation case leans on expectations for revenue to reach about $1.1b and earnings of $138.4m by 2029, with the stock trading on a future P/E of 20.6x if those forecasts play out.
The same storyline cuts both ways for investors weighing Appian. On one hand, management has reduced losses over the past 5 years at an annual rate of 24.4%, earnings are forecast to grow very quickly, and the business is expected to move into profitability within 3 years. On the other hand, the firm remains loss making today with net income of a $10.62m loss on $795.3m of revenue, carries negative shareholder equity, and operates in a crowded software field where larger rivals are investing heavily in similar automation and low code tools.
Result: Fair Value of $34 (OVERVALUED)
Still, several pressure points could flip the Appian story, including intense competition from larger platforms and the risk that high R&D and sales spending will not scale efficiently.
Find out about the key risks to this Appian narrative.
Another View: DCF Points To Slight Undervaluation
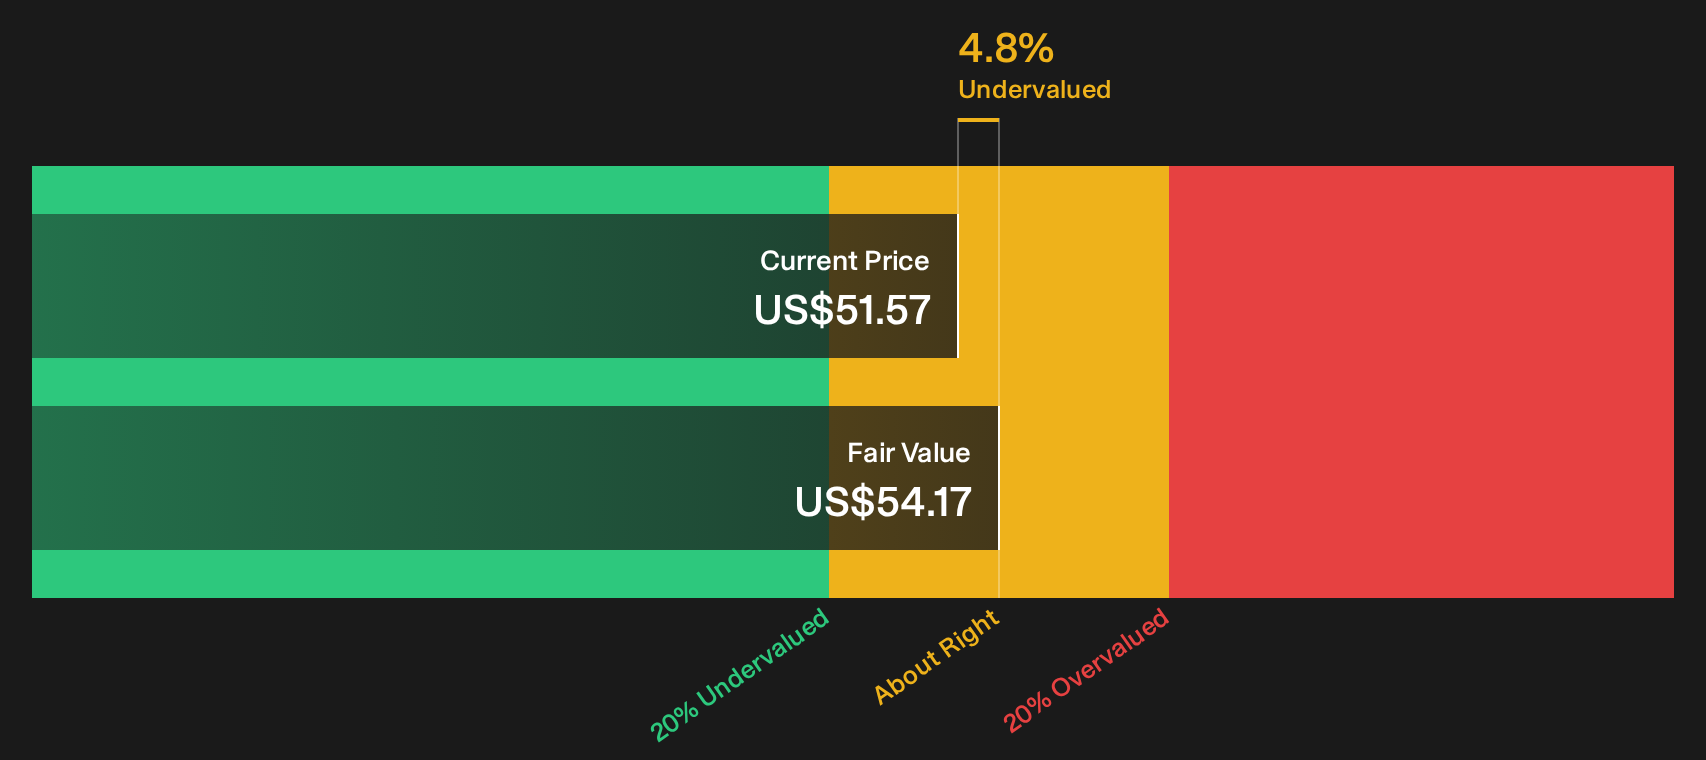
A different lens on Appian comes from the SWS DCF model, which estimates fair value at $54.17 against the current $51.57 share price. That implies the stock trades about 4.8% below this cash flow based mark. Which yardstick do you trust more when the gap is this small?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Appian for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Appian so far, right, with strong enthusiasm about future cash flows but clear questions on the risk and durability of the recent run. Act quickly, stress test that optimism, and compare it against your own expectations by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Appian?
If Appian has sharpened your interest, do not stop here. Broaden your watchlist with other clear setups that could sharpen your overall portfolio decisions.
- Target potential value opportunities by reviewing our focused list of 29 high quality undervalued stocks that pair quality fundamentals with appealing pricing signals.
- Prioritize resilience and sleep better at night by scanning 30 resilient stocks with low risk scores built around companies with sturdier risk profiles.
- Strengthen your income toolkit by checking 5 dividend fortresses that highlight higher yielding payers with the potential for more durable distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com