
Ship Healthcare Holdings (TSE:3360) Draws Undervalued Interest, Is The Market Missing Contract Cash Flows?
Recent commentary around Ship Healthcare Holdings (TSE:3360) focuses on a valuation gap. A discounted cash flow model suggests the share price does not fully reflect cash flows from long term healthcare service contracts.
The recent move to ¥2,610.5 comes after a 30 day share price return of 5.47%, while the year to date share price performance is slightly down 0.97%. With a 1 year total shareholder return of 11.93% and 3 year total shareholder return of 24.71%, Ship Healthcare Holdings shows a pattern where short term share price momentum is picking up again, even though longer term holders have seen more moderate results over five years.
Spot undervalued healthcare cash flow stories similar to Ship Healthcare Holdings by scanning our curated list of 16 high quality undervalued stocks that share resilient earnings and contract visibility.Ship Healthcare Holdings now trades higher than a month ago, yet still appears at a discount relative to DCF estimates and analyst targets. Strong healthcare contracts are one factor. Whether the current price reflects a different story is an open question.
Price-to-Earnings of 17.6x: Is it justified?
On simple earnings terms, Ship Healthcare Holdings trades on a P/E of 17.6x, which sits above both its healthcare peers and the broader industry averages mentioned in third party analysis.
The P/E ratio compares the current share price to earnings per share. For a healthcare services group like Ship Healthcare Holdings, that multiple is often used as a shorthand for what the market is willing to pay for each unit of current profit, especially when revenue is spread across recurring contracts in medical supply, life care, and pharmacies.
Here, the stock is described as good value versus an estimated fair P/E of 19.1x. At the same time, it looks expensive against the JP Healthcare industry on 14.4x and a peer set on 14.2x. That mix of signals suggests investors are paying a richer price than sector averages, and that any move toward the fair P/E level would rely on the market continuing to credit Ship Healthcare Holdings for its forecast 11.5% annual earnings growth and high quality earnings profile.
Explore the SWS fair ratio for Ship Healthcare Holdings.
Result: Price-to-Earnings of 17.6x (ABOUT RIGHT)
Still, the story around Ship Healthcare Holdings can change quickly if long term healthcare contracts are repriced or delayed, or if earnings growth falls short of current expectations.
Find out about the key risks to this Ship Healthcare Holdings narrative.
Another view of Ship Healthcare Holdings valuation
The P/E points one way, but the SWS DCF model points another. On that cash flow view, Ship Healthcare Holdings at ¥2,610.5 screens as undervalued versus an estimated future cash flow value of ¥3,116.48. That gap raises a simple question: which signal deserves more weight for you?
Look into how the SWS DCF model arrives at its fair value.
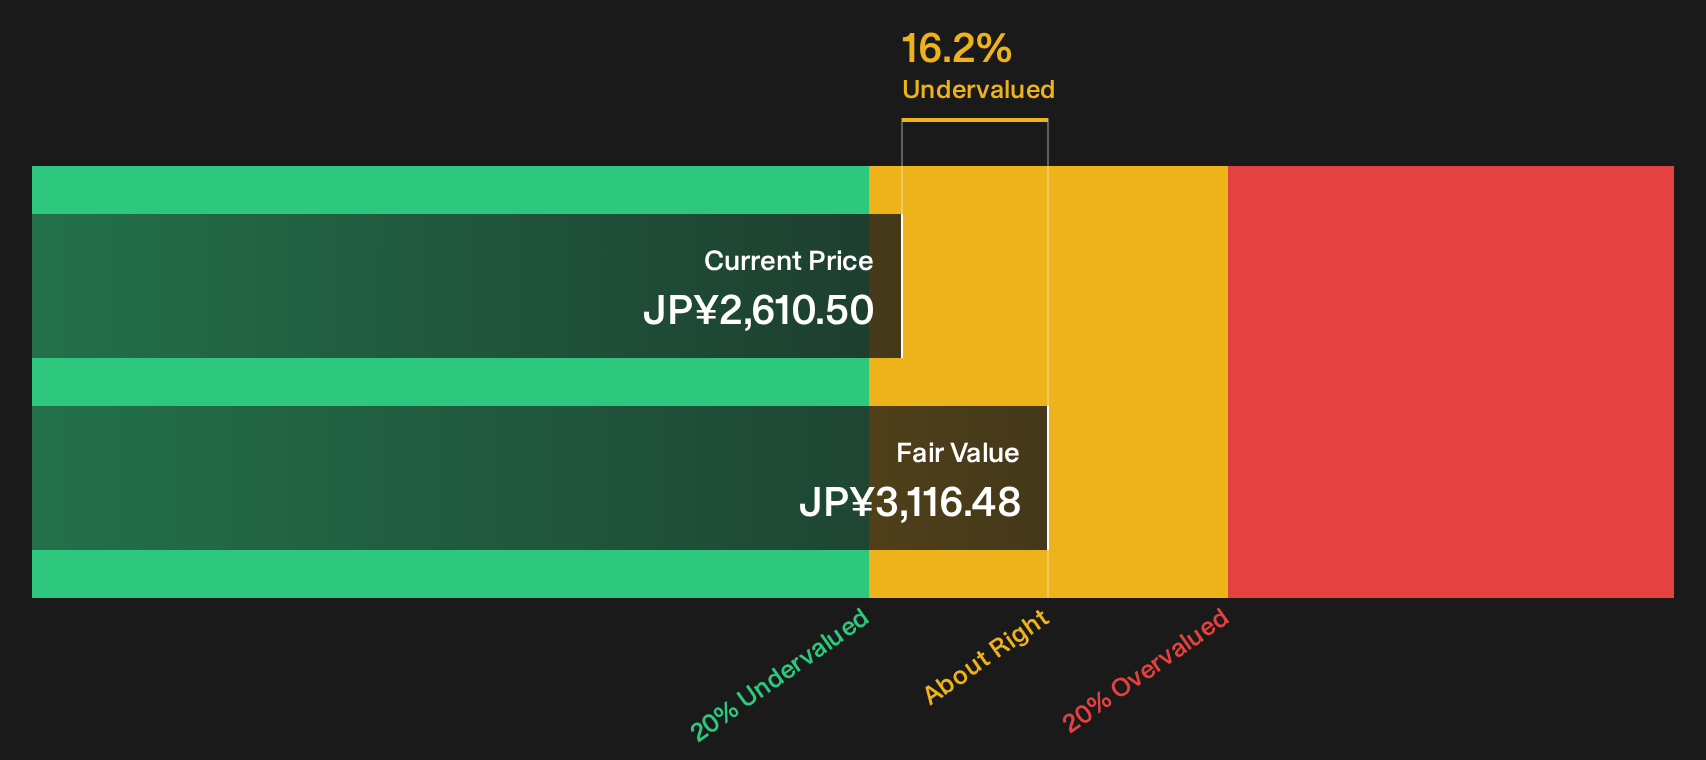
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ship Healthcare Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment looks mixed around Ship Healthcare Holdings right now, so move quickly, review the source numbers, and shape your own conclusion while the data is fresh. To see what the current optimism is built on, review the 3 key rewards
Looking for more investment ideas beyond Ship Healthcare Holdings?
If Ship Healthcare Holdings has your attention, do not stop here. Broader idea hunting with structured tools can support your next step and help you stay prepared.
- Target resilience by reviewing companies that combine strong fundamentals with healthy balance sheets through the list of solid balance sheet and fundamentals (23 results).
- Explore potential value by scanning the 72 high quality undiscovered gems that pair robust financial profiles with limited market attention.
- Reduce portfolio stress by focusing on stability oriented ideas highlighted in the 22 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com