
Can Kuros Biosciences (SWX:KURN) Justify Its Valuation On Raised 2026 Guidance?
Kuros Biosciences (SWX:KURN) reset expectations on 15 October, lifting its full year 2026 earnings guidance and now projecting sales growth between 36% and 40%, a shift that quickly drew fresh market attention.
That guidance upgrade triggered a sharp swing in sentiment, with Kuros Biosciences delivering a 24.63% 7 day share price return and a 19.25% 30 day share price return, even though the year to date share price return is still down 21.29% and the 1 year total shareholder return is down 28.03%. At the same time, longer term total shareholder returns over three and five years remain very large multiples of the starting point, suggesting recent momentum has picked up again from a much higher base.
Scan beyond Kuros Biosciences and see how other high growth stories stack up on valuation, quality and momentum in our hand picked 610 high quality undiscovered gems list.
Stronger guidance and a sharp rebound tell one story about Kuros Biosciences. A P/E of 113.3x tells another. Is this still a robust business that is simply expensive, or is the current price justified?
Price-to-Earnings of 113.3x: Is it justified?
On simple multiples, Kuros Biosciences looks expensive. The last close at CHF21 comes with a P/E of 113.3x, while the market data here classifies the stock as trading at a large discount to an estimated fair value based on other methods.
The P/E ratio compares the current share price to earnings per share. For a profitable healthcare business like Kuros Biosciences, it acts as a shorthand for how much investors are paying for each unit of current profit, and how confident they are that those profits will be sustained or improved.
Here, the P/E of 113.3x is far above the estimated fair P/E of 53.6x that the fair ratio work points to. That is more than double the level the regression based fair ratio suggests the market could gravitate toward. This indicates that buyers are paying a heavy premium for the current earnings base.
Set against peers, that premium looks even starker. The same data shows the European Biotechs industry on 16.2x and a direct peer group on 50.5x. Kuros Biosciences is therefore priced at a multiple more than 7x the wider sector and more than 2x its peer average, which suggests that expectations for this ticker are materially higher than for most comparable stocks.
Explore the SWS fair ratio for Kuros Biosciences.
Result: Price-to-Earnings of 113.3x (OVERVALUED)
Still, the Kuros Biosciences story can be knocked off course if high expectations embedded in that 113.3x P/E collide with slower execution or product setbacks.
Find out about the key risks to this Kuros Biosciences narrative.
Another view on Kuros Biosciences valuation
The P/E suggests Kuros Biosciences is expensive, yet the SWS DCF model points in the opposite direction. At CHF21, the stock is described as trading 84.2% below an estimated future cash flow value of CHF132.5, which implies a very different risk and reward balance. Which lens do you trust more when the two pull this far apart?
Look into how the SWS DCF model arrives at its fair value.
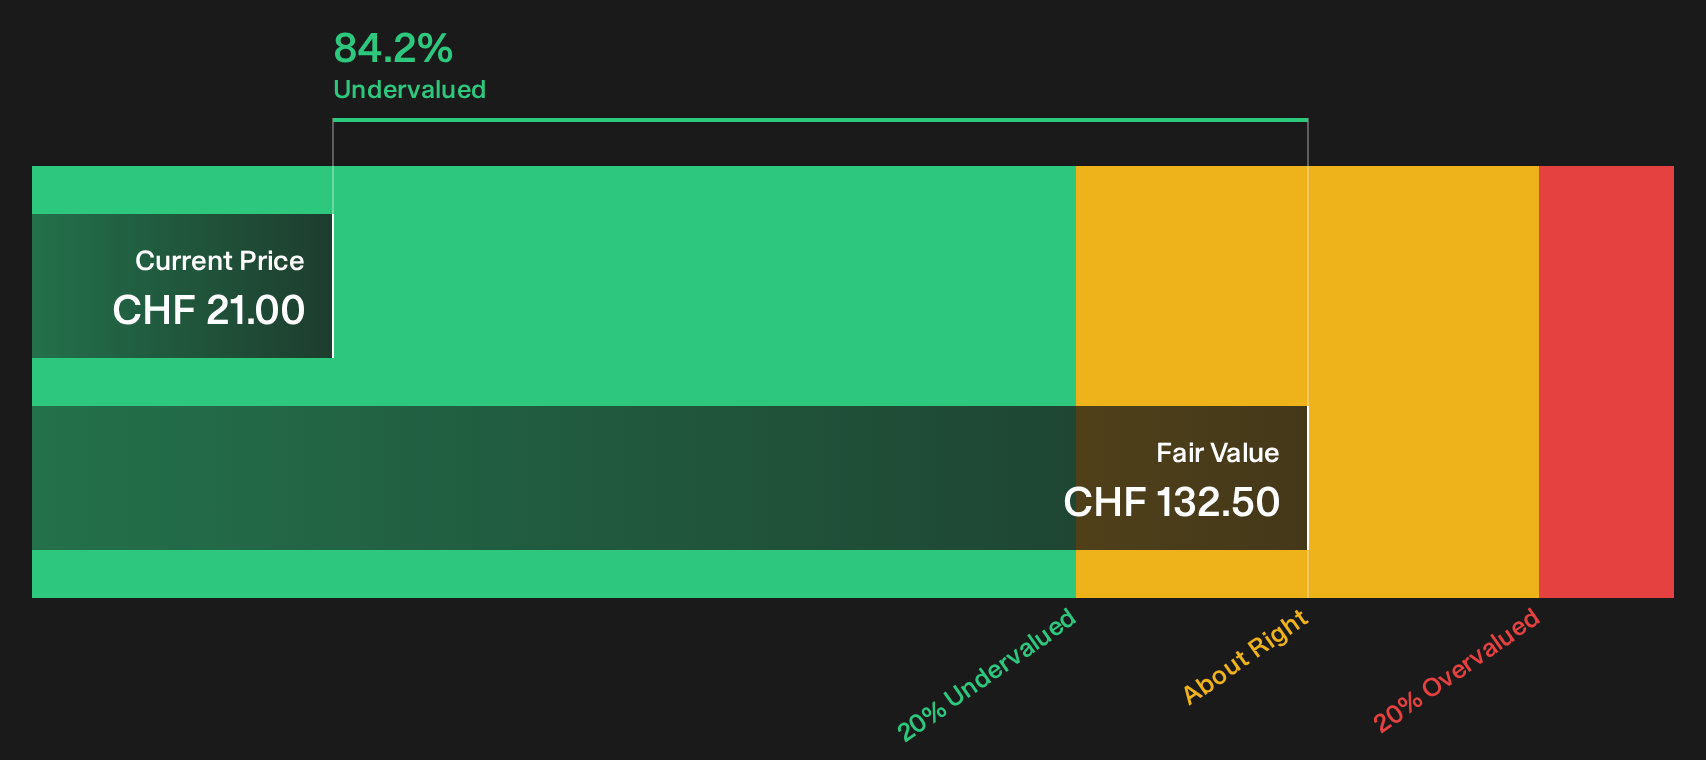
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kuros Biosciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big moves and split valuation signals around Kuros Biosciences can pull you in either direction, so consider the latest data carefully and build your own view using the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Kuros Biosciences?
If Kuros Biosciences has sharpened your focus on pricing power and expectations, do not stop here. The wider market still holds plenty of potential mispricings.
- Target stability seekers by reviewing companies with resilient balance sheets and consistent fundamentals in the list of solid balance sheet and fundamentals (207 results).
- Spot potential value opportunities by scanning for quality businesses trading below what their fundamentals suggest in the 195 high quality undervalued stocks.
- Prioritise capital preservation by filtering for companies with relatively lower risk profiles using the 223 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com