
Elite Undervalued Stocks For October 2026
Artificial intelligence spending has pushed China’s industrial profits up 14.4% year on year, reminding investors that strong cash generation matters even when headlines swing between excitement and concern. When profits and cash flows hold up, but share prices lag, valuation gaps can appear. This article singles out three US stocks that currently look underpriced relative to their future cash flow characteristics, based on our cash flow focused screener.
The three ideas in this piece are only a small sample, as the full screen surfaced 87 more companies with cash flow stories that look just as compelling on our metrics. To see the complete list and start identifying your own highest conviction targets, head straight to the Undervalued Stocks Based On Cash Flows screener.
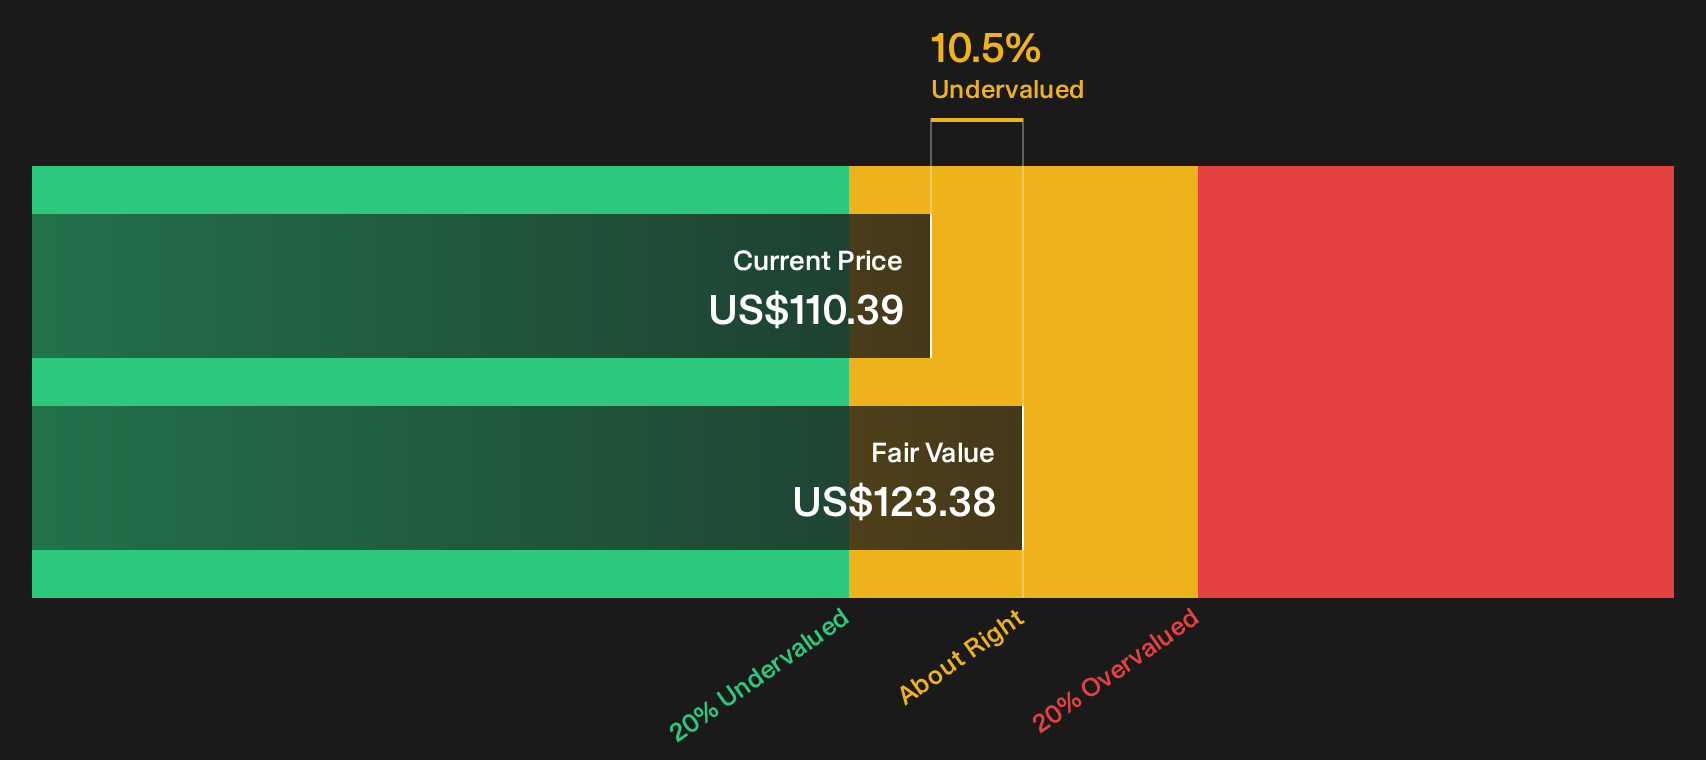
Newmont (NEM)
Overview: Newmont is a global gold producer that operates and explores mines across the Americas, Australia, Africa and the Asia-Pacific region, generating cash flows from its gold focused portfolio.
Operations: Newmont earns most of its revenue from large gold assets including Peñasquito at about US$3.8b, NGM at US$4.6b and Boddington at US$2.8b, with contributions from sites such as Lihir, Yanacocha, Ahafo South and Cadia.
Market Cap: US$113.1b
Newmont matters for a cash flow focused screen because its gold operations generate operating cash that feeds directly into discounted cash flow valuation and can create pricing gaps when sentiment is fixated on commodity swings.
"Newmont's focus on operational stability, cost discipline, and productivity enhancements (e.g., at Lihir, Boddington, and across its core assets) has been cited by management and analysts as a key factor influencing operating costs and EBITDA margins, and as an important part of the company’s margin and net income profile over time."
The development of that margin story depends on how less visible cost pressures unfold relative to production plans and pricing.
How that cost story evolves is exactly what anchors the full narrative for Newmont, revealing where cash flows could be decoupling from sentiment and what that might mean for Newmont’s valuation.
Berkshire Hathaway (BRK.A)
Overview: Berkshire Hathaway is a diversified holding company. Its insurance operations generate recurring cash flows that fund rail, energy, manufacturing, and wide-ranging consumer businesses.
Operations: Berkshire Hathaway earns US$82.99b from Manufacturing, US$50.28b from McLane, US$49.84b from Pilot Travel Centers, and US$94.38b combined across its insurance groups.
Market Cap: US$1.16t
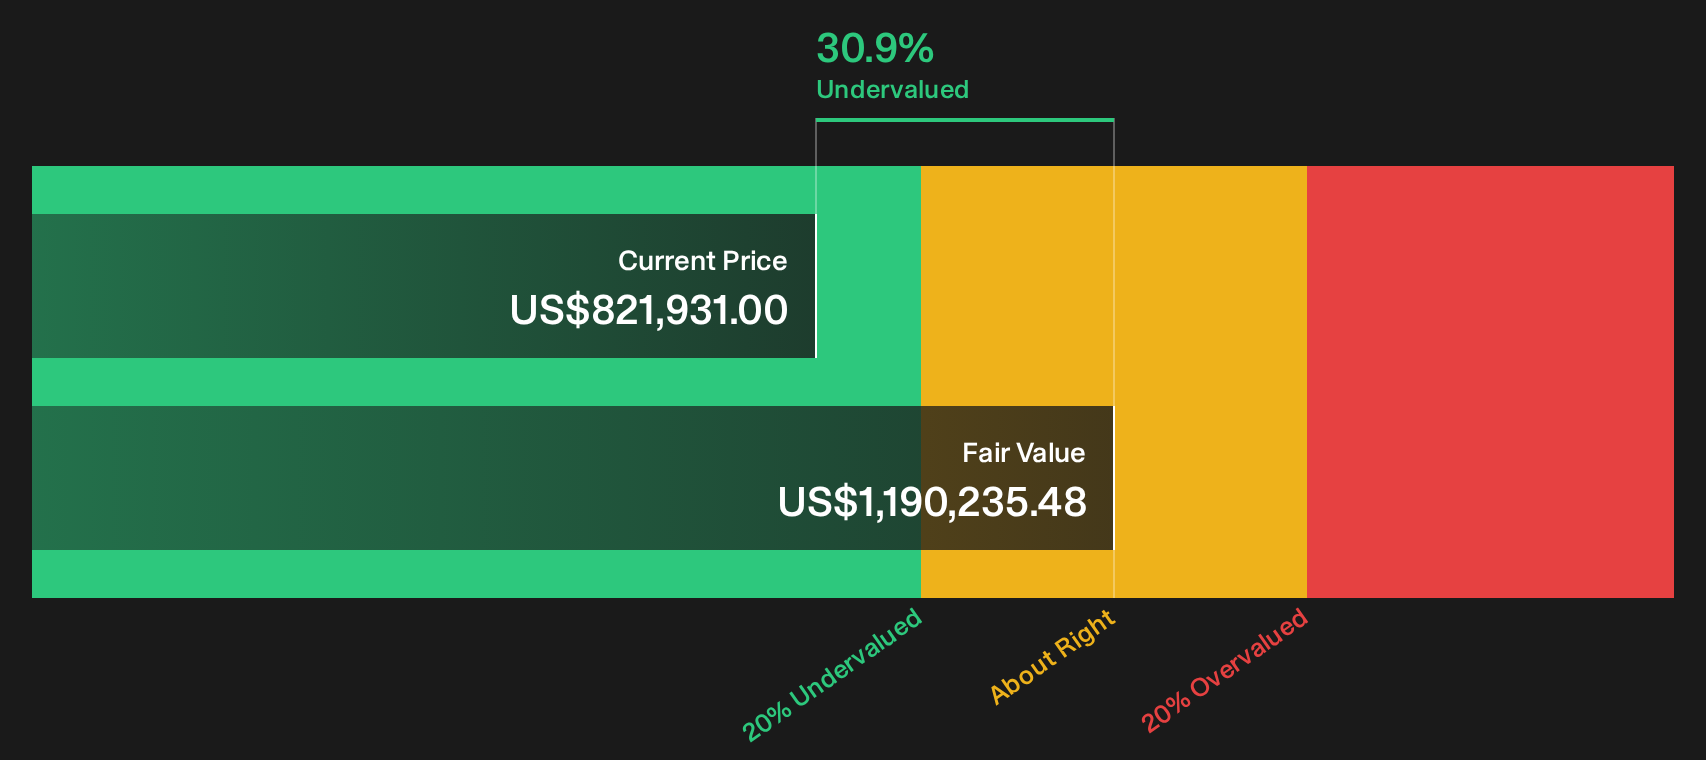
Berkshire Hathaway matters for a cash flow focused screen because its insurance float generates recurring underwriting and investment cash. This can create a gap between the value implied by discounted cash flow models and what the market is currently willing to pay.
"The Cash Fortress: Berkshire's cash and short-term Treasuries hit a staggering, record-breaking $397.4 billion."
What happens to Berkshire Hathaway’s cash flow story if one quiet shift in how that liquidity is deployed changes future earnings power?
If that shift in deployment is what you are weighing, the full narrative for Berkshire Hathaway outlines how Berkshire Hathaway’s cash holdings could either accelerate future earnings power or make it more difficult to see clearly.
F.N.B (FNB)
Overview: F.N.B is a regional banking group that earns interest and fee income by providing lending, deposit, and financial services across its Community Banking, Wealth Management, and Insurance segments.
Operations: F.N.B generates US$1.76b of revenue entirely in the United States through its branch network and related financial services.
Market Cap: US$6.38b
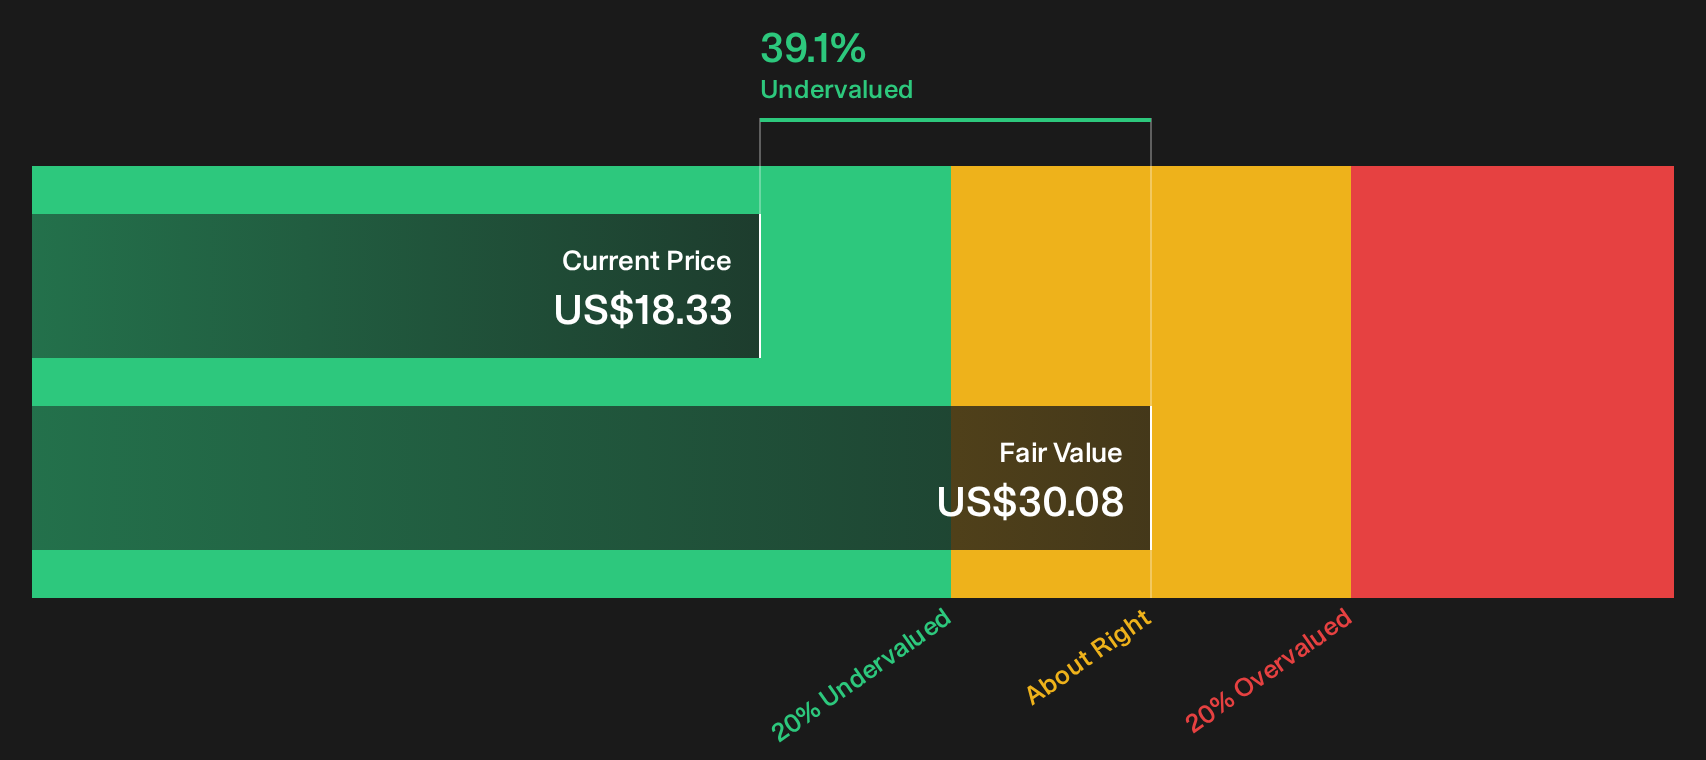
F.N.B is relevant for this cash flow focused screen because its Community Banking lending engine converts mortgage and business activity into recurring interest income that discounted cash flow models can value more precisely than short term sentiment allows.
"F.N.B's ongoing investment in digital and AI tools, including the Insight 360 platform and call center automation expected to be live by the end of 2026, is intended to deepen customer insights and streamline servicing, which could support higher revenue per customer and better net margins."
The key factor is how one quiet shift in customer behaviour interacts with that lending engine to shape future profitability.
That quiet shift is exactly what the full narrative for F.N.B unpacks, separating short term noise from where F.N.B’s cash engine could be accelerating next.
Curious About What You Might Be Missing?
Fresh ideas move first when momentum builds and prices start flying before the crowd notices. Do not get caught chasing late. Scan new themes and get in early.
- Spot cash rich companies holding firm while others drop by scanning a curated set of list of solid balance sheet and fundamentals (24 results) that still fly under most radars.
- Ride long term income momentum by reviewing a hand picked pool of 5 dividend fortresses that combine sizeable yields with balance sheets built to endure.
- Track the next wave of infrastructure demand by checking a focused basket of 42 power grid technology and infrastructure stocks positioned for grid upgrades and electrification trends.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com