
Golden Agri-Resources (SGX:E5H), Why Is Attention Building Around It?
Fresh regulatory warnings from Singapore over haze-linked fires have put Golden Agri-Resources (SGX:E5H) under closer scrutiny, with investors reassessing potential legal, financing and long-term profitability risks priced into the stock.
Over the past month the share price has fallen 16.67% while the 90 day share price return is down 3.51%. Yet Golden Agri-Resources still shows a 1 year total shareholder return of 2.8% and a 5 year total shareholder return of 27.2%, which suggests recent regulatory headlines are pressuring sentiment more than the longer term record.
Compare how the market is pricing Golden Agri-Resources against peers facing similar scrutiny and filter for hand-picked 223 resilient stocks with low risk scores that may carry fewer regulatory and financing pressures.
Regulatory heat has hit Golden Agri-Resources hard in the short term, yet the longer record and current earnings base still matter. Do recent price declines tilt the risk reward toward buyers, or is the discount earned?
Preferred P/E of 6.7x: Is it justified?
On simple valuation math, Golden Agri-Resources trades on a P/E of 6.7x, while the last close sits at just S$0.275. That combination points to a market that is pricing the group at a discount to both its own earnings profile and to comparable food producers.
The P/E ratio compares the share price to earnings per share. For a palm oil and consumer products business like Golden Agri-Resources, it gives a quick sense of how much investors are currently paying for each dollar of profit across plantations, processing, and branded products.
In this context, the 6.7x multiple appears low when set against several data points. The Asian Food industry sits at 14.4x P/E and direct peers average 9.6x, so the stock trades at a steep markdown to both. The fair P/E ratio estimate is 9.5x, which indicates that the current level is materially below that reference point.
Explore the SWS fair ratio for Golden Agri-Resources.
Result: Price-to-earnings of 6.7x (UNDERVALUED)
Still, the haze-related regulatory scrutiny and any tighter financing conditions for Golden Agri-Resources could pressure earnings quality and keep that low P/E from closing quickly.
Find out about the key risks to this Golden Agri-Resources narrative.
Another view using the SWS DCF model
The low P/E points one way, yet the SWS DCF model points another. On this approach, Golden Agri-Resources is flagged as trading at a very large discount, with the S$0.28 share price compared to an estimated future cash flow value of S$3.22. That gap raises a simple question: Is the market overreacting to haze and funding risks, or is the model too generous about future cash generation?
Look into how the SWS DCF model arrives at its fair value.
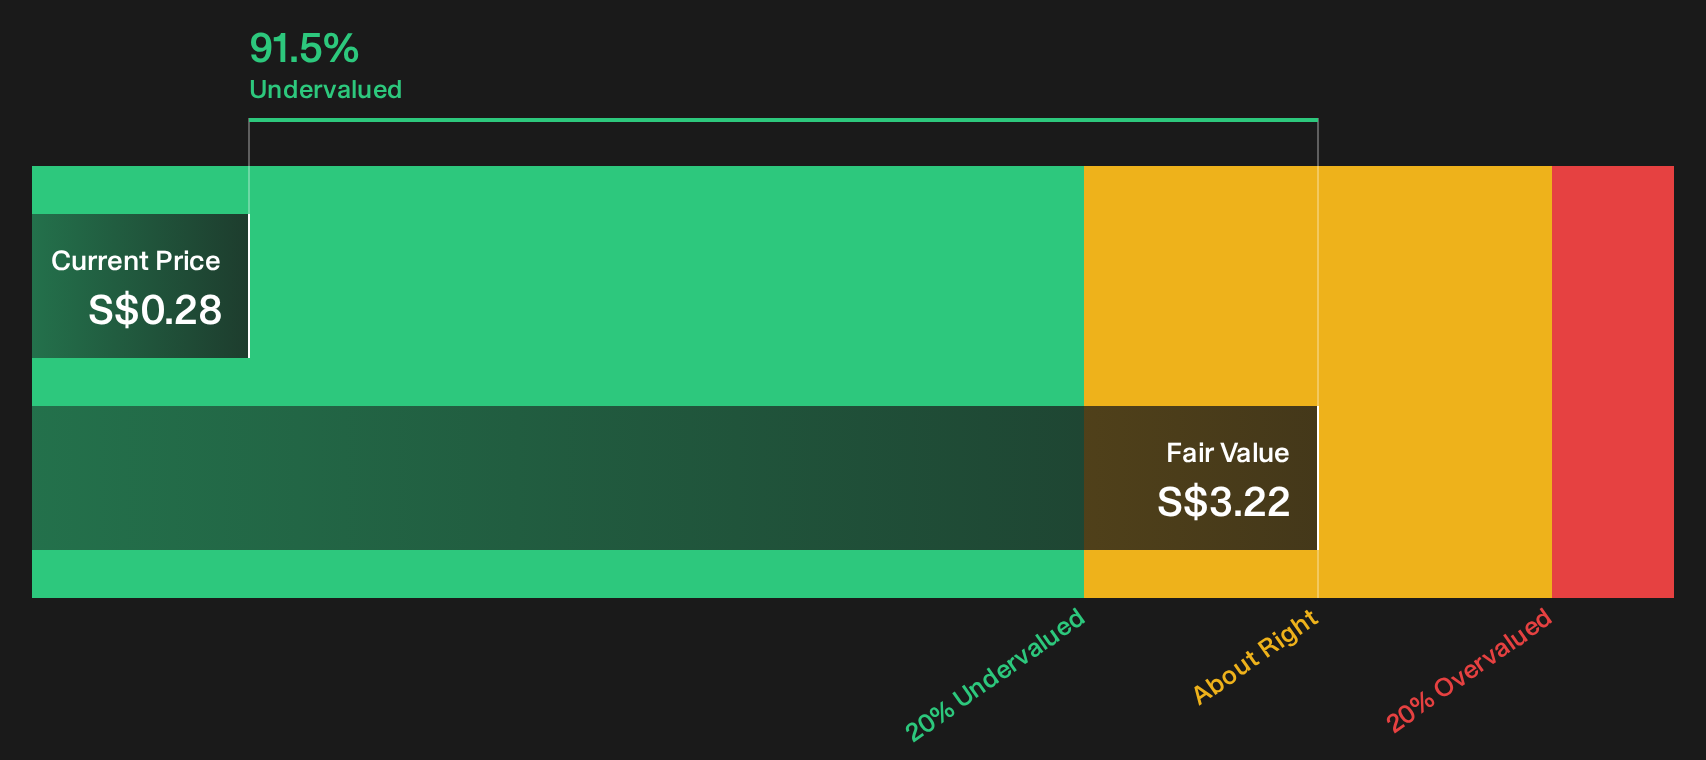
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Golden Agri-Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Golden Agri-Resources can either look like opportunity or a trap, depending on how you read the balance of risk and upside. Act while the data is fresh and stress test your own thesis by weighing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Golden Agri-Resources?
If Golden Agri-Resources has sharpened your focus on risk and valuation, you can broaden your watchlist with fresh ideas filtered for quality, resilience and income potential.
- Target long term compounding potential by scanning a curated pool of quality opportunities with 195 high quality undervalued stocks that balance fundamentals and price.
- Strengthen portfolio resilience by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (207 results) that can better withstand tighter conditions.
- Lock in potential income streams by reviewing a focused group of higher yielding opportunities through the 224 dividend fortresses that prioritise resilient payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com