
Learn Why The Bull Case For Teledyne Technologies Stock Could Change Following Raised Earnings Guidance
- Teledyne Technologies reported third quarter 2026 sales of US$1,684.9 million and net income of US$272.8 million, then raised full year GAAP diluted EPS guidance to a range of US$21.71 to US$21.87.
- The combination of higher quarterly earnings and a tighter, higher full year outlook indicates management confidence in Teledyne Technologies' current demand and cost control.
- The higher full year earnings guidance may influence how investors view Teledyne Technologies' overall investment narrative.
Teledyne Technologies Investment Narrative Recap
To own Teledyne Technologies, you need to be comfortable with a multi year story built around high reliability sensing, imaging and defense exposure, plus disciplined acquisition integration. The raised full year GAAP EPS guidance and solid third quarter earnings both point to execution that currently supports that thesis rather than changing it.
The near term swing factor is how effectively Teledyne Technologies converts its funded backlog into shipments while keeping margins steady as mix shifts toward defense and healthcare imaging. The main risk still sits in supply chain pressures and potential margin dilution from lower gross margin programs, which the latest results do not eliminate.
The updated full year 2026 GAAP diluted EPS outlook of US$21.71 to US$21.87 is the clearest operational signal in this batch of announcements. Management also set fourth quarter 2026 GAAP diluted EPS guidance at US$5.68 to US$5.83, which frames expectations for how the business exits the year on profitability.
Together, these figures give you a reference point for assessing whether the expansion in defense, space sensing and healthcare imaging, plus the planned Varex Imaging acquisition, is flowing through to earnings quality. They also help you weigh execution risk around supply chains, program mix and cost control, which remain central to the Teledyne Technologies catalyst story.
Teledyne Technologies' current earnings are US$974.8 million, with analysts assuming 5.2% yearly revenue growth and projecting revenues of US$7.4b and earnings of US$1.2b by 2029, which implies an earnings increase of about US$225 million from earnings today.
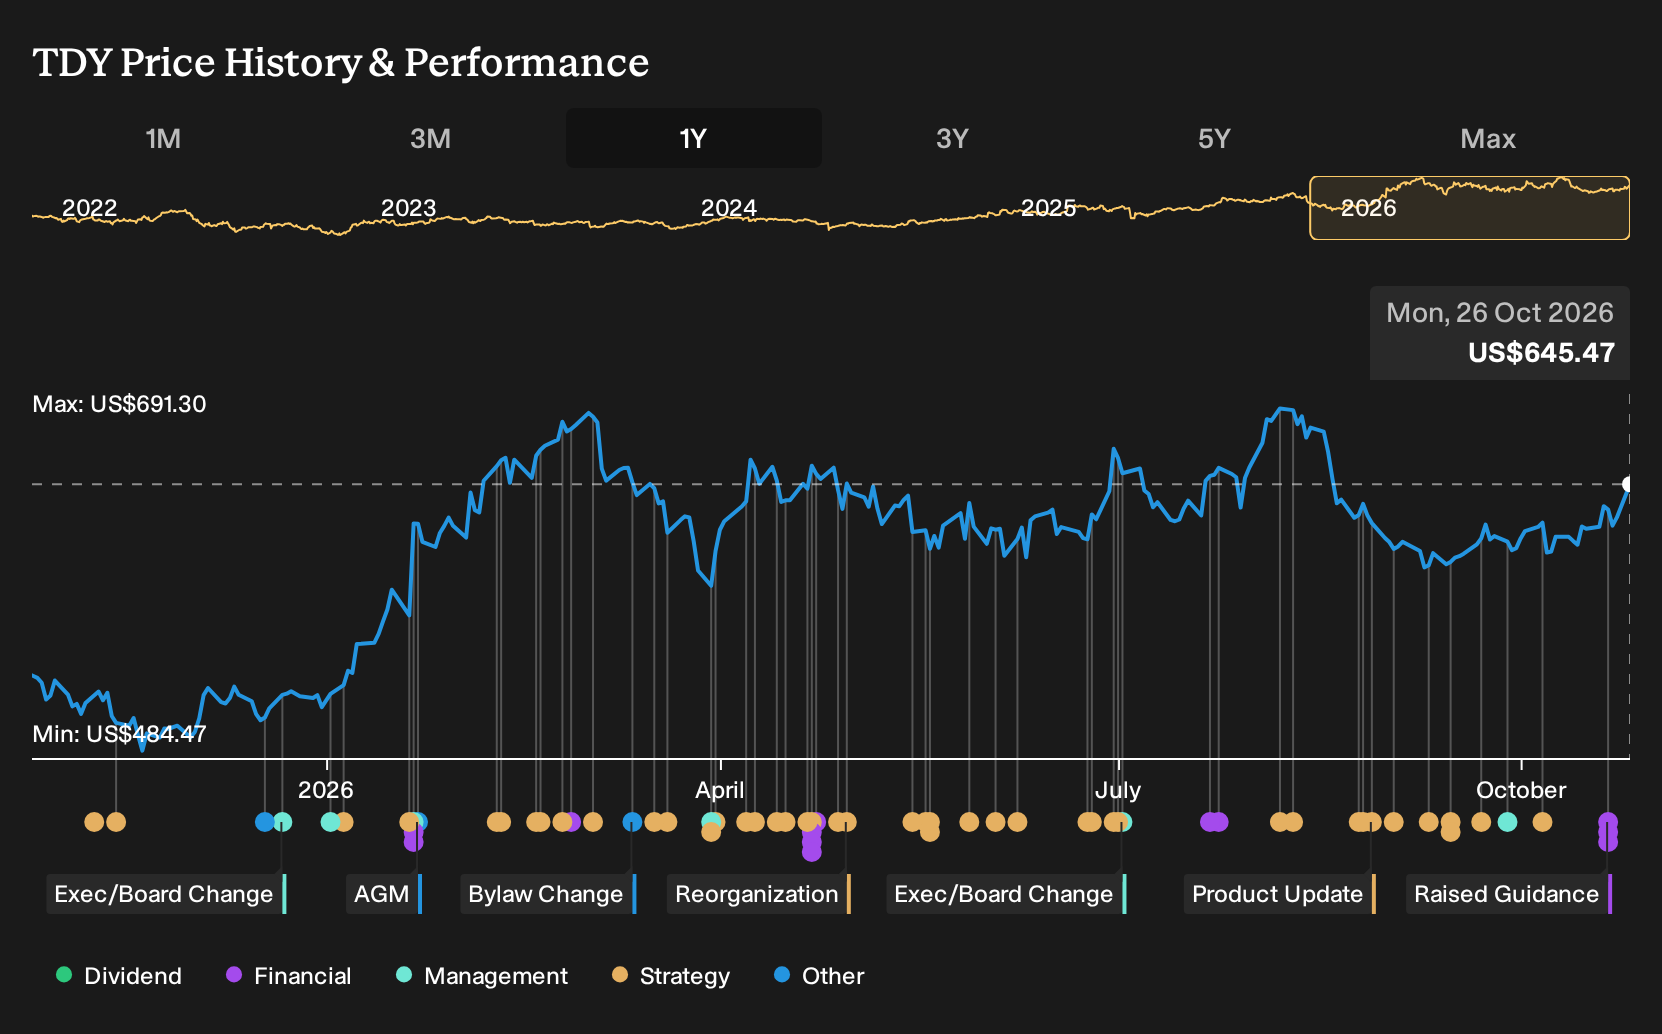
Uncover why Teledyne Technologies' fair value indicates a 17% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit between about US$631.93 and US$758.08 per share, giving you a wide bracket to work with before even factoring in Teledyne Technologies' raised 2026 guidance. When you layer in risks around supply chains, program mix and valuation multiples, you can see why opinions differ, which makes exploring more community views worthwhile.
Explore another Teledyne Technologies fair value estimate, including one that suggests as much as 17% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Teledyne Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teledyne Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teledyne Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Teledyne Technologies?
If the Teledyne Technologies story has sharpened your focus on quality, it can help to widen the lens and compare it with other businesses that share some of the same strengths. The Simply Wall St Screener gives you a quick way to filter for traits you care about, then stack those candidates against Teledyne Technologies on metrics like balance sheet strength, earnings profile and income potential.
- If capital preservation is near the top of your priority list, you could start by reviewing resilient companies that score well on stability and financial risk in the 30 resilient stocks with low risk scores.
- For investors who focus on financial robustness and fundamentals, it may be useful to filter for healthy balance sheets and consistent performance using the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for opportunities that the wider market may not be focusing on yet, you could target under followed businesses with strong underlying metrics through the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com